
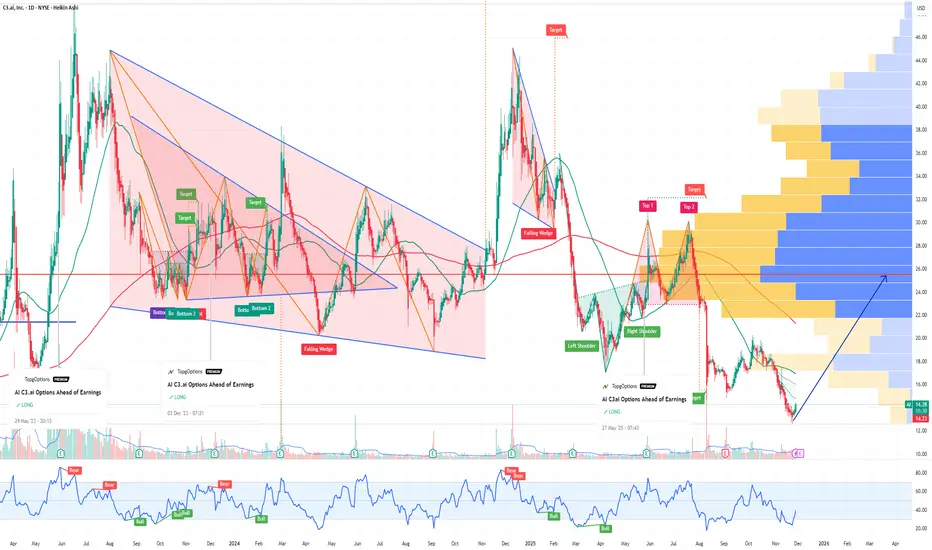
Positioning for the next wave of enterprise AI adoption, rather than the last earnings print:
1. Deepening Microsoft Integration = Real Distribution Power
The most important recent development is C3ai’s expanded collaboration with Microsoft:
C3 ai is now natively integrated across Microsoft Copilot, Microsoft Fabric and Azure AI Foundry, effectively becoming an “intelligence layer” on top of Microsoft’s enterprise stack.
This makes it much easier for large customers already running on Azure and using Copilot to deploy, manage, and scale vertical AI applications from C3ai (manufacturing, energy, financial services, government, etc.).
In simple terms: Microsoft brings the distribution and cloud muscle; C3ai brings vertical AI apps. If this integration starts to convert more pilots into long-term subscriptions, the current depressed valuation may not last.
2. Beaten-Down Expectations + Long Runway
Bears focus on the obvious problems:
Revenue has recently declined and margins are under pressure as C3 ai spends to convert pilots and expand its product suite.
Cash flow is negative, and there’s no GAAP profitability in sight yet.
However, management guides for positive free cash flow by FY26 and non-GAAP profitability in the second half of FY27, with strong revenue growth resuming as production deployments scale.
If those targets prove even roughly correct, the stock today is pricing in a lot of failure. Any upside surprise on:
deal conversions,
operating leverage, or
new, high-profile customer wins via Microsoft’s ecosystem
could trigger a meaningful re-rating from these levels.
3. Macro Headwinds as Future Tailwinds
Recent economic data and rate worries have hit high-growth tech – including C3ai – as investors fled anything with long-dated cash flows.
For a contrarian bull, that’s exactly the kind of environment where:
expectations are low,
sentiment is washed out,
and good news is under-priced.
If the macro picture stabilizes and rate-cut expectations firm up, beaten-down AI names like C3.ai can suddenly look interesting again, especially with a strategic partner like Microsoft in their corner.
AI is a potential buyout candidate, in my opinion.

DAILY HIGH-CONVICTION OPTIONS SIGNALS patreon.com/PremiumOptionsSignals
Options buy freedom24.club/SocialBookTV
RESULTS bit.ly/TG99x
CRYPTOS partner.bybit.com/b/37880
BUY-SELL INDICATORS tradingindicators.store
Options buy freedom24.club/SocialBookTV
RESULTS bit.ly/TG99x
CRYPTOS partner.bybit.com/b/37880
BUY-SELL INDICATORS tradingindicators.store
Related publications
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.