
American Express (Amex) has developed and executed a highly effective, multi-pronged growth playbook that has delivered exceptional returns for shareholders. Over the past five years, the financial giant has generated a total return of 238%, dramatically outperforming the broader market. This success is not accidental; it is the result of a clear, repeatable strategy focused on customer acquisition, engagement, and premium pricing power. Looking ahead, there is a strong, evidence-based conviction that Amex’s business will be larger and more profitable five years from now, though its future stock performance faces the dual forces of robust fundamentals and a premium valuation.
The Core Growth Playbook: A Virtuous Cycle
Management’s confidence is reflected in its ambitious long-term financial targets: revenue growth at a compound annual rate of 10% and diluted earnings per share (EPS) rising at a mid-teens percentage annually. This growth is engineered through a straightforward yet powerful cycle:
Aggressive and Strategic Customer Acquisition: The foundation of the playbook is adding high-quality card members. From Q3 2020 to Q3 2025, Amex increased its active card count by 36% to 151.2 million. Critically, the company is successfully attracting younger, digitally-native consumers. Leadership has highlighted that Gen Z and millennial cohorts are showing particularly strong engagement, ensuring the brand's relevance and customer base longevity.
Maximizing Customer Lifetime Value: Acquisition is only the first step. The true driver of revenue is increasing annual spending per cardholder. Amex has excelled here, with average card member spending reaching $6,387 in Q3 2025—a remarkable 58% increase over the past five years. This growth is fueled by a continuous expansion of the card's utility and appeal. Amex aggressively grows its merchant acceptance network worldwide, making the card more practical for daily use. Simultaneously, it forges valuable partnerships (e.g., in travel, entertainment, and retail) and refines its rewards ecosystem, ensuring the value proposition organically encourages higher spending.
The Power of the Premium Brand: Pricing Power as a Moat
Perhaps Amex’s most formidable competitive advantage is its unrivaled pricing power, a direct result of its powerful brand equity. While many financial services compete on low fees, Amex has successfully built a premium model where customers willingly pay for access.
Strategic Fee Increases: The company periodically and deliberately raises annual fees on its flagship products. Recent examples include the Gold Card fee increasing to $325 and the Platinum Card fee rising to $895. Since Q3 2020, the average annual fee per card has surged 72%. This ability to raise prices without significant customer attrition is a classic sign of a strong brand moat.
The Psychology of Premium Status: Amex transcends being a mere payment tool; it functions as a lifestyle accessory and status signal. For its affluent target demographic, possessing and using a Platinum or Centurion card carries perceived social and professional value. The company meticulously cultivates this image through marketing, exclusive benefits, and a focus on high-spending clientele.
Financial Prudence: This focus on a premium, high-spending customer base has a beneficial financial side effect: superior credit quality. Amex's net charge-off rate was a low 1.9% in Q3 2025, well-controlled compared to broader consumer lending averages. This disciplined underwriting keeps credit losses in check and protects profitability even during economic cycles.
Investment Considerations: Growth vs. Valuation
Despite the compelling business narrative, investors must weigh the robust growth trajectory against current market pricing.
The Valuation Headwind: Following a 29% rise in its share price in 2025 (as of the analysis period), Amex trades at a Price-to-Earnings (P/E) ratio of 25.7. This represents its richest valuation multiple in the past three years and is a premium to many of its financial sector peers. This elevated multiple indicates that much of the company's near-term growth is already priced in by the market, potentially limiting short-term upside and increasing sensitivity to any earnings disappointments.
The Endorsement of a Legendary Investor: A significant counterpoint to valuation concerns is the substantial, long-held stake by Berkshire Hathaway, which owns approximately 22% of American Express shares. Warren Buffett, Berkshire's chairman, is renowned for his focus on durable competitive advantages and long-term holding periods. His continued, sizable investment suggests a fundamental belief that Amex's quality—its brand moat and growth runway—justifies its valuation over a multi-decade horizon.
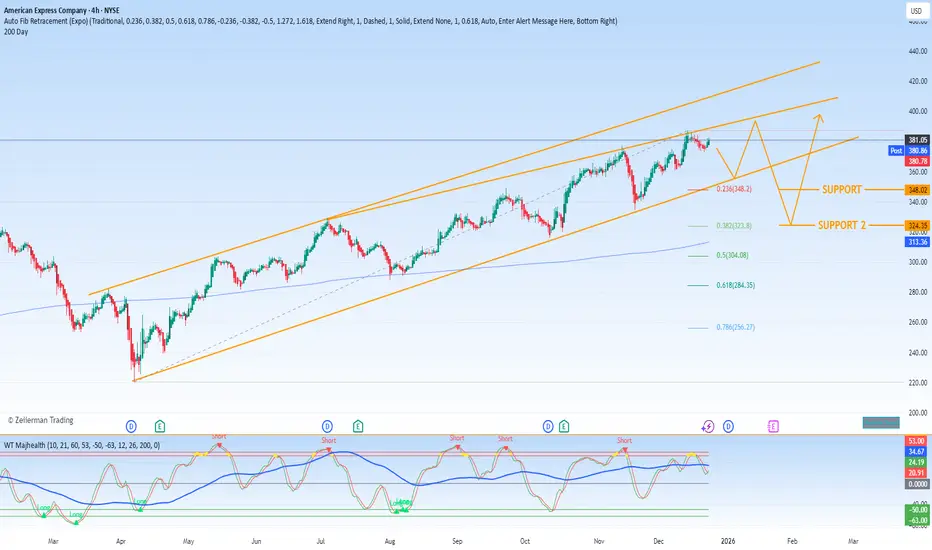
The Technical Perspective: From a market analysis standpoint, the stock's price action identifies two key technical support zones, derived from Fibonacci retracement levels, at approximately $348.20 (the 0.236 level) and $323.80 (the 0.382 level). These levels are watched by traders as potential areas where buying interest may re-emerge during a market pullback.
Five-Year Outlook: Cautious Optimism with Realistic Expectations
The path for American Express stock over the next five years will be shaped by the interplay of two dominant forces:
The Tailwind of Profit Growth: If management successfully executes its playbook and achieves mid-teens annual EPS growth, the underlying earnings power of the company will increase substantially, providing a fundamental lift to the stock price.
The Headwind of Valuation Compression: The current high P/E ratio of 25.7 may not be sustainable indefinitely. A gradual normalization or contraction of this multiple over time could act as a drag on share price appreciation, even as earnings grow.
Conclusion: The thesis that American Express will be a larger, more powerful business in five years is highly credible, supported by its proven growth strategy, pricing power, and brand strength. However, for the stock to significantly outperform the overall market from its current levels, the company will likely need to exceed its already ambitious growth targets to justify and maintain its premium valuation. While the stock is expected to trend higher, its performance may be more aligned with market returns rather than dramatically surpassing them, barring an acceleration in its growth narrative. The confidence of long-term investors like Buffett offers reassurance, but it does not eliminate the mathematical constraints imposed by today's elevated starting valuation.
The Core Growth Playbook: A Virtuous Cycle
Management’s confidence is reflected in its ambitious long-term financial targets: revenue growth at a compound annual rate of 10% and diluted earnings per share (EPS) rising at a mid-teens percentage annually. This growth is engineered through a straightforward yet powerful cycle:
Aggressive and Strategic Customer Acquisition: The foundation of the playbook is adding high-quality card members. From Q3 2020 to Q3 2025, Amex increased its active card count by 36% to 151.2 million. Critically, the company is successfully attracting younger, digitally-native consumers. Leadership has highlighted that Gen Z and millennial cohorts are showing particularly strong engagement, ensuring the brand's relevance and customer base longevity.
Maximizing Customer Lifetime Value: Acquisition is only the first step. The true driver of revenue is increasing annual spending per cardholder. Amex has excelled here, with average card member spending reaching $6,387 in Q3 2025—a remarkable 58% increase over the past five years. This growth is fueled by a continuous expansion of the card's utility and appeal. Amex aggressively grows its merchant acceptance network worldwide, making the card more practical for daily use. Simultaneously, it forges valuable partnerships (e.g., in travel, entertainment, and retail) and refines its rewards ecosystem, ensuring the value proposition organically encourages higher spending.
The Power of the Premium Brand: Pricing Power as a Moat
Perhaps Amex’s most formidable competitive advantage is its unrivaled pricing power, a direct result of its powerful brand equity. While many financial services compete on low fees, Amex has successfully built a premium model where customers willingly pay for access.
Strategic Fee Increases: The company periodically and deliberately raises annual fees on its flagship products. Recent examples include the Gold Card fee increasing to $325 and the Platinum Card fee rising to $895. Since Q3 2020, the average annual fee per card has surged 72%. This ability to raise prices without significant customer attrition is a classic sign of a strong brand moat.
The Psychology of Premium Status: Amex transcends being a mere payment tool; it functions as a lifestyle accessory and status signal. For its affluent target demographic, possessing and using a Platinum or Centurion card carries perceived social and professional value. The company meticulously cultivates this image through marketing, exclusive benefits, and a focus on high-spending clientele.
Financial Prudence: This focus on a premium, high-spending customer base has a beneficial financial side effect: superior credit quality. Amex's net charge-off rate was a low 1.9% in Q3 2025, well-controlled compared to broader consumer lending averages. This disciplined underwriting keeps credit losses in check and protects profitability even during economic cycles.
Investment Considerations: Growth vs. Valuation
Despite the compelling business narrative, investors must weigh the robust growth trajectory against current market pricing.
The Valuation Headwind: Following a 29% rise in its share price in 2025 (as of the analysis period), Amex trades at a Price-to-Earnings (P/E) ratio of 25.7. This represents its richest valuation multiple in the past three years and is a premium to many of its financial sector peers. This elevated multiple indicates that much of the company's near-term growth is already priced in by the market, potentially limiting short-term upside and increasing sensitivity to any earnings disappointments.
The Endorsement of a Legendary Investor: A significant counterpoint to valuation concerns is the substantial, long-held stake by Berkshire Hathaway, which owns approximately 22% of American Express shares. Warren Buffett, Berkshire's chairman, is renowned for his focus on durable competitive advantages and long-term holding periods. His continued, sizable investment suggests a fundamental belief that Amex's quality—its brand moat and growth runway—justifies its valuation over a multi-decade horizon.
The Technical Perspective: From a market analysis standpoint, the stock's price action identifies two key technical support zones, derived from Fibonacci retracement levels, at approximately $348.20 (the 0.236 level) and $323.80 (the 0.382 level). These levels are watched by traders as potential areas where buying interest may re-emerge during a market pullback.
Five-Year Outlook: Cautious Optimism with Realistic Expectations
The path for American Express stock over the next five years will be shaped by the interplay of two dominant forces:
The Tailwind of Profit Growth: If management successfully executes its playbook and achieves mid-teens annual EPS growth, the underlying earnings power of the company will increase substantially, providing a fundamental lift to the stock price.
The Headwind of Valuation Compression: The current high P/E ratio of 25.7 may not be sustainable indefinitely. A gradual normalization or contraction of this multiple over time could act as a drag on share price appreciation, even as earnings grow.
Conclusion: The thesis that American Express will be a larger, more powerful business in five years is highly credible, supported by its proven growth strategy, pricing power, and brand strength. However, for the stock to significantly outperform the overall market from its current levels, the company will likely need to exceed its already ambitious growth targets to justify and maintain its premium valuation. While the stock is expected to trend higher, its performance may be more aligned with market returns rather than dramatically surpassing them, barring an acceleration in its growth narrative. The confidence of long-term investors like Buffett offers reassurance, but it does not eliminate the mathematical constraints imposed by today's elevated starting valuation.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.