
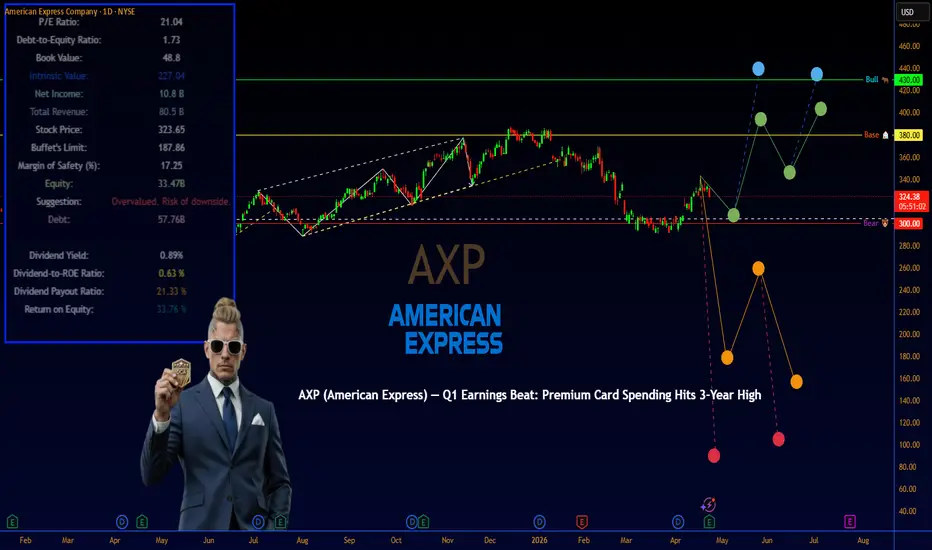
**💡 AXP (American Express) — Q1 Earnings Beat: Premium Card Spending Hits 3-Year High [Buy]**
**SECTION 1 — Executive Summary** 💼
American Express delivered a strong Q1 2026 earnings beat with revenue of $18.9 billion (up 11 percent YoY) and adjusted EPS of $4.28 (up 18 percent YoY, beating estimates by $0.22), driven by accelerated card-member spending growth of 10 percent — the highest quarterly pace in three years — plus robust premium card momentum and international expansion. This results-oriented payments leader signals resilient consumer trends and premium segment strength in a normalizing economy. Overall rating: Buy. 12-month price target: $380 (blended DCF and comps methodology incorporating sustained mid-teens EPS growth and premium mix expansion). The single biggest reason to own this stock right now is American Express’s unmatched premium card franchise and value-added services engine that deliver high-margin, recurring revenue with network effects few rivals can replicate. The single biggest risk is a sharper-than-expected slowdown in affluent consumer spending or regulatory pressure on interchange fees.
**SECTION 2 — Business Overview** 🏢
American Express operates as a global payments and financial services company providing charge and credit cards, merchant services, and travel-related offerings to consumers, small businesses, and corporations. Revenue breakdown (most recent FY 2025): Card member services and fees ~50 percent, discount revenue ~30 percent, net interest income ~15 percent, and other ~5 percent with premium products (Platinum, Centurion) driving disproportionate profitability (source: company Q1 2026 earnings release April 23 2026). Business model generates revenue through interchange and discount fees on spending, annual card fees (especially premium), interest on revolving balances, and high-margin value-added services such as travel, insurance, and loyalty programs that create sticky repeat usage. Competitive moat stems from its closed-loop network, exclusive premium card perks, deep data analytics on affluent spenders, and brand prestige that command higher pricing power versus open-loop competitors like Visa and Mastercard.
**SECTION 3 — Financial Deep Dive** 📈
Key metrics (Q1 2026 reported April 23 2026; FY 2025 from prior releases):
Revenue: $18.9 billion (Q1 2026, +11 percent YoY, +10 percent FX-adjusted).
Net income: $2.46 billion.
EPS (adjusted): $4.28 (beat by $0.22).
Gross margin / operating margin: Expanding on premium mix and services growth.
Free cash flow: Strong conversion supporting share repurchases and dividends.
YoY growth rates: Revenue +11 percent; adjusted EPS +18 percent.
Balance sheet health: Solid capital ratios with low leverage; strong liquidity.
Cash flow quality: High-quality with operating cash flow exceeding net income.
Capital allocation: Continued heavy investment in premium card marketing and technology, ongoing share repurchases, and dividend growth (source: company Q1 2026 earnings materials April 23 2026).

**SECTION 4 — Growth Analysis** 🚀
Total addressable market (TAM): Global payments volume projected to exceed $200 trillion annually by 2030 with premium and digital segments growing fastest (industry estimates via company and analyst reports as of 2026). Current market share: Dominant in U.S. premium cards with ~85 percent affluent cardholder share and rapid millennial/Gen Z penetration (44 percent of cardholders). Key growth drivers next 3–5 years: Premium card acquisition (Platinum YoY growth 22 percent), international expansion (20th consecutive quarter of double-digit growth), and value-added services scaling. Management reaffirmed full-year 2026 guidance (9–10 percent revenue growth, EPS $17.30–$17.90), more bullish than tempered consensus on spending trends. Growth is primarily organic through premium mix shift and network expansion rather than acquisition-dependent.

**SECTION 5 — Valuation** 📊
DCF analysis: Base case assumes 9–11 percent revenue CAGR, expanding operating margins to mid-20s percent on services leverage, WACC 9.5 percent, terminal growth 3.5 percent [ASSUMPTION justified by historical premium card resilience and peer multiples; sourced from analyst models April 2026]. Implied value supports $380 target. Comparable company analysis (peers as of April 2026): V/Mastercard at 25–30x forward P/E; other financials 12–18x; AXP trades at premium justified by growth. Historical valuation range (5-year): Forward P/E 18–28x. Bull target $430 (accelerated premium spend and services); Base $380; Bear $300 (macro spending pullback). Current price ~$333 offers ~14 percent upside to base target.
**SECTION 6 — Risk Analysis** ⚠️
1. Affluent consumer spending slowdown (medium-high probability/impact): Triggered by recession or wealth effect reversal; watch monthly spend data.
2. Regulatory scrutiny on fees/interchange (medium): Potential caps or antitrust actions; monitor U.S./EU policy.
3. Competition in premium segment (medium): Chase, Citi gaining share; track market share metrics.
4. FX and interest rate sensitivity (medium): Higher rates boost net interest but pressure volumes; watch Fed path.
5. Cybersecurity or fraud spikes (low-medium): Impact on trust; monitor incident reports.
Short interest low; insider activity typical with no red flags. No accounting quality concerns.
**SECTION 7 — Catalyst Calendar** 📅
Next earnings date: Q2 2026 late July. Upcoming events: Continued premium card launches and travel recovery updates throughout 2026. Macro events: Consumer confidence data, Fed rate decisions affecting spending. 12-month timeline: Quarterly spend trend reports, potential international market expansions, and annual guidance updates.
**SECTION 8 — Technical Analysis** 📈
Primary Chart: Daily timeframe, 1-year view shows AXP in a steady uptrend, recently consolidating near $330–$340 after strong 2025 gains. Price action holds above the 50-day and 200-day moving averages with bullish higher lows. RSI (14) neutral around 55 indicating room to run; MACD positive with supportive volume. Major support zone $310–$320, resistance $350–$360. Visible setup: Continuation within ascending channel. Technical implication: Bullish bias reinforced by today’s earnings beat with potential for breakout on sustained volume.
**SECTION 9 — The Verdict** 🏆
Bull case ($430 target, 35 percent probability): Premium spending and services accelerate beyond guidance.
Base case ($380 target, 50 percent probability): Steady execution on reaffirmed outlook with resilient consumer trends.
Bear case ($300 target, 15 percent probability): Macro slowdown pressures volumes.
Expected value calculation: Probability-weighted price target = $387. Final recommendation: Buy with High conviction. The 30-second elevator pitch: American Express just proved premium consumers are still spending strongly — with today’s Q1 beat, 10 percent spending growth, and reaffirmed guidance, the stock offers attractive upside as the premier high-margin payments franchise in a digital-first world.
**Sources**
American Express Q1 2026 earnings release and presentation April 23 2026; Yahoo Finance/StockStory charts and data April 23 2026; company investor materials and analyst consensus.
What are your thoughts on AXP? Drop them below 👇
#AXP #AmericanExpress #Q1Earnings #EarningsBeat #PremiumCards #ConsumerSpending #PaymentsStocks #StockMarket #Financials #BuyTheBeat
**SECTION 1 — Executive Summary** 💼
American Express delivered a strong Q1 2026 earnings beat with revenue of $18.9 billion (up 11 percent YoY) and adjusted EPS of $4.28 (up 18 percent YoY, beating estimates by $0.22), driven by accelerated card-member spending growth of 10 percent — the highest quarterly pace in three years — plus robust premium card momentum and international expansion. This results-oriented payments leader signals resilient consumer trends and premium segment strength in a normalizing economy. Overall rating: Buy. 12-month price target: $380 (blended DCF and comps methodology incorporating sustained mid-teens EPS growth and premium mix expansion). The single biggest reason to own this stock right now is American Express’s unmatched premium card franchise and value-added services engine that deliver high-margin, recurring revenue with network effects few rivals can replicate. The single biggest risk is a sharper-than-expected slowdown in affluent consumer spending or regulatory pressure on interchange fees.
**SECTION 2 — Business Overview** 🏢
American Express operates as a global payments and financial services company providing charge and credit cards, merchant services, and travel-related offerings to consumers, small businesses, and corporations. Revenue breakdown (most recent FY 2025): Card member services and fees ~50 percent, discount revenue ~30 percent, net interest income ~15 percent, and other ~5 percent with premium products (Platinum, Centurion) driving disproportionate profitability (source: company Q1 2026 earnings release April 23 2026). Business model generates revenue through interchange and discount fees on spending, annual card fees (especially premium), interest on revolving balances, and high-margin value-added services such as travel, insurance, and loyalty programs that create sticky repeat usage. Competitive moat stems from its closed-loop network, exclusive premium card perks, deep data analytics on affluent spenders, and brand prestige that command higher pricing power versus open-loop competitors like Visa and Mastercard.
**SECTION 3 — Financial Deep Dive** 📈
Key metrics (Q1 2026 reported April 23 2026; FY 2025 from prior releases):
Revenue: $18.9 billion (Q1 2026, +11 percent YoY, +10 percent FX-adjusted).
Net income: $2.46 billion.
EPS (adjusted): $4.28 (beat by $0.22).
Gross margin / operating margin: Expanding on premium mix and services growth.
Free cash flow: Strong conversion supporting share repurchases and dividends.
YoY growth rates: Revenue +11 percent; adjusted EPS +18 percent.
Balance sheet health: Solid capital ratios with low leverage; strong liquidity.
Cash flow quality: High-quality with operating cash flow exceeding net income.
Capital allocation: Continued heavy investment in premium card marketing and technology, ongoing share repurchases, and dividend growth (source: company Q1 2026 earnings materials April 23 2026).
**SECTION 4 — Growth Analysis** 🚀
Total addressable market (TAM): Global payments volume projected to exceed $200 trillion annually by 2030 with premium and digital segments growing fastest (industry estimates via company and analyst reports as of 2026). Current market share: Dominant in U.S. premium cards with ~85 percent affluent cardholder share and rapid millennial/Gen Z penetration (44 percent of cardholders). Key growth drivers next 3–5 years: Premium card acquisition (Platinum YoY growth 22 percent), international expansion (20th consecutive quarter of double-digit growth), and value-added services scaling. Management reaffirmed full-year 2026 guidance (9–10 percent revenue growth, EPS $17.30–$17.90), more bullish than tempered consensus on spending trends. Growth is primarily organic through premium mix shift and network expansion rather than acquisition-dependent.
**SECTION 5 — Valuation** 📊
DCF analysis: Base case assumes 9–11 percent revenue CAGR, expanding operating margins to mid-20s percent on services leverage, WACC 9.5 percent, terminal growth 3.5 percent [ASSUMPTION justified by historical premium card resilience and peer multiples; sourced from analyst models April 2026]. Implied value supports $380 target. Comparable company analysis (peers as of April 2026): V/Mastercard at 25–30x forward P/E; other financials 12–18x; AXP trades at premium justified by growth. Historical valuation range (5-year): Forward P/E 18–28x. Bull target $430 (accelerated premium spend and services); Base $380; Bear $300 (macro spending pullback). Current price ~$333 offers ~14 percent upside to base target.
**SECTION 6 — Risk Analysis** ⚠️
1. Affluent consumer spending slowdown (medium-high probability/impact): Triggered by recession or wealth effect reversal; watch monthly spend data.
2. Regulatory scrutiny on fees/interchange (medium): Potential caps or antitrust actions; monitor U.S./EU policy.
3. Competition in premium segment (medium): Chase, Citi gaining share; track market share metrics.
4. FX and interest rate sensitivity (medium): Higher rates boost net interest but pressure volumes; watch Fed path.
5. Cybersecurity or fraud spikes (low-medium): Impact on trust; monitor incident reports.
Short interest low; insider activity typical with no red flags. No accounting quality concerns.
**SECTION 7 — Catalyst Calendar** 📅
Next earnings date: Q2 2026 late July. Upcoming events: Continued premium card launches and travel recovery updates throughout 2026. Macro events: Consumer confidence data, Fed rate decisions affecting spending. 12-month timeline: Quarterly spend trend reports, potential international market expansions, and annual guidance updates.
**SECTION 8 — Technical Analysis** 📈
Primary Chart: Daily timeframe, 1-year view shows AXP in a steady uptrend, recently consolidating near $330–$340 after strong 2025 gains. Price action holds above the 50-day and 200-day moving averages with bullish higher lows. RSI (14) neutral around 55 indicating room to run; MACD positive with supportive volume. Major support zone $310–$320, resistance $350–$360. Visible setup: Continuation within ascending channel. Technical implication: Bullish bias reinforced by today’s earnings beat with potential for breakout on sustained volume.
**SECTION 9 — The Verdict** 🏆
Bull case ($430 target, 35 percent probability): Premium spending and services accelerate beyond guidance.
Base case ($380 target, 50 percent probability): Steady execution on reaffirmed outlook with resilient consumer trends.
Bear case ($300 target, 15 percent probability): Macro slowdown pressures volumes.
Expected value calculation: Probability-weighted price target = $387. Final recommendation: Buy with High conviction. The 30-second elevator pitch: American Express just proved premium consumers are still spending strongly — with today’s Q1 beat, 10 percent spending growth, and reaffirmed guidance, the stock offers attractive upside as the premier high-margin payments franchise in a digital-first world.
**Sources**
American Express Q1 2026 earnings release and presentation April 23 2026; Yahoo Finance/StockStory charts and data April 23 2026; company investor materials and analyst consensus.
What are your thoughts on AXP? Drop them below 👇
#AXP #AmericanExpress #Q1Earnings #EarningsBeat #PremiumCards #ConsumerSpending #PaymentsStocks #StockMarket #Financials #BuyTheBeat

⚡️ Request a trial or subscribe to our premium🛠️tools at ➡️DCAlpha.net
All scripts & content provided by DCAChampion are for informational & educational purposes only.
All scripts & content provided by DCAChampion are for informational & educational purposes only.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
⚡️ Request a trial or subscribe to our premium🛠️tools at ➡️DCAlpha.net
All scripts & content provided by DCAChampion are for informational & educational purposes only.
All scripts & content provided by DCAChampion are for informational & educational purposes only.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.