
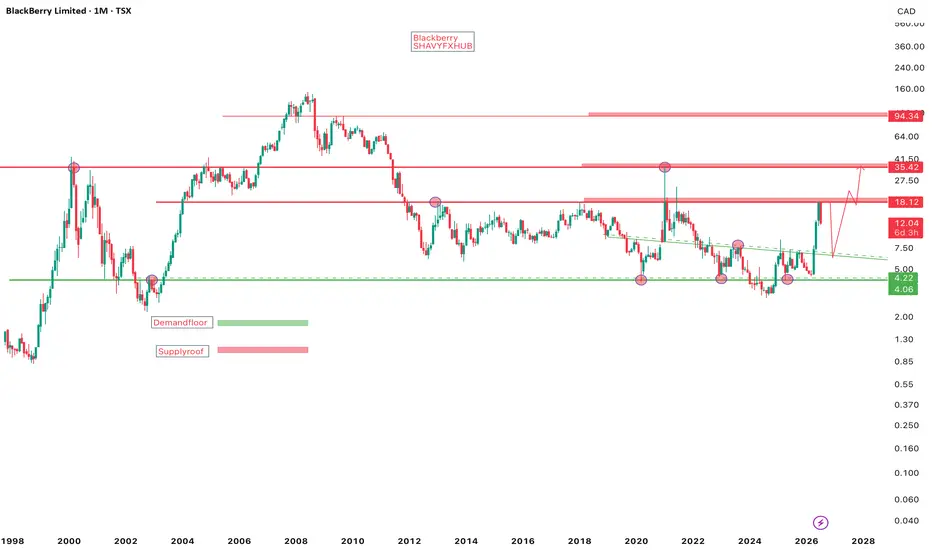
(BlackBerry monthly, shows the classic long-term decline from the 2007–2008 peak (~CAD 140+ area). Major horizontal supply roofs sit near ~94, ~35–41, and ~18. A persistent demand floor/green zone is marked around ~4.00–5.00 (with labels “Demandfloor” and “Supplyroof”). A descending green trendline from the mid-2010s highs has been broken or challenged on the recent advance. Price rallied strongly from the ~4 zone, spiked toward/through the ~18 area (and briefly higher), then pulled back sharply—the chart notes a recent ~–5.87 (–32.77%) move, consistent with the July 2026 price action from a local high near ~18.45 CAD down toward ~12. 
In Shavyfxhub terms (market structure + character, demand/supply, liquidity, break-and-retest):
• The multi-year base at the demand floor (~4–5) acted as a strong accumulation zone with repeated reactions.
• The 2026 rally represents a change of character / break of the prior descending structure and intermediate supply.
• The current pullback is testing prior breakout/structure zones (near the ~12–18 band and the broken descending trendline area). Hold above the demand floor keeps the higher-timeframe bullish structure intact; a sustained break back below ~4–5 would reassert the long-term bearish character.
• Key levels to watch for reactions (rejections or break-and-retests): ; higher supply ~35–41 / 94+. Volume and candle closes on the monthly (and lower timeframes) confirm character shifts.
Business model driving the rise since April 2026: BlackBerry is no longer a phone company. It is a software firm focused on two main engines: QNX (real-time embedded OS for automotive, industrial, robotics/medical “physical AI,” and general embedded markets) and Secure Communications (government/enterprise-grade secure messaging, voice, crisis management/AtHoc, digital sovereignty solutions). There is also patent/licensing revenue. 
Key drivers of the 2026 rally (from ~CAD 4–5 / US ~3.8 early year toward peaks near CAD 18+ / US ~13.6):
• Strong Q4 FY2026 and especially Q1 FY2027 results (ended May 2026): revenue ~US$153M (+26% YoY), adjusted EBITDA more than doubled, both segments hitting “Rule of 40,” positive cash flow milestones, raised full-year guidance (revenue ~US$594–621M range).
• QNX strength: embedded in 275M+ vehicles, development licenses at multi-quarter highs (leading indicator for future royalties), ~US$950M royalty backlog earlier, expansion beyond auto into robotics/industrial/medical via partnerships (notably expanded NVIDIA collaboration for edge AI/safety-critical systems).
• Secure Communications: government demand for digital sovereignty, cybersecurity modernization, contracts (e.g., Canadian government expansion), high retention, and recurring revenue.
• Completed turnaround narrative (Cylance sold earlier, focus narrowed, consecutive profitable quarters, cost discipline), share buybacks, and institutional/analyst interest shifting from “meme” to growth/software/AI-adjacent story. 
Will the trajectory continue after the pullback? The fundamental momentum (QNX design wins, physical AI/robotics optionality, government secure-comms tailwinds, improved profitability/cash generation) supports a constructive multi-year case if execution continues and guidance is met. The chart’s higher-timeframe structure remains constructive above the long-term demand floor. However, after a ~130–180%+ YTD surge into elevated valuations (high forward multiples relative to peers/history), profit-taking, volatility, and mean-reversion risk are high—exactly what the July pullback reflects. Continuation higher requires holding key structure (reclaim/hold above intermediate levels, successful retests of broken supply as demand) plus ongoing fundamental delivery. A deeper retest of the demand floor is possible without invalidating the broader turnaround; failure there would reopen downside. This is not financial advice—markets can remain irrational and past performance is no guarantee.
Why the BlackBerry phone and consumer messaging app collapsed: BlackBerry (then RIM) dominated enterprise/mobile email and secure messaging in the early-to-mid 2000s with physical keyboards and its ecosystem. The iPhone (2007) and Android smartphones rapidly shifted the market to touchscreens, rich app ecosystems, consumer media, and developer support. BlackBerry was slow to adapt (late/imperfect touch devices, BlackBerry 10 OS struggles, internal strategy disagreements, over-reliance on keyboard/enterprise strengths). Market share collapsed; by the mid-2010s it was negligible. Hardware was effectively exited by ~2016 (later limited licensing attempts failed to revive it). Classic devices lost network support in 2022 as the company fully pivoted to software. 
Consumer BBM (BlackBerry Messenger) was once highly popular for secure/group messaging. It was licensed out (to Emtek in Indonesia around 2016); the consumer version shut down in 2019 because users migrated to WhatsApp, iMessage, etc., and new-user acquisition failed despite efforts. The enterprise-grade version (BBM Enterprise / secure messaging tools) continued and evolved into part of the Secure Communications portfolio. 
In short: the phone/messaging consumer era ended due to failure to compete in the post-iPhone smartphone platform shift. The surviving business is the software pivot (QNX + secure gov/enterprise tools) that has driven the 2026 re-rating. The monthly chart’s demand-floor base and recent structural break align with that fundamental shift, while the current pullback is a classic post-rally test .
#blackberry
In Shavyfxhub terms (market structure + character, demand/supply, liquidity, break-and-retest):
• The multi-year base at the demand floor (~4–5) acted as a strong accumulation zone with repeated reactions.
• The 2026 rally represents a change of character / break of the prior descending structure and intermediate supply.
• The current pullback is testing prior breakout/structure zones (near the ~12–18 band and the broken descending trendline area). Hold above the demand floor keeps the higher-timeframe bullish structure intact; a sustained break back below ~4–5 would reassert the long-term bearish character.
• Key levels to watch for reactions (rejections or break-and-retests): ; higher supply ~35–41 / 94+. Volume and candle closes on the monthly (and lower timeframes) confirm character shifts.
Business model driving the rise since April 2026: BlackBerry is no longer a phone company. It is a software firm focused on two main engines: QNX (real-time embedded OS for automotive, industrial, robotics/medical “physical AI,” and general embedded markets) and Secure Communications (government/enterprise-grade secure messaging, voice, crisis management/AtHoc, digital sovereignty solutions). There is also patent/licensing revenue. 
Key drivers of the 2026 rally (from ~CAD 4–5 / US ~3.8 early year toward peaks near CAD 18+ / US ~13.6):
• Strong Q4 FY2026 and especially Q1 FY2027 results (ended May 2026): revenue ~US$153M (+26% YoY), adjusted EBITDA more than doubled, both segments hitting “Rule of 40,” positive cash flow milestones, raised full-year guidance (revenue ~US$594–621M range).
• QNX strength: embedded in 275M+ vehicles, development licenses at multi-quarter highs (leading indicator for future royalties), ~US$950M royalty backlog earlier, expansion beyond auto into robotics/industrial/medical via partnerships (notably expanded NVIDIA collaboration for edge AI/safety-critical systems).
• Secure Communications: government demand for digital sovereignty, cybersecurity modernization, contracts (e.g., Canadian government expansion), high retention, and recurring revenue.
• Completed turnaround narrative (Cylance sold earlier, focus narrowed, consecutive profitable quarters, cost discipline), share buybacks, and institutional/analyst interest shifting from “meme” to growth/software/AI-adjacent story. 
Will the trajectory continue after the pullback? The fundamental momentum (QNX design wins, physical AI/robotics optionality, government secure-comms tailwinds, improved profitability/cash generation) supports a constructive multi-year case if execution continues and guidance is met. The chart’s higher-timeframe structure remains constructive above the long-term demand floor. However, after a ~130–180%+ YTD surge into elevated valuations (high forward multiples relative to peers/history), profit-taking, volatility, and mean-reversion risk are high—exactly what the July pullback reflects. Continuation higher requires holding key structure (reclaim/hold above intermediate levels, successful retests of broken supply as demand) plus ongoing fundamental delivery. A deeper retest of the demand floor is possible without invalidating the broader turnaround; failure there would reopen downside. This is not financial advice—markets can remain irrational and past performance is no guarantee.
Why the BlackBerry phone and consumer messaging app collapsed: BlackBerry (then RIM) dominated enterprise/mobile email and secure messaging in the early-to-mid 2000s with physical keyboards and its ecosystem. The iPhone (2007) and Android smartphones rapidly shifted the market to touchscreens, rich app ecosystems, consumer media, and developer support. BlackBerry was slow to adapt (late/imperfect touch devices, BlackBerry 10 OS struggles, internal strategy disagreements, over-reliance on keyboard/enterprise strengths). Market share collapsed; by the mid-2010s it was negligible. Hardware was effectively exited by ~2016 (later limited licensing attempts failed to revive it). Classic devices lost network support in 2022 as the company fully pivoted to software. 
Consumer BBM (BlackBerry Messenger) was once highly popular for secure/group messaging. It was licensed out (to Emtek in Indonesia around 2016); the consumer version shut down in 2019 because users migrated to WhatsApp, iMessage, etc., and new-user acquisition failed despite efforts. The enterprise-grade version (BBM Enterprise / secure messaging tools) continued and evolved into part of the Secure Communications portfolio. 
In short: the phone/messaging consumer era ended due to failure to compete in the post-iPhone smartphone platform shift. The surviving business is the software pivot (QNX + secure gov/enterprise tools) that has driven the 2026 re-rating. The monthly chart’s demand-floor base and recent structural break align with that fundamental shift, while the current pullback is a classic post-rally test .
#blackberry
Trade active
QNX and secure communication will set up bullish rally soon
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.