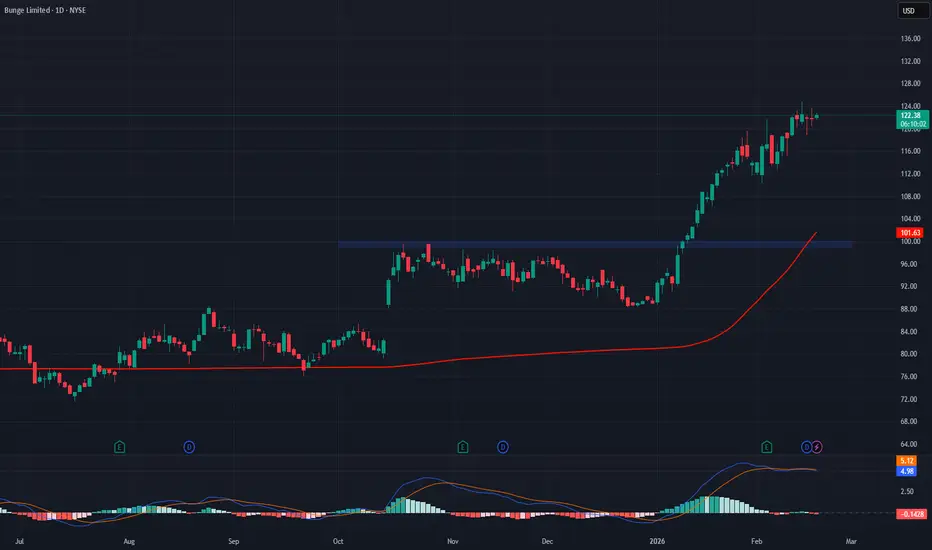
Company Overview
Bunge BG is a global agribusiness leader spanning origination, crushing, merchandising/trading, and food ingredients—a direct play on global food demand, renewable fuels, and resilient supply chains.
Key Catalysts
Viterra Acquisition = Core Value Driver (2025): The deal materially expands Bunge’s origination footprint, processing capacity, and global logistics network. Integration is advancing with synergies ramping and better margin capture, reinforcing BG as a dominant global platform.
Exceptional Free Cash Flow Outlook: Street estimates call for ~$2.1B FCF in 2026 and ~$2.7B in 2027, powered by higher volumes, integration benefits, and cost discipline—supporting deleveraging, buybacks, dividends, and strategic flexibility.
Revenue Momentum + Multi-Year Demand: Q4’25 revenue +75% YoY to $23.76B, driven by soybean crush strength, grain merchandising, and expanded reach. Tailwinds from renewable diesel feedstocks and specialty ingredients add durable growth drivers.
Why It Matters
✅ Global scale across crops and geographies reduces single-cycle risk
✅ Logistics + origination integration improves throughput and margins
✅ Strong FCF enables consistent shareholder returns
Investment View
Bullish above: $99–$100
Upside target: $145–$150 — backed by Viterra integration upside, strong crush economics, and FCF compounding.
Bunge
BG is a global agribusiness leader spanning origination, crushing, merchandising/trading, and food ingredients—a direct play on global food demand, renewable fuels, and resilient supply chains.Key Catalysts
Viterra Acquisition = Core Value Driver (2025): The deal materially expands Bunge’s origination footprint, processing capacity, and global logistics network. Integration is advancing with synergies ramping and better margin capture, reinforcing BG as a dominant global platform.
Exceptional Free Cash Flow Outlook: Street estimates call for ~$2.1B FCF in 2026 and ~$2.7B in 2027, powered by higher volumes, integration benefits, and cost discipline—supporting deleveraging, buybacks, dividends, and strategic flexibility.
Revenue Momentum + Multi-Year Demand: Q4’25 revenue +75% YoY to $23.76B, driven by soybean crush strength, grain merchandising, and expanded reach. Tailwinds from renewable diesel feedstocks and specialty ingredients add durable growth drivers.
Why It Matters
✅ Global scale across crops and geographies reduces single-cycle risk
✅ Logistics + origination integration improves throughput and margins
✅ Strong FCF enables consistent shareholder returns
Investment View
Bullish above: $99–$100
Upside target: $145–$150 — backed by Viterra integration upside, strong crush economics, and FCF compounding.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.