Company Overview
Peabody BTU is a leading U.S./global coal producer with exposure to thermal (PRB) and metallurgical markets—positioned for durable cash generation and diversification.
Key Drivers
PRB Tightness into 2026: Delayed plant retirements keep domestic demand firm; a large share sold forward at attractive prices supports near-term cash-flow visibility.
Met Coal Mix Shift: Rising exposure to higher-margin metallurgical coal adds upside tied to global steel demand and export pricing.
Operational Discipline: Strong balance sheet and cost control enhance cycle resilience and shareholder return potential.
Investment Outlook
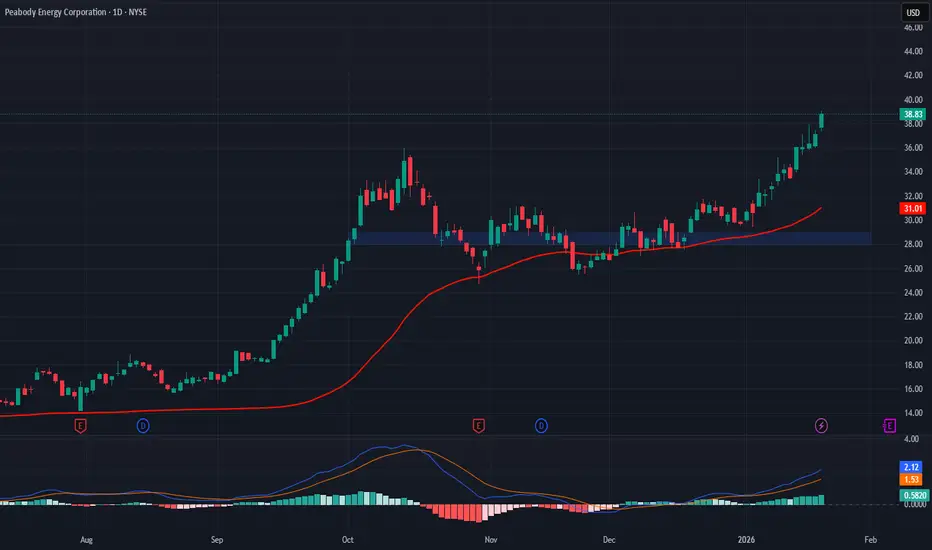
Bullish above: $28–$29
Target: $46–$48 — underpinned by locked-in PRB pricing, met coal optionality, and lean operations.
📌 BTU — Cash visibility now, optionality later via met coal.
Peabody
BTU is a leading U.S./global coal producer with exposure to thermal (PRB) and metallurgical markets—positioned for durable cash generation and diversification.Key Drivers
PRB Tightness into 2026: Delayed plant retirements keep domestic demand firm; a large share sold forward at attractive prices supports near-term cash-flow visibility.
Met Coal Mix Shift: Rising exposure to higher-margin metallurgical coal adds upside tied to global steel demand and export pricing.
Operational Discipline: Strong balance sheet and cost control enhance cycle resilience and shareholder return potential.
Investment Outlook
Bullish above: $28–$29
Target: $46–$48 — underpinned by locked-in PRB pricing, met coal optionality, and lean operations.
📌 BTU — Cash visibility now, optionality later via met coal.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.