
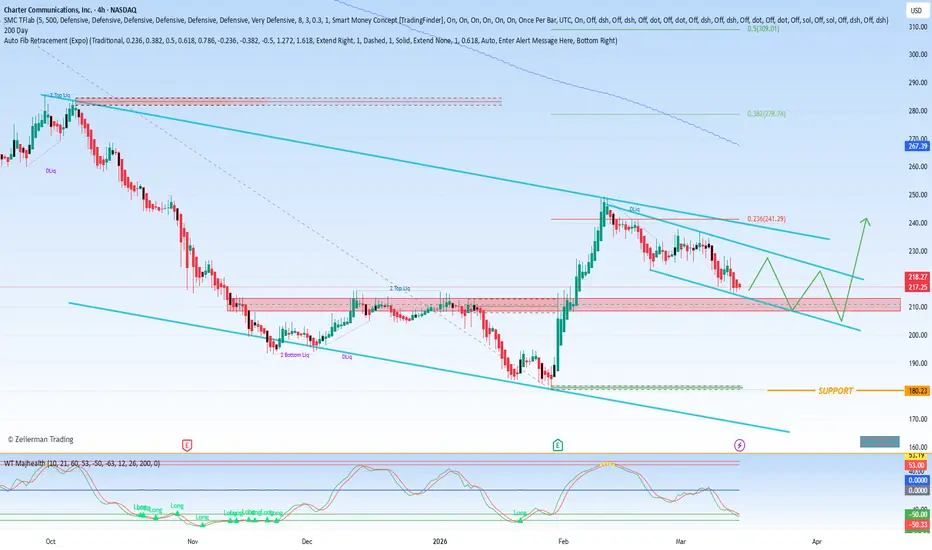
A compelling investment thesis for Charter Communications (CHTR) has recently surfaced within the value investing community, challenging the prevailing negative sentiment surrounding the stock. As of February 13th, CHTR shares were trading at $239.09, presenting what appears to be a deeply undervalued opportunity based on several key metrics and strategic shifts. According to data from Yahoo Finance, the stock's trailing price-to-earnings (P/E) ratio stands at a modest 6.60, while its forward P/E is even lower at 5.50. However, the core of this bullish argument extends beyond conventional earnings multiples to focus on a significant upcoming transformation in the company's capital expenditure cycle and its shareholder return strategy.
Navigating Near-Term Headwinds
It is undeniable that Charter has faced its share of recent challenges. The company has been grappling with modest but concerning losses in its broadband subscriber base, a trend that has fueled a broader narrative that the cable giant is losing its competitive edge and long-term relevancy in a rapidly evolving digital landscape. Despite these headwinds, there are early signs of operational resilience. Charter has managed to slightly outperform subdued market expectations by reporting broadband subscriber losses that were less severe than anticipated. Furthermore, the company has demonstrated strength in its mobile virtual network operator (MVNO) business by consistently adding mobile subscribers. This dual dynamic—stabilizing the core broadband business while gaining traction in mobile—suggests that the worst of the subscriber decline may be over, potentially paving the way for modest, single-digit growth in the latter half of the year.
The Capex Cliff: A Catalyst for Explosive Free Cash Flow
While the current earnings multiple appears low, the most significant and transformative aspect of the investment thesis lies in the company's impending "capex cliff." Over the past several years, Charter has been in the midst of a monumental, multi-billion dollar initiative to overhaul and upgrade its network infrastructure. This capital-intensive period peaked in 2025, with the company investing a staggering $12 billion in capital expenditures. However, this spending is not set to continue indefinitely.
Management has provided a clear roadmap indicating that this elevated level of investment will steadily decline over the next four years. The projections show capital expenditures decreasing from approximately $11 billion in 2026 to around $7 billion by 2028 and beyond. This is the critical inflection point. The dramatic reduction in capital spending does not imply a decline in business health or profitability; rather, it signifies the completion of the heavy-lifting phase of network modernization. As these capital outlays recede, a significant portion of the company's operational cash flow will be liberated, leading to a dramatic and predictable surge in free cash flow (FCF). This isn't a function of speculative revenue growth, but a near-mathematical certainty resulting from reduced spending requirements.
A Blueprint for Shareholder Value Creation
The most exciting part of the thesis is what management intends to do with this burgeoning free cash flow. Leadership has explicitly stated that a substantial portion of this capital will be channeled back to shareholders through aggressive share repurchases. Given the current depressed share price and the projected cash flows, the math behind this strategy is powerful.
The analysis suggests that if Charter executes on its buyback plan at current valuations, the company could retire nearly 50% of its total outstanding shares over the next five years. This aggressive reduction in share count would have a compounding effect on per-share metrics, magnifying the value for remaining investors.
The projected financial trajectory underscores this point. By 2026, as the capex reduction begins to take hold, Charter is expected to generate free cash flow per share of approximately $36. This would translate to a massive free cash flow yield of roughly 14% based on the current stock price. As the capex decline accelerates towards 2029, the potential is even more striking. By the end of the decade, the model projects free cash flow per share could skyrocket to $121, implying a staggering 56% free cash flow yield.
The Investment Conclusion: A Unique Risk/Reward Profile
The investment thesis for Charter Communications is not predicated on a sudden acceleration of top-line revenue or a miraculous re-conquest of lost market share. Instead, it is built on a structural de-risking of the business model and a disciplined, shareholder-friendly capital allocation strategy. The combination of a low initial valuation, a visible and imminent acceleration of free cash flow, and a commitment to aggressive buybacks creates a unique setup for long-term investors. As the market begins to recognize the sustainability of the cash flows and the decreasing capital intensity of the business, there is significant potential for a valuation rerating. For investors with a multi-year time horizon, Charter Communications presents an exceptional opportunity where the margin of safety is defined by tangible financial engineering and the potential for outsized returns is driven by a coming transformation in capital allocation.
Navigating Near-Term Headwinds
It is undeniable that Charter has faced its share of recent challenges. The company has been grappling with modest but concerning losses in its broadband subscriber base, a trend that has fueled a broader narrative that the cable giant is losing its competitive edge and long-term relevancy in a rapidly evolving digital landscape. Despite these headwinds, there are early signs of operational resilience. Charter has managed to slightly outperform subdued market expectations by reporting broadband subscriber losses that were less severe than anticipated. Furthermore, the company has demonstrated strength in its mobile virtual network operator (MVNO) business by consistently adding mobile subscribers. This dual dynamic—stabilizing the core broadband business while gaining traction in mobile—suggests that the worst of the subscriber decline may be over, potentially paving the way for modest, single-digit growth in the latter half of the year.
The Capex Cliff: A Catalyst for Explosive Free Cash Flow
While the current earnings multiple appears low, the most significant and transformative aspect of the investment thesis lies in the company's impending "capex cliff." Over the past several years, Charter has been in the midst of a monumental, multi-billion dollar initiative to overhaul and upgrade its network infrastructure. This capital-intensive period peaked in 2025, with the company investing a staggering $12 billion in capital expenditures. However, this spending is not set to continue indefinitely.
Management has provided a clear roadmap indicating that this elevated level of investment will steadily decline over the next four years. The projections show capital expenditures decreasing from approximately $11 billion in 2026 to around $7 billion by 2028 and beyond. This is the critical inflection point. The dramatic reduction in capital spending does not imply a decline in business health or profitability; rather, it signifies the completion of the heavy-lifting phase of network modernization. As these capital outlays recede, a significant portion of the company's operational cash flow will be liberated, leading to a dramatic and predictable surge in free cash flow (FCF). This isn't a function of speculative revenue growth, but a near-mathematical certainty resulting from reduced spending requirements.
A Blueprint for Shareholder Value Creation
The most exciting part of the thesis is what management intends to do with this burgeoning free cash flow. Leadership has explicitly stated that a substantial portion of this capital will be channeled back to shareholders through aggressive share repurchases. Given the current depressed share price and the projected cash flows, the math behind this strategy is powerful.
The analysis suggests that if Charter executes on its buyback plan at current valuations, the company could retire nearly 50% of its total outstanding shares over the next five years. This aggressive reduction in share count would have a compounding effect on per-share metrics, magnifying the value for remaining investors.
The projected financial trajectory underscores this point. By 2026, as the capex reduction begins to take hold, Charter is expected to generate free cash flow per share of approximately $36. This would translate to a massive free cash flow yield of roughly 14% based on the current stock price. As the capex decline accelerates towards 2029, the potential is even more striking. By the end of the decade, the model projects free cash flow per share could skyrocket to $121, implying a staggering 56% free cash flow yield.
The Investment Conclusion: A Unique Risk/Reward Profile
The investment thesis for Charter Communications is not predicated on a sudden acceleration of top-line revenue or a miraculous re-conquest of lost market share. Instead, it is built on a structural de-risking of the business model and a disciplined, shareholder-friendly capital allocation strategy. The combination of a low initial valuation, a visible and imminent acceleration of free cash flow, and a commitment to aggressive buybacks creates a unique setup for long-term investors. As the market begins to recognize the sustainability of the cash flows and the decreasing capital intensity of the business, there is significant potential for a valuation rerating. For investors with a multi-year time horizon, Charter Communications presents an exceptional opportunity where the margin of safety is defined by tangible financial engineering and the potential for outsized returns is driven by a coming transformation in capital allocation.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.