
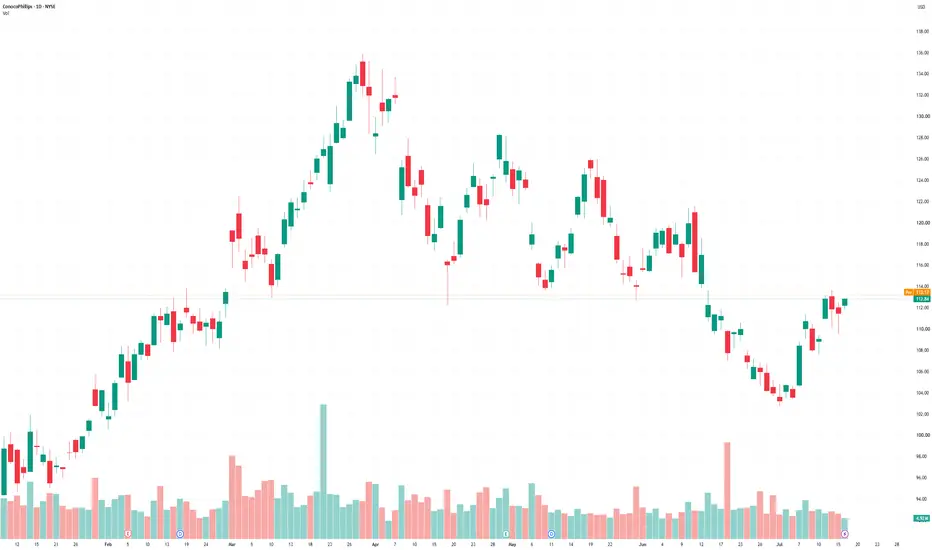
ConocoPhillips: Strong Fundamentals and Favorable Energy Market Conditions
Ticker: NYSE
Price at the time of analysis (July 7, 2026): $103.58
Current price: $111.46
Target price: $117.80
Stop-loss: $96.40
Recommendation: Buy
Risk level: Medium
Investment Thesis
Rising seasonal demand for oil and natural gas, combined with ConocoPhillips’ strong fundamentals and the completion of major investment projects, makes COP shares attractive over both the short and long term.
The key factors supporting this investment idea are:
Company Overview
ConocoPhillips is one of the largest oil and gas producers in the United States. In addition to its core exploration and production operations, the company participates in several liquefied natural gas projects.
The company’s business is primarily concentrated in the United States, which accounts for approximately 80% of its revenue. Founded in 1875, ConocoPhillips is headquartered in Houston, Texas.
In our view, COP shares offer attractive upside potential over the next two months, supported by several fundamental and market-related catalysts.
Rising Demand and Prices for Oil and Natural Gas
The U.S. Department of Energy forecasts an 11.0% month-over-month increase in natural gas demand in July. Seasonal demand for natural gas in the United States typically peaks between late July and early August.
Forecasts also point to a significant slowdown in natural gas storage injections over the coming weeks. Stronger demand and slower inventory growth could support higher U.S. natural gas prices.
WTI crude oil prices have declined by 21.5% since the beginning of June, falling below $70 per barrel amid optimism surrounding negotiations between the United States and Iran, as well as expectations of an oversupplied oil market.
We believe this optimism may be excessive. Attacks on tankers in the Strait of Hormuz are continuing, while disagreements over key issues remain unresolved. In addition, U.S. crude oil and petroleum product inventories have fallen to their lowest level since 2004.
A favorable technical setup, combined with the seasonal increase in summer oil demand, could also support a recovery in oil prices and a positive move in COP shares.
Completion of Major Investment Projects
The completion of the North Field East and North Field South LNG projects in Qatar, as well as the Port Arthur LNG project in the United States, could provide a meaningful boost to ConocoPhillips’ financial performance.
Together with the company’s cost-reduction program, these projects are expected by management to increase annual free cash flow by approximately $1 billion in each of 2026, 2027, and 2028.
In 2029, free cash flow could rise by an additional $4 billion year over year following the launch of the large-scale Willow project in Alaska.
The Willow project is expected to reach peak production of approximately 180,000 barrels per day and has estimated proven reserves of around 600 million barrels. It is considered a strategically important project for ConocoPhillips, with planned capital expenditures of approximately $7 billion.
Conclusion:
We maintain a Buy rating on ConocoPhillips shares.
Our target price of $117.80 represents approximately 14% upside from the price at the time of analysis. A stop-loss at $96.40 may help limit downside risk.
Seasonally stronger energy demand, low U.S. inventories, potential support for oil and natural gas prices, and expected free-cash-flow growth from major investment projects create a favorable risk-reward profile for COP share.
Ticker: NYSE
Price at the time of analysis (July 7, 2026): $103.58
Current price: $111.46
Target price: $117.80
Stop-loss: $96.40
Recommendation: Buy
Risk level: Medium
Investment Thesis
Rising seasonal demand for oil and natural gas, combined with ConocoPhillips’ strong fundamentals and the completion of major investment projects, makes COP shares attractive over both the short and long term.
The key factors supporting this investment idea are:
- Rising demand and prices for oil and natural gas
- The completion of major investment projects
- Expected growth in free cash flow
- A favorable technical setup
Company Overview
ConocoPhillips is one of the largest oil and gas producers in the United States. In addition to its core exploration and production operations, the company participates in several liquefied natural gas projects.
The company’s business is primarily concentrated in the United States, which accounts for approximately 80% of its revenue. Founded in 1875, ConocoPhillips is headquartered in Houston, Texas.
In our view, COP shares offer attractive upside potential over the next two months, supported by several fundamental and market-related catalysts.
Rising Demand and Prices for Oil and Natural Gas
The U.S. Department of Energy forecasts an 11.0% month-over-month increase in natural gas demand in July. Seasonal demand for natural gas in the United States typically peaks between late July and early August.
Forecasts also point to a significant slowdown in natural gas storage injections over the coming weeks. Stronger demand and slower inventory growth could support higher U.S. natural gas prices.
WTI crude oil prices have declined by 21.5% since the beginning of June, falling below $70 per barrel amid optimism surrounding negotiations between the United States and Iran, as well as expectations of an oversupplied oil market.
We believe this optimism may be excessive. Attacks on tankers in the Strait of Hormuz are continuing, while disagreements over key issues remain unresolved. In addition, U.S. crude oil and petroleum product inventories have fallen to their lowest level since 2004.
A favorable technical setup, combined with the seasonal increase in summer oil demand, could also support a recovery in oil prices and a positive move in COP shares.
Completion of Major Investment Projects
The completion of the North Field East and North Field South LNG projects in Qatar, as well as the Port Arthur LNG project in the United States, could provide a meaningful boost to ConocoPhillips’ financial performance.
Together with the company’s cost-reduction program, these projects are expected by management to increase annual free cash flow by approximately $1 billion in each of 2026, 2027, and 2028.
In 2029, free cash flow could rise by an additional $4 billion year over year following the launch of the large-scale Willow project in Alaska.
The Willow project is expected to reach peak production of approximately 180,000 barrels per day and has estimated proven reserves of around 600 million barrels. It is considered a strategically important project for ConocoPhillips, with planned capital expenditures of approximately $7 billion.
Conclusion:
We maintain a Buy rating on ConocoPhillips shares.
Our target price of $117.80 represents approximately 14% upside from the price at the time of analysis. A stop-loss at $96.40 may help limit downside risk.
Seasonally stronger energy demand, low U.S. inventories, potential support for oil and natural gas prices, and expected free-cash-flow growth from major investment projects create a favorable risk-reward profile for COP share.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.