
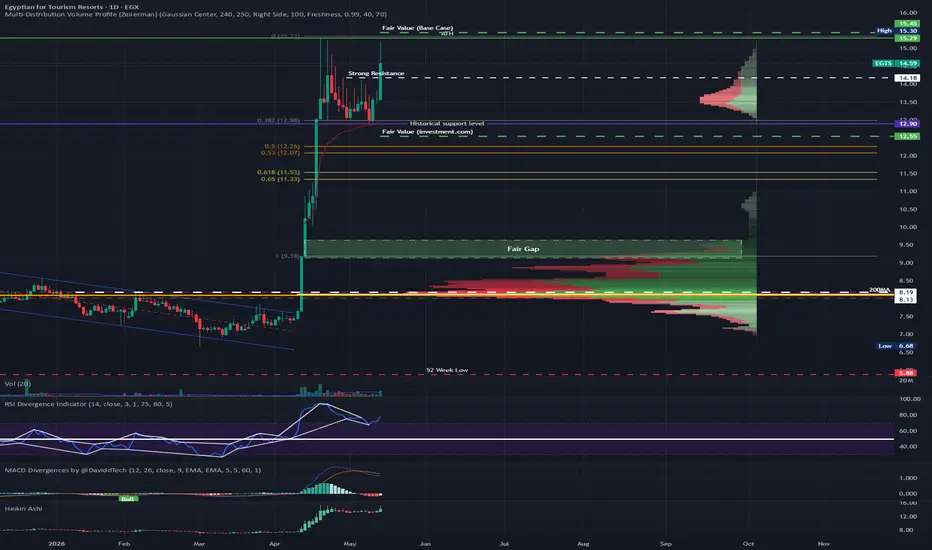
The Reality: I see a "Recovery Play" that is currently trading at its maximum fundamental temperature. 🌡️
After reporting a massive turnaround in late 2025 (EGP 1.05B net profit), the stock has become a momentum favorite.
However, with the price at 15.10 EGP, you are paying for every bit of that recovery—and then some. 🏛️✨
🔢 Relative Valuation (Earnings Model):TTM EPS: 0.96 EGP 💵
Growth Multiplier: 14x P/E applied (above the 13x peer average due to a strong 31% growth rate and tourism recovery) 📈🌊
Base Valuation: 13.44 EGP ($0.96 \times 14$) 🏗️💎
The "Land Bank" Premium: I am adding a 15% premium (+2.01 EGP) for the immense strategic value of the Sahl Hasheesh waterfront assets, which aren't fully captured in the current earnings. 🏖️🏨
Total Fair Value: 15.45 EGP 🎯
The Technical Ceiling: I find the stock is hitting a wall.
The all-time high of 15.30 EGP (set just weeks ago in April 2026) is acting as a heavy psychological barrier. 🧱🏹
With a trailing P/E of ~14.1x, the "value" window has officially closed, making this a pure play on future land sales and hotel occupancy. 📉🌬️
🚨 Current Status: Aggressive Hold
EGTS is trading at the very top end of its fundamental range (Fair Value: 15.45 EGP). 📈
If you like my insights, follow and boost! 🙌💙🚀
🎁 $15 TradingView Discount:
🔗 tradingview.com/pricing/?share_your_love=mnmabroukw36ix ✨💸🤑

Related publications
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Related publications
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.