
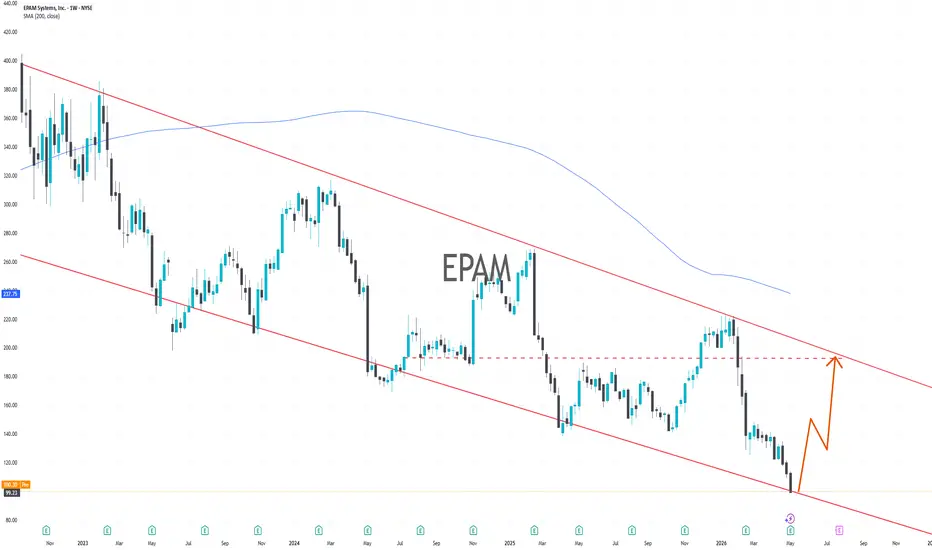
$NYSE: EPAM Systems (EPAM) just delivered a quarter that perfectly explains the current market environment:
Fundamentals were actually solid…
But guidance and macro fears crushed sentiment.
The company reported:
7.6% YoY revenue growth
Nearly 19% EPS growth
Improving margins
AI revenue above $125M in Q1 alone
At the same time, management lowered full-year growth expectations because of:
Slower enterprise decision-making
Weaker North American demand
Broader macro uncertainty
That combination created the selloff.
Why The AI Story Matters
This is no longer just a traditional IT outsourcing company.
EPAM is aggressively repositioning itself into:
Enterprise AI integration
AI-native engineering
Transformation infrastructure
The partnership with Anthropic is a major signal here.
Management is targeting:
10,000 Claude-certified architects
$600M in AI revenue this year
That is not the profile of a dying business.
Balance Sheet Strength
The market is acting as if EPAM is in structural trouble.
But financially:
Over $1B cash
No long-term debt
Aggressive buybacks continue
Management repurchased hundreds of millions in stock because they clearly believe valuation became disconnected from fundamentals.
Technical Picture
Technically, the chart is now testing the lower boundary of a massive multi-year descending channel.
This area matters because:
Previous major bottoms formed near this structure
Downside momentum is becoming extended
The sentiment is extremely bearish
At the same time, the stock remains deeply below the 200-week moving average and long-term downtrend resistance.
So the thesis here is not “trend reversal confirmed.”
The thesis is:
risk/reward is becoming asymmetric near major support.
The Setup
If the lower channel support holds:
→ EPAM could stage a strong mean reversion move back toward the upper channel resistance.
That would align with:
Improving AI narrative
Stabilization in enterprise spending
Broader software sector recovery
But if support breaks cleanly, the bearish structure remains fully intact.
Bottom Line
The market currently sees EPAM as:
A slowing IT services company is exposed to macro weakness.
But underneath the surface:
AI revenue is accelerating fast
Margins remain healthy
The balance sheet is extremely strong
The company is positioning for the next enterprise AI cycle
Now the chart is approaching the kind of level where long-term opportunities often begin forming — not after optimism returns, but while fear still dominates pricing.

Related publications
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Related publications
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.