
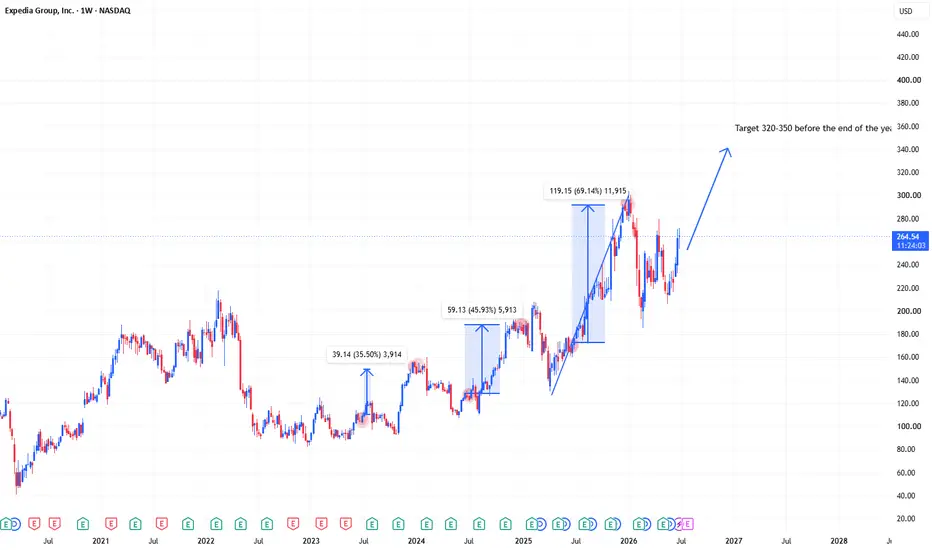
Expedia Group is one of the largest online travel and travel technology companies, operating brands across hotels, flights, vacation rentals, rental cars, cruises, B2B travel solutions, and advertising. The company owns major travel platforms including Expedia, Hotels.com, Vrbo, Travelocity, Trivago, Hotwire, Orbitz, and others.
From a fundamental perspective, Expedia has recently benefited from three important drivers:
1. Travel demand remains resilient
Even with higher interest rates, consumers continue to spend on travel. The travel sector remains one of the strongest post-pandemic consumer categories, with demand supported by hotel bookings, international travel, vacation rentals, and corporate partnerships.
2. Positive summer and Christmas seasonality
Expedia typically benefits from two major seasonal periods: summer holidays and Christmas travel. These periods can bring higher booking volumes, stronger hotel pricing, increased vacation rental demand, and better operating leverage.
According to the analysis, Expedia has shown strong seasonal performance in recent years:
2023: +30% seasonal growth
2024: +45% seasonal growth
2025: +65% seasonal growth
This suggests that seasonal travel demand has been an important catalyst for the stock.
3. Strong earnings beat
The biggest recent catalyst was Expedia’s strong Q1 2026 earnings performance. The company reported:
Gross bookings: +13% YoY
Revenue: +15% YoY
B2B bookings: +22% YoY
Adjusted EBITDA: +83% YoY
This shows that Expedia is not only growing, but also improving profitability and margins.
Bullish Scenario
If travel demand remains strong during the summer period and Expedia continues to deliver solid earnings, the stock could continue attracting buyers.
The bullish case is supported by:
Strong seasonal demand
Resilient consumer travel spending
Revenue and booking growth
Margin expansion
Positive analyst expectations
In this scenario, Expedia could continue moving higher, especially if investors keep pricing in strong summer and winter travel demand.
Risk Scenario
The main risk is valuation.
A good company is not always a good investment if the entry price is too high. The PDF highlights that in 2024, around 630 million shares traded, with only 15% trading below estimated fair value. This means a large part of market activity may have happened at higher valuation levels.
If future growth does not justify the premium, the stock could correct even if the business remains healthy.
My View
Expedia has a strong fundamental story: travel demand is resilient, seasonality is positive, and earnings have improved significantly.
However, the key is not only whether Expedia is a good company. The key is the price investors are paying.
For me, EXPE remains interesting, but only if the market gives a reasonable entry or confirms that earnings growth can continue supporting the current valuation.
Conclusion
Expedia can benefit from summer and Christmas travel demand, but investors should not ignore valuation risk.
Strong business momentum = bullish factor.
Overpaying for the stock = main risk.
Educational analysis only. Not financial advice.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.