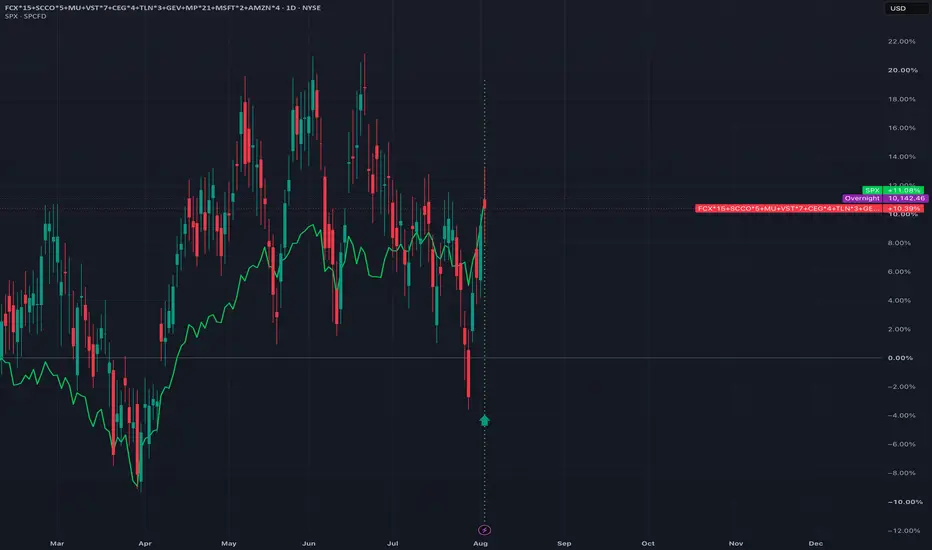
I run a thematic long book built on one macro premise: physical scarcity is repricing faster than equities acknowledge. Four engines, ten positions, all catalyst-dated. Sharing the full logic and my actual allocation.
ENGINE 1 — COPPER: THE CLEANEST SCARCITY TRADE ( FCX x15,
 SCCO x5)
LME copper cancelled warrants (metal already earmarked for withdrawal, so not really available) hit 62.4% of total stock — versus 4-18% for every other base metal. Live stock is down 71.8% from the April peak. Chile keeps losing supply (Caserones offline until mid/late August, Antofagasta H1 output -9.5%), and Morgan Stanley now forecasts a 600,000-tonne refined deficit for 2026 — the largest in over 20 years. Deficit estimates have widened three times in a row: 150kt → 520kt → 600kt. Every indicator points one direction.
ENGINE 2 — POWER SCARCITY ( VST x7,
 CEG x4,
 TLN x3,
 GEV x1)
PJM (the grid operator for 13 US states / 65M people) formally came up 6.8 GW short of its reliability target; a backstop auction runs Sept 30–Oct 21 — a dated catalyst for generators. Datacenters drove 38% ($6.3B) of the $16.4B capacity auction cost. Meanwhile ~40% of new US datacenter capacity is projected to go off-grid by 2030 (Google discloses interconnection delays up to 12 years), which is the GEV leg: someone has to build those gas turbines. Europe just joined the theme — Hungary's Paks nuclear plant dropped to ~25% output on record-low Danube cooling water.
ENGINE 3 — THE MEMORY BIFURCATION ( MU x1,
 MSFT x2,
 AMZN x4)
The AI-chip complex lost over $1 trillion in market cap in the week of July 28; MU trades ~37% below its June high. Yet the physical market tightened in the same week: Micron guides next quarter to $50B revenue at ~86% gross margin, HBM (high-bandwidth memory used in AI accelerators) is fully booked through 2027, Samsung guides the shortage through 2028, and Q3 DRAM contract prices are forecast +13-18%. Price crashed; product is sold out. I'm buying the gap, sized small because a third China-capacity headline (CXMT) can extend the drawdown. MSFT and AMZN are the demand underwrite — both held/raised capex (~$175B and $200B for 2026) and were rewarded for it, unlike GOOGL/META.
ENGINE 4 — RARE EARTHS ( MP x21)
China shipped ZERO gallium/dysprosium/terbium/yttrium to Japan in June — a full-month embargo posture against a G7 economy. NdPr alloy is +21.4% in a month. Two hard dates ahead: Nov 10 and Nov 27, when China's export-control suspensions expire. MP is the ex-China supply answer, and my largest share-count position on purpose.
CATALYST CALENDAR
- Aug 19: 50% US tariffs on Canadian autos/alcohol/dairy take effect (first Section 338 use since 1949)
- Aug 26: NVDA earnings — the referendum on the whole AI-chip crash
- Sept 30–Oct 21: PJM backstop auction (VST/CEG/TLN catalyst)
- Nov 10 / Nov 27: China export-control cliffs (MP catalyst)
RISKS
US-Iran de-escalation holding would ease the inflation/scarcity backdrop broadly; a CXMT headline can hit MU another leg down; power-scarcity politics (price caps, moratoriums) are a two-sided risk for generators; MP is priced for confrontation — a genuine China trade détente hurts it.
Positions disclosed above are my actual holdings. Not financial advice — do your own research.
ENGINE 1 — COPPER: THE CLEANEST SCARCITY TRADE (
FCX x15, SCCO x5)LME copper cancelled warrants (metal already earmarked for withdrawal, so not really available) hit 62.4% of total stock — versus 4-18% for every other base metal. Live stock is down 71.8% from the April peak. Chile keeps losing supply (Caserones offline until mid/late August, Antofagasta H1 output -9.5%), and Morgan Stanley now forecasts a 600,000-tonne refined deficit for 2026 — the largest in over 20 years. Deficit estimates have widened three times in a row: 150kt → 520kt → 600kt. Every indicator points one direction.
ENGINE 2 — POWER SCARCITY (
VST x7, CEG x4, TLN x3, GEV x1)PJM (the grid operator for 13 US states / 65M people) formally came up 6.8 GW short of its reliability target; a backstop auction runs Sept 30–Oct 21 — a dated catalyst for generators. Datacenters drove 38% ($6.3B) of the $16.4B capacity auction cost. Meanwhile ~40% of new US datacenter capacity is projected to go off-grid by 2030 (Google discloses interconnection delays up to 12 years), which is the GEV leg: someone has to build those gas turbines. Europe just joined the theme — Hungary's Paks nuclear plant dropped to ~25% output on record-low Danube cooling water.
ENGINE 3 — THE MEMORY BIFURCATION (
MU x1, MSFT x2, AMZN x4)The AI-chip complex lost over $1 trillion in market cap in the week of July 28; MU trades ~37% below its June high. Yet the physical market tightened in the same week: Micron guides next quarter to $50B revenue at ~86% gross margin, HBM (high-bandwidth memory used in AI accelerators) is fully booked through 2027, Samsung guides the shortage through 2028, and Q3 DRAM contract prices are forecast +13-18%. Price crashed; product is sold out. I'm buying the gap, sized small because a third China-capacity headline (CXMT) can extend the drawdown. MSFT and AMZN are the demand underwrite — both held/raised capex (~$175B and $200B for 2026) and were rewarded for it, unlike GOOGL/META.
ENGINE 4 — RARE EARTHS (
MP x21)China shipped ZERO gallium/dysprosium/terbium/yttrium to Japan in June — a full-month embargo posture against a G7 economy. NdPr alloy is +21.4% in a month. Two hard dates ahead: Nov 10 and Nov 27, when China's export-control suspensions expire. MP is the ex-China supply answer, and my largest share-count position on purpose.
CATALYST CALENDAR
- Aug 19: 50% US tariffs on Canadian autos/alcohol/dairy take effect (first Section 338 use since 1949)
- Aug 26: NVDA earnings — the referendum on the whole AI-chip crash
- Sept 30–Oct 21: PJM backstop auction (VST/CEG/TLN catalyst)
- Nov 10 / Nov 27: China export-control cliffs (MP catalyst)
RISKS
US-Iran de-escalation holding would ease the inflation/scarcity backdrop broadly; a CXMT headline can hit MU another leg down; power-scarcity politics (price caps, moratoriums) are a two-sided risk for generators; MP is priced for confrontation — a genuine China trade détente hurts it.
Positions disclosed above are my actual holdings. Not financial advice — do your own research.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.