
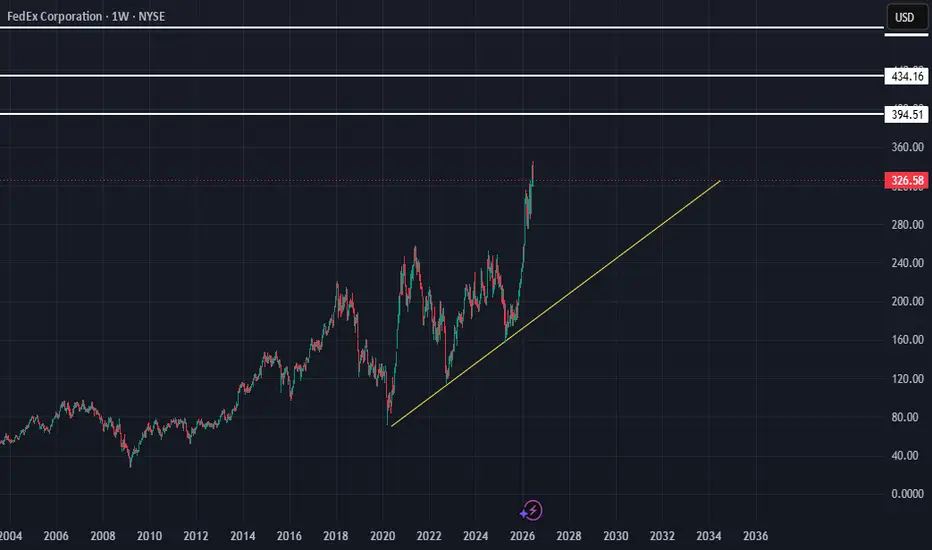
FedEx is transforming, from a low-margin shipping company, into a more efficient, cash-generative logistics platform.
PE 17.5
Margin expansion: The DRIVE and Network 2.0 initiatives, are removing billions of dollars of costs from the business, improving operating leverage and profitability.
Management has already achieved, major cost reductions and continues to target additional savings.
Freight spin-off unlocks value: The planned, separation of FedEx Freight, could eliminate the conglomerate discount, allowing investors to value the parcel and LTL businesses independently.
Improving core business: Express and parcel volumes, pricing, and yields have been strengthening, driving multiple quarters of margin expansion in the core network.
Strong free cash flow: Lower capital expenditures and ongoing efficiency gains.Boosting cash generation, supporting buybacks, dividends, and debt reduction.
Reasonable valuation: Despite operational improvements, FedEx still trades below many transportation peers on earnings and cash flow metrics, leaving room for multiple expansion if execution continues.
https://www.tradingview.com/x/kQcaKQPH/

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.