
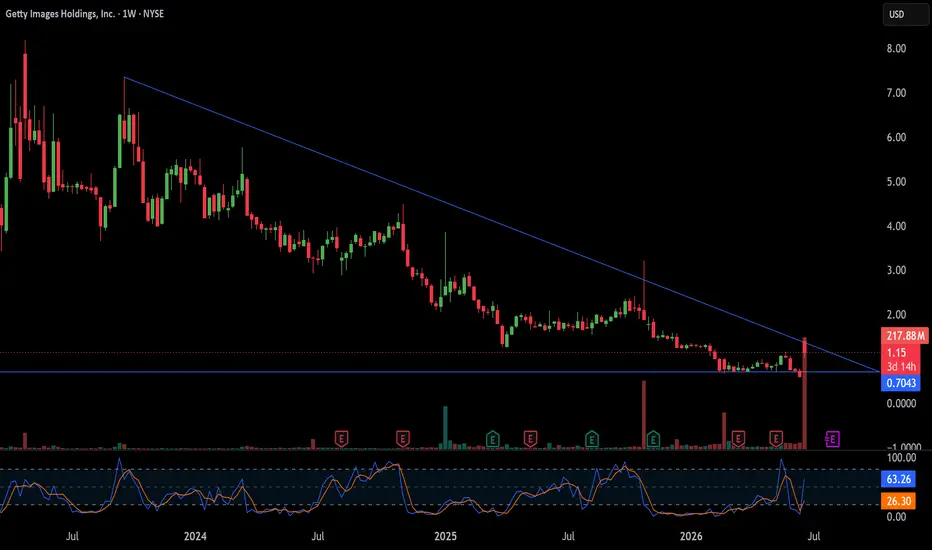
Getty Images (NYSE: GETY) announced a multi-year display partnership with OpenAI on June 21, and the stock did the rest. Shares spiked as much as 145% intraday before closing roughly 90% higher near $1.15. The detail that matters is what the deal is: Getty's licensed images will appear in ChatGPT's search and discovery results with attribution, and the agreement explicitly excludes using those images to train OpenAI's models. Financial terms were not disclosed.
The real significance is narrative rather than near-term cash. Getty has flipped from litigation, having sued Stability AI, to positioning itself as the clean, licensed, attributed visual layer for AI-native search. That reframes the company's story from AI as an existential substitution threat to AI as a new distribution channel for rights-cleared content. For a business the market had largely written off, that shift in narrative is the genuine prize, and it is why a sleepy content name re-rated overnight.
The fundamentals demand caution, because the move came off a distressed base. GETY had been a sub-$1 stock trading near its 52-week low of $0.58, and it received an NYSE notice in March for failing the minimum-price requirement. First-quarter revenue of $226.6 million missed estimates, creative revenue fell 4.5%, and full-year guidance was left unchanged at $948 million to $988 million. The company carries negative margins, heavy leverage, and a $3.7 billion Shutterstock acquisition still awaiting approval. With no disclosed economics on the OpenAI deal, the 145% spike fading to a 90% close looks as much like a low-float squeeze as a true re-rating.
The honest read is that the deal is strategically real but financially unproven. Getty has a credible claim to be the licensed, rights-cleared content layer for AI search, and the pivot from suing AI firms to supplying them is smart. But "AI kingmaker" overstates a display agreement with undisclosed terms on a penny stock with shrinking revenue. Treat GETY as a high-risk, event-driven turnaround, not a proven AI-data winner. The swing factor is whether the OpenAI distribution, and the scale a Shutterstock deal would add, converts into disclosed, recurring revenue. Until terms and dollars appear, this is a narrative bet, not an earnings one.
The real significance is narrative rather than near-term cash. Getty has flipped from litigation, having sued Stability AI, to positioning itself as the clean, licensed, attributed visual layer for AI-native search. That reframes the company's story from AI as an existential substitution threat to AI as a new distribution channel for rights-cleared content. For a business the market had largely written off, that shift in narrative is the genuine prize, and it is why a sleepy content name re-rated overnight.
The fundamentals demand caution, because the move came off a distressed base. GETY had been a sub-$1 stock trading near its 52-week low of $0.58, and it received an NYSE notice in March for failing the minimum-price requirement. First-quarter revenue of $226.6 million missed estimates, creative revenue fell 4.5%, and full-year guidance was left unchanged at $948 million to $988 million. The company carries negative margins, heavy leverage, and a $3.7 billion Shutterstock acquisition still awaiting approval. With no disclosed economics on the OpenAI deal, the 145% spike fading to a 90% close looks as much like a low-float squeeze as a true re-rating.
The honest read is that the deal is strategically real but financially unproven. Getty has a credible claim to be the licensed, rights-cleared content layer for AI search, and the pivot from suing AI firms to supplying them is smart. But "AI kingmaker" overstates a display agreement with undisclosed terms on a penny stock with shrinking revenue. Treat GETY as a high-risk, event-driven turnaround, not a proven AI-data winner. The swing factor is whether the OpenAI distribution, and the scale a Shutterstock deal would add, converts into disclosed, recurring revenue. Until terms and dollars appear, this is a narrative bet, not an earnings one.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.