
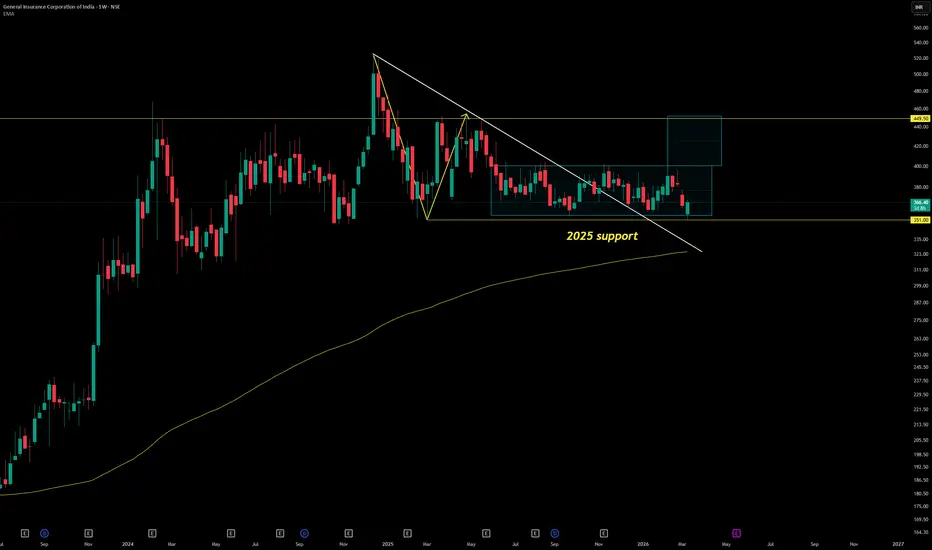
General Insurance Corporation of India (NSE: GICRE) is India’s leading reinsurance company, incorporated in 1972. It provides reinsurance support to direct insurers in India and abroad, covering fire, marine, motor, health, agriculture, aviation, and liability segments.
Promoter: Government of India (President of India acting through MoF) – 85.78% holding (Dec 2025)
FY22–FY26 Snapshot
Revenue Growth: CAGR ~9% over FY22–FY26, driven by reinsurance premium growth. → Neutral
Net Profit: FY26 PAT ~₹4,200 Cr, reflecting steady profitability. → Good
Operating Margin: Maintained ~18–20%, showing efficiency in underwriting. → Good
Equity Capital: Stable, no major dilution. → Good
Dividend Policy: Attractive, yield ~3.5% (FY26). → Good
Asset Building: Expansion of reinsurance portfolio across multiple sectors. → Good
Sales: FY26 revenue crossed ₹50,000 Cr, supported by premium growth. → Good
Expense: High claim ratios in health and agriculture segments. → Neutral
EPS: ~₹26.4 in FY26, reflecting consistent earnings. → Good
Institutional Interest & Ownership Trends
Largest Promoter: Government of India (MoF) – 85.78%
Largest FII: Vanguard Emerging Markets Fund – ~2.1%
Largest DII: LIC of India – ~3.8%
Strategic Moves & Innovations
Strengthening international reinsurance presence in Asia and Africa.
Focus on agriculture and health reinsurance.
Investment in digital underwriting and risk analytics.
Expansion into specialty lines (aviation, liability, cyber risk).
Cash Flow & Balance Sheet Strength
Strong operating cash flows supported by premium income.
Debt levels negligible, balance sheet backed by government.
Consistent profit growth supports dividend payouts.
Risk Factors
Exposure to high claim ratios in agriculture and health.
Dependence on global reinsurance cycles.
Competition from international reinsurers.
Regulatory risks in insurance pricing.
Investor Takeaway
General Insurance Corporation of India (GICRE) is a PSU reinsurance giant with strong promoter backing and attractive dividend yield. With most snapshot parameters rated Good, GICRE offers stability and consistent profitability. Investors should monitor claim ratios and global reinsurance cycles, but overall the outlook remains positive.

Sucrit.D.Patil
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Sucrit.D.Patil
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.