
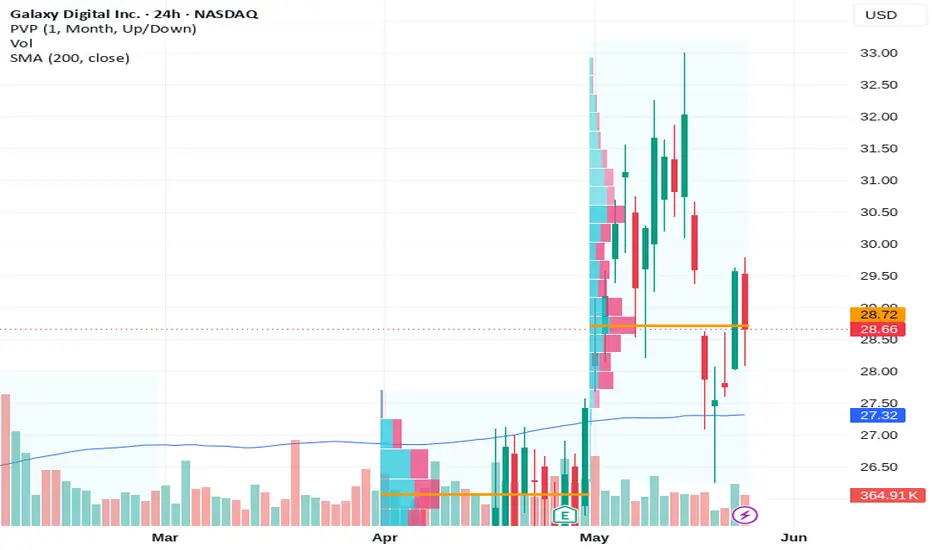
Executive Summary:
Margin of safety verdict: At roughly $30 per share, Galaxy Digital does not appear to offer a demonstrable margin of safety because normalized earnings and free cash flow cannot be estimated with confidence.
Galaxy Digital is often framed as a bridge between traditional finance and the digital asset economy. The firm runs a mix of businesses tied to crypto markets: trading and market making, asset management, advisory work similar to investment banking, venture investing, and infrastructure tied to mining and computing.
The long-term bull thesis is straightforward. If digital assets become a permanent part of global capital markets, Galaxy could evolve into a full financial platform for the ecosystem. In that scenario the company would collect fees from multiple layers of activity: trading, custody, ETFs, capital markets, and potentially high‑performance computing infrastructure.
The problem is that the current economics are difficult to analyze through a traditional value framework. Free cash flow has appeared deeply negative in recent years. Share dilution has increased. At the same time the company is committing large amounts of capital to infrastructure projects whose long-term returns remain uncertain. Much of the company’s profitability also continues to track crypto market cycles.
So the key question is not whether crypto markets grow over time. The question is whether Galaxy can consistently earn durable returns on capital through those cycles. Until that shows up in sustained cash flow, the stock behaves less like a compounding business and more like a macro proxy for crypto adoption.
One Stock, Dozens of Voices:
This is not one analyst's opinion. CrowdWisdom aggregated 2 independent sources for GLXY (1 live market intelligence feeds; 1 verified financial data checks (Yahoo Finance)) and synthesized the shared thesis: what do dozens of traders, investors, and researchers broadly agree on, where do they disagree, and what might the market be missing?
The evidence was then stress tested by setting opposing views against each other: a bull case, a bear case that challenges the consensus, and an examination of what expectations may already be reflected in the current price. All financial metrics were cross validated against live market data.
What follows highlights where opinions converge, where they split, and whether the stock provides any meaningful margin of safety at today’s price.
Business Quality and Moat Durability:
Galaxy Digital operates across several segments of the digital asset economy. These include institutional trading and market making, asset management products, advisory services resembling investment banking, venture investments in crypto startups, and infrastructure such as mining operations and large-scale data centers.
The broader strategy resembles a merchant bank built around digital assets.
In theory, several advantages could support that model.
One is institutional positioning. Large investors entering crypto markets typically require regulated counterparties with compliance systems comparable to traditional financial firms. Galaxy has tried to establish itself as one of the few crypto‑native platforms capable of serving hedge funds, asset managers, and sovereign capital.
Another advantage is platform integration. By running trading desks, venture portfolios, asset management products, and advisory services simultaneously, the company sits close to capital flows across the ecosystem. A firm advising blockchain startups, managing funds, and providing liquidity can potentially develop information advantages and cross‑selling opportunities.
There are also potential liquidity network effects. In financial markets, liquidity tends to attract more liquidity. Once an intermediary becomes a preferred counterparty, that position can reinforce itself.
Despite these theoretical advantages, the moat remains fragile.
Crypto trading infrastructure is highly competitive. Exchanges, market makers, and prime brokerage platforms all compete for institutional order flow. Switching costs are relatively low because sophisticated clients can route trades across multiple venues.
Large financial institutions are also moving into the space. If regulatory frameworks stabilize, global banks and exchanges could compete directly for institutional crypto services. At the same time, decentralized finance platforms aim to remove intermediaries entirely by enabling peer‑to‑peer financial transactions.
Moat durability verdict: narrow and uncertain. Any competitive advantage depends heavily on a market structure that is still evolving.
Return on Invested Capital (ROIC):
For long‑term investors, the central question is whether the company can generate attractive returns on invested capital over time.
Trading desks and venture portfolios can produce extremely high returns during strong markets. The difficulty is that those returns tend to be episodic. They often depend more on asset price appreciation than on durable competitive advantages.
Galaxy now appears to be expanding aggressively into capital‑intensive infrastructure.
The company has invested in large facilities designed for crypto mining and high‑performance computing workloads. These assets may eventually support artificial intelligence training or other compute‑heavy applications.
That shift changes the economics of the business.
Financial services businesses are usually capital light. Infrastructure businesses are not. Data centers require large upfront investment, long development timelines, and high utilization rates to earn acceptable returns.
If Galaxy commits substantial capital to infrastructure, incremental ROIC could compress meaningfully. Mature data center operators generally earn moderate returns relative to the occasionally extreme returns that trading businesses can produce during bull markets.
Utilization becomes the critical variable. If the company secures long‑term compute contracts with strong counterparties, returns could become stable though possibly lower. If utilization fluctuates alongside crypto cycles or speculative demand, returns could deteriorate.
Because verified ROIC figures are unavailable in the dataset, investors cannot confidently evaluate the trajectory. That lack of visibility alone is a significant analytical limitation.
Quality of Earnings:
One of the more concerning signals appears in the trend of free cash flow.
Recent financial analysis suggests free cash flow deteriorated sharply between 2022 and 2025, moving from roughly negative tens of millions to approximately negative $1.5 billion. Even allowing for estimation error, the scale of the change suggests substantial cash consumption.
Several forces may explain this.
First, infrastructure development requires heavy capital spending. Data center construction, power systems, and computing hardware must be deployed well before revenue is generated.
Second, the company holds digital asset investments and venture positions whose values fluctuate. Mark‑to‑market accounting can inflate earnings during bull markets while masking the volatility of underlying cash flow.
Third, trading operations can introduce large swings in working capital.
Another signal worth noting is dilution. The number of shares outstanding has risen sharply in recent years. For example, the share count increased significantly between 2024 and 2025, suggesting that equity issuance has been used to fund part of the expansion strategy.
For long‑term investors, accounting earnings matter less than free cash flow per share. If dilution continues while free cash flow remains negative, the economic value accruing to each shareholder may decline.
Capital Allocation Scorecard:
Capital allocation is ultimately the clearest test of management discipline.
Galaxy’s capital deployment in recent years reflects three major patterns.
Infrastructure expansion. The company has committed significant capital to data center and mining‑related assets. These investments could eventually produce stable contracted revenue, but the capital intensity and long payback periods increase execution risk.
Equity issuance. Rising share counts suggest the firm has relied on equity financing rather than internally generated cash. For existing shareholders this represents dilution of future earnings.
Limited shareholder returns. There is little evidence of meaningful buybacks or dividends. That is not unusual for a company pursuing aggressive growth, but it also means investors depend entirely on future capital appreciation.
Overall capital allocation grade: uncertain with rising capital intensity.
Customer and Revenue Concentration:
Verified data on customer concentration is not available. However the structure of institutional crypto markets implies potential concentration risk.
A large share of trading activity typically comes from a relatively small group of hedge funds, proprietary trading firms, and crypto‑native investment funds. These participants control a significant portion of liquidity.
If a handful of large clients represent a meaningful share of revenue, switching risk becomes material. Sophisticated trading firms can shift activity quickly to other exchanges or prime brokers if fees rise or liquidity weakens.
Meanwhile, large banks and exchanges are building their own institutional crypto infrastructure and may compete for the same client base.
Without clear disclosure on customer concentration, this remains an important unknown.
Management Alignment:
Galaxy Digital was founded by Mike Novogratz, a well‑known investor who became deeply involved in the cryptocurrency ecosystem early in its development.
Founder‑led companies can benefit from long‑term vision and a willingness to pursue ambitious strategies. Ultimately, though, alignment comes down to incentives and capital discipline.
Detailed insider ownership data is not available in the dataset, which limits the ability to assess alignment precisely. Investors should watch whether management focuses on creating value per share or continues issuing equity to fund expansion.
10-Year Durability Test:
Trying to forecast the structure of digital asset finance ten years from now is extremely difficult.
Several structural forces could reshape the industry.
Regulation is probably the largest variable. Governments around the world continue debating how digital assets should be governed. Strict regulation could constrain trading, lending, and token issuance, while favorable frameworks could accelerate institutional adoption.
Institutional participation is another key factor. The bullish case assumes digital assets become a permanent allocation in global portfolios, similar to commodities or emerging market equities. If adoption stalls, many intermediaries could struggle.
Competition from traditional finance is also likely to intensify. Global banks, exchanges, and fintech firms are investing heavily in crypto infrastructure and may eventually dominate regulated markets.
Technological disruption remains possible as well. Decentralized finance protocols attempt to remove intermediaries entirely by enabling peer‑to‑peer financial services on blockchain networks.
Given how quickly the industry is evolving, it is hard to know whether Galaxy will remain a central intermediary or whether new structures will replace centralized platforms.
For conservative investors who prefer stable industry structures, the business may fall into the too hard pile.
Multi-Year Thesis:
The following scenarios illustrate how outcomes could diverge over the next three to seven years.
Bear Scenario
Probability: 40 percent
Assumptions:
Crypto markets enter another prolonged downturn and trading volumes collapse. Venture investments tied to blockchain startups experience substantial write downs. Infrastructure projects struggle to secure high utilization or long term contracts. Free cash flow remains negative and additional equity issuance is required.
Estimated intrinsic value: approximately $15 per share.
Base Scenario
Probability: 40 percent
Assumptions:
Digital assets remain volatile but persist as a niche asset class. Trading and investment revenues fluctuate with market cycles. Asset management grows modestly while infrastructure assets achieve moderate utilization. Profitability stabilizes but remains cyclical.
Estimated intrinsic value: approximately $30 per share.
Bull Scenario
Probability: 20 percent
Assumptions:
Digital assets become deeply integrated into global capital markets. Institutional allocations increase steadily and crypto ETFs expand significantly. Galaxy successfully scales fee based asset management, advisory services, and institutional liquidity infrastructure. Data center assets secure high utilization through artificial intelligence workloads and long term contracts.
Estimated intrinsic value: approximately $55 per share.
Probability weighted valuation centers close to the current market price. That suggests the market is already discounting a meaningful portion of the upside scenario.
Margin of Safety Verdict:
The margin of safety principle requires buying a security at a substantial discount to conservatively estimated intrinsic value.
In Galaxy’s case, the inputs required to estimate intrinsic value are unreliable. Free cash flow appears volatile and may be negative. ROIC data is unavailable. Earnings fluctuate with crypto market conditions and mark‑to‑market asset valuations.
Even with generous assumptions, the probability‑weighted intrinsic value lands near the current price of about $30.
Without a clear discount of at least 20 percent to intrinsic value, the stock fails the margin of safety test.
Peak Margin Stress Test:
Crypto financial firms often report unusually strong profits during bull markets.
During these periods several dynamics inflate margins. Trading volumes surge. Bid‑ask spreads widen. Venture investments are marked up aggressively. Digital asset holdings appreciate.
When the cycle reverses, the process works in the opposite direction. Trading activity slows, spreads compress, venture valuations fall, and asset prices decline.
If Galaxy’s valuation today reflects strong trading conditions, a normalization scenario could lead to significant earnings compression.
In a prolonged crypto bear market, revenues could drop sharply while infrastructure and personnel costs remain relatively fixed. Under those conditions operating margins could contract dramatically and profits might disappear altogether.
This cyclicality creates the risk of meaningful downside if investors are capitalizing peak‑cycle earnings.
Valuation Framing:
Galaxy currently trades with a market capitalization near $11 to $12 billion and a share price around $30. Analyst targets cover a wide range, from roughly the high twenties to the mid fifties.
Traditional valuation approaches are difficult to apply.
Discounted cash flow models require stable free cash flow, which is currently absent. Earnings power valuation requires normalized profits across market cycles, which are hard to estimate because the business combines trading, venture investing, and infrastructure operations.
As a result the market often treats the company as a proxy for crypto adoption. When digital asset prices rise, expectations for Galaxy’s trading and investment profits increase. When crypto markets decline, the reverse tends to occur.
In practice, the stock often behaves less like a traditional financial services company and more like leveraged exposure to the broader crypto ecosystem.
Perception vs Reality:
Perception: Galaxy is a scalable financial platform that will capture toll‑like economics across the digital asset ecosystem.
Reality: A substantial portion of earnings still depends on trading activity and crypto price cycles.
Perception: Data center infrastructure provides massive upside through artificial intelligence demand.
Reality: Infrastructure projects are capital intensive and may generate lower returns on capital than financial services businesses.
Why This May Be Misunderstood:
Investors often underestimate how strongly crypto market cycles influence financial performance. During bull markets trading and investment profits can surge, creating the appearance of highly scalable earnings.
Another misunderstanding involves infrastructure economics. Enthusiasm around artificial intelligence demand can obscure the realities of building and operating data centers, including large capital requirements, power constraints, and long payback periods.
Three Measurable Things to Watch Next Quarter:
1. Free cash flow trajectory. Investors should watch whether cash burn improves or continues to deteriorate as infrastructure investments ramp.
2. Infrastructure utilization. Evidence of long‑term contracts for data center capacity would materially improve the predictability of returns.
3. Asset management growth. Expansion of fee‑based AUM could reduce reliance on trading revenues.
Historical Conviction Drift:
Available sentiment indicators point to moderate optimism among analysts and market participants. Most analyst ratings are positive and price targets generally sit above the current market price.
Sentiment, however, is not a substitute for fundamentals. In businesses tied to speculative markets, optimism can build quickly during favorable periods and disappear just as quickly when conditions reverse.
Disconfirming Evidence:
The strongest argument against owning the stock is that Galaxy may simply function as a leveraged vehicle for crypto market cycles rather than a durable compounding enterprise.
If profits depend primarily on rising digital asset prices, trading activity, and venture valuations, intrinsic value will move sharply with the broader crypto market. In that case investors are not buying a predictable operating business but making a macro bet on the trajectory of digital assets.
Risks:
Major structural risks include the following.
1. Crypto market cyclicality causing large swings in revenue and profitability.
2. Regulatory changes that restrict institutional participation in digital asset markets.
3. Infrastructure investments producing returns below the cost of capital.
4. Counterparty failures within the crypto ecosystem.
5. Continued equity dilution to finance expansion.
6. Competition from major banks and exchanges entering institutional crypto markets.
Summary:
Galaxy Digital represents an ambitious effort to build a full‑service financial institution for the digital asset economy while simultaneously investing in large‑scale computing infrastructure.
The opportunity could be substantial if digital assets become embedded in global financial markets and if the company’s infrastructure assets achieve strong utilization from artificial intelligence workloads.
For now, however, several ingredients of a traditional value investment are missing. Free cash flow appears deeply negative in recent years, normalized earnings are difficult to estimate, and the company is committing large amounts of capital to projects with uncertain returns.
Without stable cash generation or a clear margin of safety relative to intrinsic value, the stock currently looks more like macro exposure to crypto adoption than a predictable compounding business.
For investors focused on durable returns on capital and measurable downside protection, patience may be the more prudent stance.
Data Snapshot:
Current Share Price: about $30.32
Metric: Value
Current Price (GLXY): $30.32
Market Capitalization: $11.83 billion
Shares Outstanding: 191,850,792
Trailing P/E: N/A
Forward P/E: 250.91x
Enterprise Value (EV): $9.89 billion
EV/EBITDA: 0.17x
Revenue (TTM): $58.71 billion
Gross Margin: 100.00%
Operating Margin: 95.95%
Free Cash Flow (FCF): N/A
FCF Yield: N/A
52-Week Range: $16.43 to $45.92
Sector: Financial Services
Industry: Capital Markets
References:
1. GuruFocus, Galaxy Digital PE Ratio Page gurufocus.com/term/pe_ratio/TSX:GLXY?utm_source=webApp&utm_medium=ticker_link&utm_campaign=dcf_to_stock_summary
2. AlphaSpread, Galaxy Digital Company Summary alphaspread.com/security/tsx/glxy/summary
3. Investing.com, Galaxy Digital Financial Ratios investing.com/equities/galaxy-digital-ratios
4. Investing.com Nigeria Mirror, Galaxy Digital Ratios ng.investing.com/equities/galaxy-digital-ratios
5. SimplyWallSt, Galaxy Digital Overview simplywall.st/stocks/us/diversified-financials/nasdaq-glxy/galaxy-digital
6. GuruFocus, Galaxy Digital PE TTM gurufocus.com/term/pettm/MEX:GLXY
7. ValueInvesting.io, Galaxy Digital Intrinsic Value Estimate valueinvesting.io/GLXY.TO/valuation/intrinsic-value
8. GuruFocus, Galaxy Digital PE Ratio Page gurufocus.com/term/pe-ratio/GLXY
9. AlphaSpread, Galaxy Digital DCF Base Case alphaspread.com/security/tsx/glxy/dcf-valuation/base-case
10. AlphaSpread, Galaxy Digital NASDAQ DCF Base Case alphaspread.com/security/nasdaq/glxy/dcf-valuation/base-case
11. SimplyWallSt, Galaxy Digital Valuation simplywall.st/stocks/us/diversified-financials/nasdaq-glxy/galaxy-digital/valuation
12. Smart Investing, Galaxy Surfactants Company Page smart-investing.in/main.php?Company=GALAXY+SURFACTANTS+LTD
13. StockAnalysis.com, Galaxy Digital Statistics stockanalysis.com/stocks/glxy/statistics/
14. MarketBeat, Galaxy Digital Stock Overview marketbeat.com/stocks/TSE/GLXY/
15. Yahoo Finance, Galaxy Digital Key Statistics finance.yahoo.com/quote/GLXY/key-statistics/
16. Yahoo Finance News, Calculating Intrinsic Value Article finance.yahoo.com/news/calculating-intrinsic-value-galaxy-payroll-105236792.html
17. Validea Guru Analysis, GLXY validea.com/guru-analysis/glxy
18. StockGro, How to Find Intrinsic Value of a Stock stockgro.club/stoxo/resources/how-to-find-the-intrinsic-value-of-stock/
19. Medium, Intrinsic Value Using PE Ratio medium.com/@jdgb.projects/how-to-calculate-the-intrinsic-value-of-a-stock-using-the-p-e-ratio-9f19c31d294d
20. ValueSpreadsheet Blog, Intrinsic Value Formula valuespreadsheet.com/blog/easy-intrinsic-value-formula
21. MarketBeat, GLXY Earnings marketbeat.com/stocks/NASDAQ/GLXY/earnings/
22. SimplyWallSt, Galaxy Digital Past Performance simplywall.st/stocks/us/diversified-financials/nasdaq-glxy/galaxy-digital/past
23. ChartMill, Analyst Ratings chartmill.com/stock/quote/GLXY/analyst-ratings
24. Macrotrends, Galaxy Digital Revenue History macrotrends.net/stocks/charts/GLXY/galaxy-digital/revenue
25. Public.com, GLXY Earnings public.com/stocks/glxy/earnings
26. SimplyWallSt, Galaxy Digital Future Forecast simplywall.st/stocks/us/diversified-financials/nasdaq-glxy/galaxy-digital/future
27. StockInvest, GLXY Earnings Report stockinvest.us/earnings-report/GLXY
28. KoalaGains, GLXY Stock Overview koalagains.com/stocks/NASDAQ/GLXY
29. Optionslam, GLXY Earnings optionslam.com/earnings/stocks/GLXY
30. Digrin, GLXY Earnings digrin.com/stocks/detail/GLXY.TO/earnings
31. ChartMill, GLXY Fundamental Analysis chartmill.com/stock/quote/GLXY.CA/fundamental-analysis
32. The Motley Fool, Galaxy Digital Q1 2026 Earnings Call Transcript fool.com/earnings/call-transcripts/2026/04/28/galaxy-digital-glxy-q1-2026-earnings-transcript/
33. Barchart, Galaxy Digital Crypto Recovery Narrative barchart.com/story/news/1545028/galaxy-digital-s-crypto-recovery-narrative-gets-its-first-real-test-tomorrow
34. Yahoo Finance Markets, Story Shifting for Galaxy Digital finance.yahoo.com/markets/stocks/articles/story-shifting-galaxy-digital-nasdaqgs-230857946.html
35. Yahoo Finance, GLXY Analysis finance.yahoo.com/quote/GLXY/analysis/
36. Morningstar, GLXY Quote morningstar.com/stocks/xnas/glxy/quote
37. MarketBeat, Bullish Case for Galaxy Digital in 2026 marketbeat.com/originals/the-bullish-case-for-galaxy-digital-in-2026/
38. AlphaSpread, Analyst Estimates alphaspread.com/security/nasdaq/glxy/analyst-estimates
39. Kavout Market Lens, Drivers of Galaxy Digital Volatility kavout.com/market-lens/what-s-driving-galaxy-digital-s-volatility-amidst-crypto-swings
40. Wall Street Journal Market Data, GLXY Research Ratings wsj.com/market-data/quotes/GLXY/research-ratings
41. Seeking Alpha, GLXY Sell Side Ratings seekingalpha.com/symbol/GLXY/ratings/sell-side-ratings
42. Public.com, GLXY Price Target Forecast public.com/stocks/glxy/forecast-price-target
43. MarketBeat, GLXY Forecast marketbeat.com/stocks/NASDAQ/GLXY/forecast/
44. MarketWatch, GLXY Analyst Estimates marketwatch.com/investing/stock/glxy/analystestimates
45. MarketScreener, Galaxy Digital Consensus marketscreener.com/quote/stock/GALAXY-DIGITAL-INC-188580758/consensus/
46. Investing.com, GLXY Consensus Estimates investing.com/equities/galaxy-digital-consensus-estimates
47. TipRanks, GLXY Forecast tipranks.com/stocks/glxy/forecast
48. Investing.com News, Jefferies Price Target Article investing.com/news/analyst-ratings/galaxy-digital-stock-price-target-reiterated-at-45-by-jefferies-on-strong-q3-93CH-4299591
49. StockAnalysis.com, GLXY Overview stockanalysis.com/stocks/glxy/
50. MarketScreener, Galaxy Digital Holdings Consensus marketscreener.com/quote/stock/GALAXY-DIGITAL-HOLDINGS-49479424/consensus/
51. The Globe and Mail, GLXY Research theglobeandmail.com/investing/markets/stocks/GLXY-T/research/
52. CNN Business Markets, GLXY cnn.com/markets/stocks/GLXY
53. Yahoo Finance, GLXY Quote finance.yahoo.com/quote/GLXY/
54. Source identity unavailable in payload t.co/jmheg91l7t
55. Source identity unavailable in payload api.tavily.com/search
Disclaimer:
This analysis is for informational purposes only and does not constitute investment advice. Investors should conduct independent research and consider their own financial situation before making investment decisions.
Margin of safety verdict: At roughly $30 per share, Galaxy Digital does not appear to offer a demonstrable margin of safety because normalized earnings and free cash flow cannot be estimated with confidence.
Galaxy Digital is often framed as a bridge between traditional finance and the digital asset economy. The firm runs a mix of businesses tied to crypto markets: trading and market making, asset management, advisory work similar to investment banking, venture investing, and infrastructure tied to mining and computing.
The long-term bull thesis is straightforward. If digital assets become a permanent part of global capital markets, Galaxy could evolve into a full financial platform for the ecosystem. In that scenario the company would collect fees from multiple layers of activity: trading, custody, ETFs, capital markets, and potentially high‑performance computing infrastructure.
The problem is that the current economics are difficult to analyze through a traditional value framework. Free cash flow has appeared deeply negative in recent years. Share dilution has increased. At the same time the company is committing large amounts of capital to infrastructure projects whose long-term returns remain uncertain. Much of the company’s profitability also continues to track crypto market cycles.
So the key question is not whether crypto markets grow over time. The question is whether Galaxy can consistently earn durable returns on capital through those cycles. Until that shows up in sustained cash flow, the stock behaves less like a compounding business and more like a macro proxy for crypto adoption.
One Stock, Dozens of Voices:
This is not one analyst's opinion. CrowdWisdom aggregated 2 independent sources for GLXY (1 live market intelligence feeds; 1 verified financial data checks (Yahoo Finance)) and synthesized the shared thesis: what do dozens of traders, investors, and researchers broadly agree on, where do they disagree, and what might the market be missing?
The evidence was then stress tested by setting opposing views against each other: a bull case, a bear case that challenges the consensus, and an examination of what expectations may already be reflected in the current price. All financial metrics were cross validated against live market data.
What follows highlights where opinions converge, where they split, and whether the stock provides any meaningful margin of safety at today’s price.
Business Quality and Moat Durability:
Galaxy Digital operates across several segments of the digital asset economy. These include institutional trading and market making, asset management products, advisory services resembling investment banking, venture investments in crypto startups, and infrastructure such as mining operations and large-scale data centers.
The broader strategy resembles a merchant bank built around digital assets.
In theory, several advantages could support that model.
One is institutional positioning. Large investors entering crypto markets typically require regulated counterparties with compliance systems comparable to traditional financial firms. Galaxy has tried to establish itself as one of the few crypto‑native platforms capable of serving hedge funds, asset managers, and sovereign capital.
Another advantage is platform integration. By running trading desks, venture portfolios, asset management products, and advisory services simultaneously, the company sits close to capital flows across the ecosystem. A firm advising blockchain startups, managing funds, and providing liquidity can potentially develop information advantages and cross‑selling opportunities.
There are also potential liquidity network effects. In financial markets, liquidity tends to attract more liquidity. Once an intermediary becomes a preferred counterparty, that position can reinforce itself.
Despite these theoretical advantages, the moat remains fragile.
Crypto trading infrastructure is highly competitive. Exchanges, market makers, and prime brokerage platforms all compete for institutional order flow. Switching costs are relatively low because sophisticated clients can route trades across multiple venues.
Large financial institutions are also moving into the space. If regulatory frameworks stabilize, global banks and exchanges could compete directly for institutional crypto services. At the same time, decentralized finance platforms aim to remove intermediaries entirely by enabling peer‑to‑peer financial transactions.
Moat durability verdict: narrow and uncertain. Any competitive advantage depends heavily on a market structure that is still evolving.
Return on Invested Capital (ROIC):
For long‑term investors, the central question is whether the company can generate attractive returns on invested capital over time.
Trading desks and venture portfolios can produce extremely high returns during strong markets. The difficulty is that those returns tend to be episodic. They often depend more on asset price appreciation than on durable competitive advantages.
Galaxy now appears to be expanding aggressively into capital‑intensive infrastructure.
The company has invested in large facilities designed for crypto mining and high‑performance computing workloads. These assets may eventually support artificial intelligence training or other compute‑heavy applications.
That shift changes the economics of the business.
Financial services businesses are usually capital light. Infrastructure businesses are not. Data centers require large upfront investment, long development timelines, and high utilization rates to earn acceptable returns.
If Galaxy commits substantial capital to infrastructure, incremental ROIC could compress meaningfully. Mature data center operators generally earn moderate returns relative to the occasionally extreme returns that trading businesses can produce during bull markets.
Utilization becomes the critical variable. If the company secures long‑term compute contracts with strong counterparties, returns could become stable though possibly lower. If utilization fluctuates alongside crypto cycles or speculative demand, returns could deteriorate.
Because verified ROIC figures are unavailable in the dataset, investors cannot confidently evaluate the trajectory. That lack of visibility alone is a significant analytical limitation.
Quality of Earnings:
One of the more concerning signals appears in the trend of free cash flow.
Recent financial analysis suggests free cash flow deteriorated sharply between 2022 and 2025, moving from roughly negative tens of millions to approximately negative $1.5 billion. Even allowing for estimation error, the scale of the change suggests substantial cash consumption.
Several forces may explain this.
First, infrastructure development requires heavy capital spending. Data center construction, power systems, and computing hardware must be deployed well before revenue is generated.
Second, the company holds digital asset investments and venture positions whose values fluctuate. Mark‑to‑market accounting can inflate earnings during bull markets while masking the volatility of underlying cash flow.
Third, trading operations can introduce large swings in working capital.
Another signal worth noting is dilution. The number of shares outstanding has risen sharply in recent years. For example, the share count increased significantly between 2024 and 2025, suggesting that equity issuance has been used to fund part of the expansion strategy.
For long‑term investors, accounting earnings matter less than free cash flow per share. If dilution continues while free cash flow remains negative, the economic value accruing to each shareholder may decline.
Capital Allocation Scorecard:
Capital allocation is ultimately the clearest test of management discipline.
Galaxy’s capital deployment in recent years reflects three major patterns.
Infrastructure expansion. The company has committed significant capital to data center and mining‑related assets. These investments could eventually produce stable contracted revenue, but the capital intensity and long payback periods increase execution risk.
Equity issuance. Rising share counts suggest the firm has relied on equity financing rather than internally generated cash. For existing shareholders this represents dilution of future earnings.
Limited shareholder returns. There is little evidence of meaningful buybacks or dividends. That is not unusual for a company pursuing aggressive growth, but it also means investors depend entirely on future capital appreciation.
Overall capital allocation grade: uncertain with rising capital intensity.
Customer and Revenue Concentration:
Verified data on customer concentration is not available. However the structure of institutional crypto markets implies potential concentration risk.
A large share of trading activity typically comes from a relatively small group of hedge funds, proprietary trading firms, and crypto‑native investment funds. These participants control a significant portion of liquidity.
If a handful of large clients represent a meaningful share of revenue, switching risk becomes material. Sophisticated trading firms can shift activity quickly to other exchanges or prime brokers if fees rise or liquidity weakens.
Meanwhile, large banks and exchanges are building their own institutional crypto infrastructure and may compete for the same client base.
Without clear disclosure on customer concentration, this remains an important unknown.
Management Alignment:
Galaxy Digital was founded by Mike Novogratz, a well‑known investor who became deeply involved in the cryptocurrency ecosystem early in its development.
Founder‑led companies can benefit from long‑term vision and a willingness to pursue ambitious strategies. Ultimately, though, alignment comes down to incentives and capital discipline.
Detailed insider ownership data is not available in the dataset, which limits the ability to assess alignment precisely. Investors should watch whether management focuses on creating value per share or continues issuing equity to fund expansion.
10-Year Durability Test:
Trying to forecast the structure of digital asset finance ten years from now is extremely difficult.
Several structural forces could reshape the industry.
Regulation is probably the largest variable. Governments around the world continue debating how digital assets should be governed. Strict regulation could constrain trading, lending, and token issuance, while favorable frameworks could accelerate institutional adoption.
Institutional participation is another key factor. The bullish case assumes digital assets become a permanent allocation in global portfolios, similar to commodities or emerging market equities. If adoption stalls, many intermediaries could struggle.
Competition from traditional finance is also likely to intensify. Global banks, exchanges, and fintech firms are investing heavily in crypto infrastructure and may eventually dominate regulated markets.
Technological disruption remains possible as well. Decentralized finance protocols attempt to remove intermediaries entirely by enabling peer‑to‑peer financial services on blockchain networks.
Given how quickly the industry is evolving, it is hard to know whether Galaxy will remain a central intermediary or whether new structures will replace centralized platforms.
For conservative investors who prefer stable industry structures, the business may fall into the too hard pile.
Multi-Year Thesis:
The following scenarios illustrate how outcomes could diverge over the next three to seven years.
Bear Scenario
Probability: 40 percent
Assumptions:
Crypto markets enter another prolonged downturn and trading volumes collapse. Venture investments tied to blockchain startups experience substantial write downs. Infrastructure projects struggle to secure high utilization or long term contracts. Free cash flow remains negative and additional equity issuance is required.
Estimated intrinsic value: approximately $15 per share.
Base Scenario
Probability: 40 percent
Assumptions:
Digital assets remain volatile but persist as a niche asset class. Trading and investment revenues fluctuate with market cycles. Asset management grows modestly while infrastructure assets achieve moderate utilization. Profitability stabilizes but remains cyclical.
Estimated intrinsic value: approximately $30 per share.
Bull Scenario
Probability: 20 percent
Assumptions:
Digital assets become deeply integrated into global capital markets. Institutional allocations increase steadily and crypto ETFs expand significantly. Galaxy successfully scales fee based asset management, advisory services, and institutional liquidity infrastructure. Data center assets secure high utilization through artificial intelligence workloads and long term contracts.
Estimated intrinsic value: approximately $55 per share.
Probability weighted valuation centers close to the current market price. That suggests the market is already discounting a meaningful portion of the upside scenario.
Margin of Safety Verdict:
The margin of safety principle requires buying a security at a substantial discount to conservatively estimated intrinsic value.
In Galaxy’s case, the inputs required to estimate intrinsic value are unreliable. Free cash flow appears volatile and may be negative. ROIC data is unavailable. Earnings fluctuate with crypto market conditions and mark‑to‑market asset valuations.
Even with generous assumptions, the probability‑weighted intrinsic value lands near the current price of about $30.
Without a clear discount of at least 20 percent to intrinsic value, the stock fails the margin of safety test.
Peak Margin Stress Test:
Crypto financial firms often report unusually strong profits during bull markets.
During these periods several dynamics inflate margins. Trading volumes surge. Bid‑ask spreads widen. Venture investments are marked up aggressively. Digital asset holdings appreciate.
When the cycle reverses, the process works in the opposite direction. Trading activity slows, spreads compress, venture valuations fall, and asset prices decline.
If Galaxy’s valuation today reflects strong trading conditions, a normalization scenario could lead to significant earnings compression.
In a prolonged crypto bear market, revenues could drop sharply while infrastructure and personnel costs remain relatively fixed. Under those conditions operating margins could contract dramatically and profits might disappear altogether.
This cyclicality creates the risk of meaningful downside if investors are capitalizing peak‑cycle earnings.
Valuation Framing:
Galaxy currently trades with a market capitalization near $11 to $12 billion and a share price around $30. Analyst targets cover a wide range, from roughly the high twenties to the mid fifties.
Traditional valuation approaches are difficult to apply.
Discounted cash flow models require stable free cash flow, which is currently absent. Earnings power valuation requires normalized profits across market cycles, which are hard to estimate because the business combines trading, venture investing, and infrastructure operations.
As a result the market often treats the company as a proxy for crypto adoption. When digital asset prices rise, expectations for Galaxy’s trading and investment profits increase. When crypto markets decline, the reverse tends to occur.
In practice, the stock often behaves less like a traditional financial services company and more like leveraged exposure to the broader crypto ecosystem.
Perception vs Reality:
Perception: Galaxy is a scalable financial platform that will capture toll‑like economics across the digital asset ecosystem.
Reality: A substantial portion of earnings still depends on trading activity and crypto price cycles.
Perception: Data center infrastructure provides massive upside through artificial intelligence demand.
Reality: Infrastructure projects are capital intensive and may generate lower returns on capital than financial services businesses.
Why This May Be Misunderstood:
Investors often underestimate how strongly crypto market cycles influence financial performance. During bull markets trading and investment profits can surge, creating the appearance of highly scalable earnings.
Another misunderstanding involves infrastructure economics. Enthusiasm around artificial intelligence demand can obscure the realities of building and operating data centers, including large capital requirements, power constraints, and long payback periods.
Three Measurable Things to Watch Next Quarter:
1. Free cash flow trajectory. Investors should watch whether cash burn improves or continues to deteriorate as infrastructure investments ramp.
2. Infrastructure utilization. Evidence of long‑term contracts for data center capacity would materially improve the predictability of returns.
3. Asset management growth. Expansion of fee‑based AUM could reduce reliance on trading revenues.
Historical Conviction Drift:
Available sentiment indicators point to moderate optimism among analysts and market participants. Most analyst ratings are positive and price targets generally sit above the current market price.
Sentiment, however, is not a substitute for fundamentals. In businesses tied to speculative markets, optimism can build quickly during favorable periods and disappear just as quickly when conditions reverse.
Disconfirming Evidence:
The strongest argument against owning the stock is that Galaxy may simply function as a leveraged vehicle for crypto market cycles rather than a durable compounding enterprise.
If profits depend primarily on rising digital asset prices, trading activity, and venture valuations, intrinsic value will move sharply with the broader crypto market. In that case investors are not buying a predictable operating business but making a macro bet on the trajectory of digital assets.
Risks:
Major structural risks include the following.
1. Crypto market cyclicality causing large swings in revenue and profitability.
2. Regulatory changes that restrict institutional participation in digital asset markets.
3. Infrastructure investments producing returns below the cost of capital.
4. Counterparty failures within the crypto ecosystem.
5. Continued equity dilution to finance expansion.
6. Competition from major banks and exchanges entering institutional crypto markets.
Summary:
Galaxy Digital represents an ambitious effort to build a full‑service financial institution for the digital asset economy while simultaneously investing in large‑scale computing infrastructure.
The opportunity could be substantial if digital assets become embedded in global financial markets and if the company’s infrastructure assets achieve strong utilization from artificial intelligence workloads.
For now, however, several ingredients of a traditional value investment are missing. Free cash flow appears deeply negative in recent years, normalized earnings are difficult to estimate, and the company is committing large amounts of capital to projects with uncertain returns.
Without stable cash generation or a clear margin of safety relative to intrinsic value, the stock currently looks more like macro exposure to crypto adoption than a predictable compounding business.
For investors focused on durable returns on capital and measurable downside protection, patience may be the more prudent stance.
Data Snapshot:
Current Share Price: about $30.32
Metric: Value
Current Price (GLXY): $30.32
Market Capitalization: $11.83 billion
Shares Outstanding: 191,850,792
Trailing P/E: N/A
Forward P/E: 250.91x
Enterprise Value (EV): $9.89 billion
EV/EBITDA: 0.17x
Revenue (TTM): $58.71 billion
Gross Margin: 100.00%
Operating Margin: 95.95%
Free Cash Flow (FCF): N/A
FCF Yield: N/A
52-Week Range: $16.43 to $45.92
Sector: Financial Services
Industry: Capital Markets
References:
1. GuruFocus, Galaxy Digital PE Ratio Page gurufocus.com/term/pe_ratio/TSX:GLXY?utm_source=webApp&utm_medium=ticker_link&utm_campaign=dcf_to_stock_summary
2. AlphaSpread, Galaxy Digital Company Summary alphaspread.com/security/tsx/glxy/summary
3. Investing.com, Galaxy Digital Financial Ratios investing.com/equities/galaxy-digital-ratios
4. Investing.com Nigeria Mirror, Galaxy Digital Ratios ng.investing.com/equities/galaxy-digital-ratios
5. SimplyWallSt, Galaxy Digital Overview simplywall.st/stocks/us/diversified-financials/nasdaq-glxy/galaxy-digital
6. GuruFocus, Galaxy Digital PE TTM gurufocus.com/term/pettm/MEX:GLXY
7. ValueInvesting.io, Galaxy Digital Intrinsic Value Estimate valueinvesting.io/GLXY.TO/valuation/intrinsic-value
8. GuruFocus, Galaxy Digital PE Ratio Page gurufocus.com/term/pe-ratio/GLXY
9. AlphaSpread, Galaxy Digital DCF Base Case alphaspread.com/security/tsx/glxy/dcf-valuation/base-case
10. AlphaSpread, Galaxy Digital NASDAQ DCF Base Case alphaspread.com/security/nasdaq/glxy/dcf-valuation/base-case
11. SimplyWallSt, Galaxy Digital Valuation simplywall.st/stocks/us/diversified-financials/nasdaq-glxy/galaxy-digital/valuation
12. Smart Investing, Galaxy Surfactants Company Page smart-investing.in/main.php?Company=GALAXY+SURFACTANTS+LTD
13. StockAnalysis.com, Galaxy Digital Statistics stockanalysis.com/stocks/glxy/statistics/
14. MarketBeat, Galaxy Digital Stock Overview marketbeat.com/stocks/TSE/GLXY/
15. Yahoo Finance, Galaxy Digital Key Statistics finance.yahoo.com/quote/GLXY/key-statistics/
16. Yahoo Finance News, Calculating Intrinsic Value Article finance.yahoo.com/news/calculating-intrinsic-value-galaxy-payroll-105236792.html
17. Validea Guru Analysis, GLXY validea.com/guru-analysis/glxy
18. StockGro, How to Find Intrinsic Value of a Stock stockgro.club/stoxo/resources/how-to-find-the-intrinsic-value-of-stock/
19. Medium, Intrinsic Value Using PE Ratio medium.com/@jdgb.projects/how-to-calculate-the-intrinsic-value-of-a-stock-using-the-p-e-ratio-9f19c31d294d
20. ValueSpreadsheet Blog, Intrinsic Value Formula valuespreadsheet.com/blog/easy-intrinsic-value-formula
21. MarketBeat, GLXY Earnings marketbeat.com/stocks/NASDAQ/GLXY/earnings/
22. SimplyWallSt, Galaxy Digital Past Performance simplywall.st/stocks/us/diversified-financials/nasdaq-glxy/galaxy-digital/past
23. ChartMill, Analyst Ratings chartmill.com/stock/quote/GLXY/analyst-ratings
24. Macrotrends, Galaxy Digital Revenue History macrotrends.net/stocks/charts/GLXY/galaxy-digital/revenue
25. Public.com, GLXY Earnings public.com/stocks/glxy/earnings
26. SimplyWallSt, Galaxy Digital Future Forecast simplywall.st/stocks/us/diversified-financials/nasdaq-glxy/galaxy-digital/future
27. StockInvest, GLXY Earnings Report stockinvest.us/earnings-report/GLXY
28. KoalaGains, GLXY Stock Overview koalagains.com/stocks/NASDAQ/GLXY
29. Optionslam, GLXY Earnings optionslam.com/earnings/stocks/GLXY
30. Digrin, GLXY Earnings digrin.com/stocks/detail/GLXY.TO/earnings
31. ChartMill, GLXY Fundamental Analysis chartmill.com/stock/quote/GLXY.CA/fundamental-analysis
32. The Motley Fool, Galaxy Digital Q1 2026 Earnings Call Transcript fool.com/earnings/call-transcripts/2026/04/28/galaxy-digital-glxy-q1-2026-earnings-transcript/
33. Barchart, Galaxy Digital Crypto Recovery Narrative barchart.com/story/news/1545028/galaxy-digital-s-crypto-recovery-narrative-gets-its-first-real-test-tomorrow
34. Yahoo Finance Markets, Story Shifting for Galaxy Digital finance.yahoo.com/markets/stocks/articles/story-shifting-galaxy-digital-nasdaqgs-230857946.html
35. Yahoo Finance, GLXY Analysis finance.yahoo.com/quote/GLXY/analysis/
36. Morningstar, GLXY Quote morningstar.com/stocks/xnas/glxy/quote
37. MarketBeat, Bullish Case for Galaxy Digital in 2026 marketbeat.com/originals/the-bullish-case-for-galaxy-digital-in-2026/
38. AlphaSpread, Analyst Estimates alphaspread.com/security/nasdaq/glxy/analyst-estimates
39. Kavout Market Lens, Drivers of Galaxy Digital Volatility kavout.com/market-lens/what-s-driving-galaxy-digital-s-volatility-amidst-crypto-swings
40. Wall Street Journal Market Data, GLXY Research Ratings wsj.com/market-data/quotes/GLXY/research-ratings
41. Seeking Alpha, GLXY Sell Side Ratings seekingalpha.com/symbol/GLXY/ratings/sell-side-ratings
42. Public.com, GLXY Price Target Forecast public.com/stocks/glxy/forecast-price-target
43. MarketBeat, GLXY Forecast marketbeat.com/stocks/NASDAQ/GLXY/forecast/
44. MarketWatch, GLXY Analyst Estimates marketwatch.com/investing/stock/glxy/analystestimates
45. MarketScreener, Galaxy Digital Consensus marketscreener.com/quote/stock/GALAXY-DIGITAL-INC-188580758/consensus/
46. Investing.com, GLXY Consensus Estimates investing.com/equities/galaxy-digital-consensus-estimates
47. TipRanks, GLXY Forecast tipranks.com/stocks/glxy/forecast
48. Investing.com News, Jefferies Price Target Article investing.com/news/analyst-ratings/galaxy-digital-stock-price-target-reiterated-at-45-by-jefferies-on-strong-q3-93CH-4299591
49. StockAnalysis.com, GLXY Overview stockanalysis.com/stocks/glxy/
50. MarketScreener, Galaxy Digital Holdings Consensus marketscreener.com/quote/stock/GALAXY-DIGITAL-HOLDINGS-49479424/consensus/
51. The Globe and Mail, GLXY Research theglobeandmail.com/investing/markets/stocks/GLXY-T/research/
52. CNN Business Markets, GLXY cnn.com/markets/stocks/GLXY
53. Yahoo Finance, GLXY Quote finance.yahoo.com/quote/GLXY/
54. Source identity unavailable in payload t.co/jmheg91l7t
55. Source identity unavailable in payload api.tavily.com/search
Disclaimer:
This analysis is for informational purposes only and does not constitute investment advice. Investors should conduct independent research and consider their own financial situation before making investment decisions.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.