
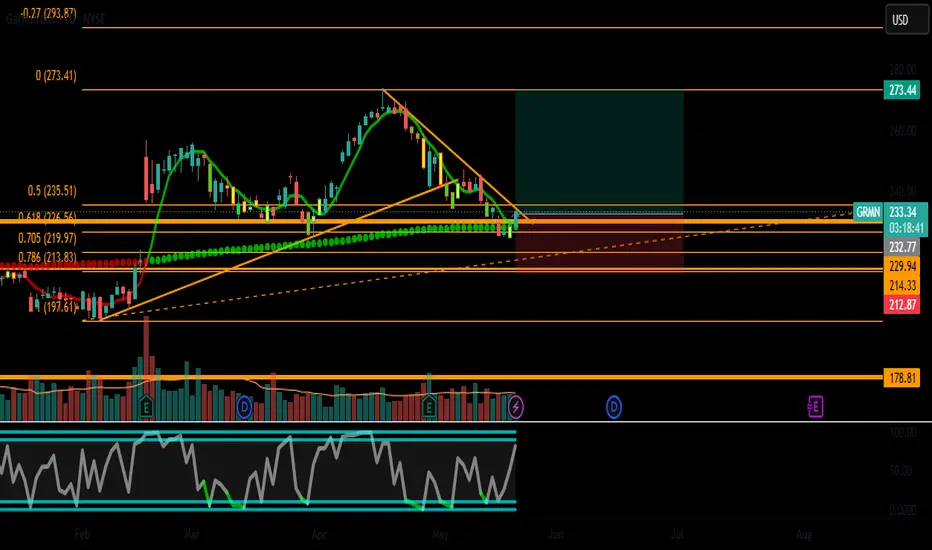
📊 Our system signal (Score_Pro = 4.5 → WATCH)
We use proprietary quantitative software that integrates fundamentals (ratios, revenue/debt) and technicals across 3 timeframes. The data from our tables shows:
Concept/Value
Financial ratios suggestion / Sell (overvalued: P/E 25.5x, P/S 5.9x, P/B 4.76x)
Revenue/Earnings suggestion / Buy (strong growth +17.9% YoY)
Debt suggestion / Buy (score 10, zero debt)
Fundamental Score /4.0
Daily Technical / Sell (bearish)
4H Technical / Sell (bearish)
1H Technical / Hold (bearish)
Pro Score / 4.5
→ Mixed fundamentals (expensive ratios but solid growth and zero debt). Overall technical is bearish, but the RSI in extreme oversold (32.4) suggests a bounce is imminent.
🎯 Trade Setup
Entry: $232.77
Stop Loss: $212.87 (~ -8.6%)
Take Profit: $273.44 (~ +17.5%)
R:R: ~1 : 2.0
Horizon: 1-3 months (swing/position)
📈 Catalysts – Q1 2026 Earnings (Apr 29) + Recent News
Pro Forma EPS: $2.08 (+29% YoY), beat estimates by +13%
Revenue: $1.75B (+14% YoY), record Q1
Fitness segment: +42% to $547M – driven by advanced wearables
Gross margin: 59.4% (+180 bps) | Operating margin: 24.6% (+290 bps)
Zero debt, cash & marketable securities: $4.3B
Share buyback: $40M in Q1 | Dividend: ~1.66% annual yield
Recent news (May 20):
Garmin selected as official supplier of Luna Rossa, the Italian challenger for the 38th America’s Cup (to be held in Naples, Italy in 2027). Garmin will supply marine navigation, communications, and fitness equipment – a brand visibility and credibility catalyst for the Marine segment.
FY2026 Guidance: Reaffirmed at
7.9Brevenue,9.35 EPS.
📊 Technical Context
RSI (14 days): ~32.4 – oversold territory, anticipating a bounce
Moving averages: Price below SMA20 and SMA50 (bearish), but SMA200 acts as key support
Key levels:
Immediate support: $228-230 (200-day SMA)
Short-term resistance: $245-250
Main target (TP): $273.44 (near 52-week high)
⚠️ Risks to consider
Expensive valuation: P/E 25.2x vs. consumer durables industry ~11x. If growth normalizes, multiple compression is possible.
Elevated inventory: ~$1.9B (+16% YoY) – potential overstocking.
Outdoor segment declining: -5% YoY due to tough comps.
Rising operating expenses: +$59M (+11%) driven by personnel costs.
The technical bounce still needs confirmation with institutional volume.
📌 Bottom Line
Garmin is an exceptional quality company (impeccable balance sheet, high margins, leadership in Fitness) but trades at a premium valuation that already prices in much of the expected growth. Technically, the stock is in oversold territory with the 200-day SMA acting as a floor, offering a bounce setup with ~1:2 R:R.
Plan: Enter at 232.77, stop at 212.87, target $273.44. Best suited for medium-term positions seeking a technical rebound backed by solid fundamentals.
⚠️ Disclaimer: This post is for educational and informational purposes only, based on our proprietary software and public sources. It does not constitute financial advice. Trading involves risk of loss. Always do your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results.
We use proprietary quantitative software that integrates fundamentals (ratios, revenue/debt) and technicals across 3 timeframes. The data from our tables shows:
Concept/Value
Financial ratios suggestion / Sell (overvalued: P/E 25.5x, P/S 5.9x, P/B 4.76x)
Revenue/Earnings suggestion / Buy (strong growth +17.9% YoY)
Debt suggestion / Buy (score 10, zero debt)
Fundamental Score /4.0
Daily Technical / Sell (bearish)
4H Technical / Sell (bearish)
1H Technical / Hold (bearish)
Pro Score / 4.5
→ Mixed fundamentals (expensive ratios but solid growth and zero debt). Overall technical is bearish, but the RSI in extreme oversold (32.4) suggests a bounce is imminent.
🎯 Trade Setup
Entry: $232.77
Stop Loss: $212.87 (~ -8.6%)
Take Profit: $273.44 (~ +17.5%)
R:R: ~1 : 2.0
Horizon: 1-3 months (swing/position)
📈 Catalysts – Q1 2026 Earnings (Apr 29) + Recent News
Pro Forma EPS: $2.08 (+29% YoY), beat estimates by +13%
Revenue: $1.75B (+14% YoY), record Q1
Fitness segment: +42% to $547M – driven by advanced wearables
Gross margin: 59.4% (+180 bps) | Operating margin: 24.6% (+290 bps)
Zero debt, cash & marketable securities: $4.3B
Share buyback: $40M in Q1 | Dividend: ~1.66% annual yield
Recent news (May 20):
Garmin selected as official supplier of Luna Rossa, the Italian challenger for the 38th America’s Cup (to be held in Naples, Italy in 2027). Garmin will supply marine navigation, communications, and fitness equipment – a brand visibility and credibility catalyst for the Marine segment.
FY2026 Guidance: Reaffirmed at
7.9Brevenue,9.35 EPS.
📊 Technical Context
RSI (14 days): ~32.4 – oversold territory, anticipating a bounce
Moving averages: Price below SMA20 and SMA50 (bearish), but SMA200 acts as key support
Key levels:
Immediate support: $228-230 (200-day SMA)
Short-term resistance: $245-250
Main target (TP): $273.44 (near 52-week high)
⚠️ Risks to consider
Expensive valuation: P/E 25.2x vs. consumer durables industry ~11x. If growth normalizes, multiple compression is possible.
Elevated inventory: ~$1.9B (+16% YoY) – potential overstocking.
Outdoor segment declining: -5% YoY due to tough comps.
Rising operating expenses: +$59M (+11%) driven by personnel costs.
The technical bounce still needs confirmation with institutional volume.
📌 Bottom Line
Garmin is an exceptional quality company (impeccable balance sheet, high margins, leadership in Fitness) but trades at a premium valuation that already prices in much of the expected growth. Technically, the stock is in oversold territory with the 200-day SMA acting as a floor, offering a bounce setup with ~1:2 R:R.
Plan: Enter at 232.77, stop at 212.87, target $273.44. Best suited for medium-term positions seeking a technical rebound backed by solid fundamentals.
⚠️ Disclaimer: This post is for educational and informational purposes only, based on our proprietary software and public sources. It does not constitute financial advice. Trading involves risk of loss. Always do your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.