
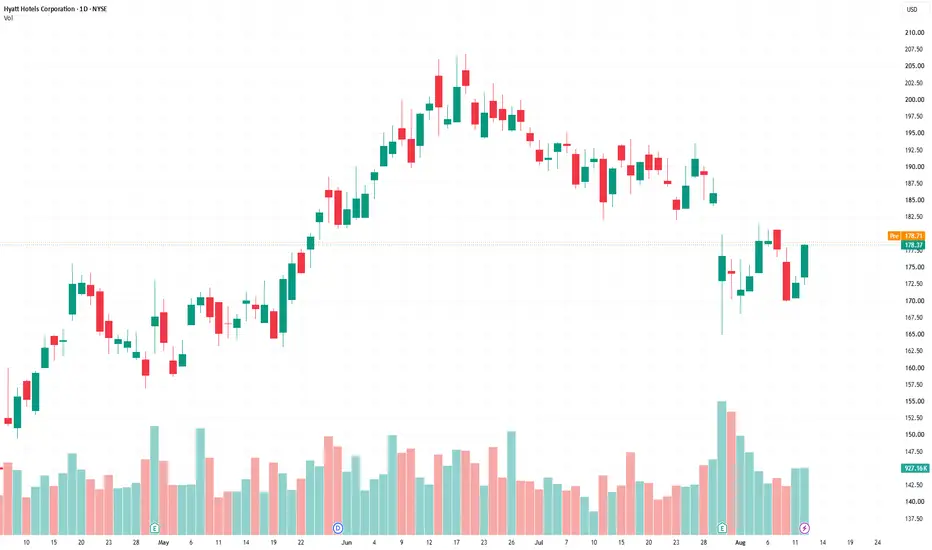
Hyatt Hotels (H): Post-Earnings Pullback Creates a Tactical Buying Opportunity
Hyatt Hotels Corporation (H)
Hotels, Resorts & Cruise Lines
Ticker: H
Price at time of analysis: $173.60
Current price (August 13, 2026): $178.37
Target: $190
Stop Loss: $162
Key Arguments Supporting the Idea
Following its July 30 earnings report, Hyatt shares fell 6.7%, closing at $173.60 on August 4. The main driver of the selloff was a reduction in the company’s net rooms growth guidance from 6–7% to approximately 6%.
At the same time, Hyatt raised its 2026 RevPAR growth guidance to 3.5–4.5% and maintained most of its other full-year targets. The main exception was net income guidance, which was lowered from $255–350 million to $250–335 million.
Over the next two months, the stock could find support from share repurchases, resilient demand, improving performance in Mexico, and potential hotel asset sales. During the first half of the year, Hyatt returned $175 million to shareholders, leaving another $150–200 million in combined dividends and share repurchases to reach its full-year target of $325–375 million.
Investment Thesis
Hyatt is a global hotel operator focused primarily on the premium segment. As of June 30, 2026, the company’s portfolio comprised 1,559 properties and 377,900 rooms across 83 countries.
According to the company, approximately 89% of adjusted EBITDA in 2025 was generated by asset-light businesses that require limited investment in real estate, including hotel management, franchising, and travel distribution.
Hyatt still owns 17 hotels with an estimated gross value of $2.2–2.5 billion.
The company operates across three main business segments: hotel management and franchising, owned and leased properties, and travel distribution.
The post-earnings decline was driven primarily by weaker net rooms growth guidance and temporary softness in Mexico and the Middle East. Meanwhile, Hyatt’s core hotel management and franchise businesses continued to show resilient underlying momentum.
Strong Q2 2026 Operating Results
Comparable RevPAR, or revenue per available room, increased 5.9% YoY. Average daily rate rose 5.0%, while occupancy improved by 0.6 percentage points.
RevPAR increased:
The weakest performance came from the Middle East and Africa, where RevPAR declined 28.3%.
During the earnings call, management noted that RevPAR in the Middle East alone fell 36%, primarily due to regional conflict.
Total revenue reached $1.829 billion, while adjusted EPS came in at $1.12.
In the all-inclusive resort segment, Net Package RevPAR declined 1.2%, reflecting the impact of a security incident in Mexico as well as reduced airline capacity on certain routes.
Asset-Light Revenue Remains Strong
Revenue from hotel management, franchising, and related services maintained solid growth momentum. In Q2 2026, combined revenue increased 7.8% to $324 million.
Base management fees rose 10.2%, franchise and other fee revenue increased 8.1%, and incentive management fees grew 2.6%.
Travel distribution remained under pressure due to softer demand in Mexico and temporary hotel closures in Jamaica following a hurricane.
Net rooms growth over the past 12 months was 3.9%, or 4.4% excluding Playa-related rooms that were removed from Hyatt’s reported room count in the second half of 2025.
The signed development pipeline reached a record 154,000 rooms, up 10% YoY.
More than half of the hotel openings planned for 2026 are scheduled for Q4, meaning some properties could ultimately be pushed into early 2027.
Full-Year Guidance Remains Resilient
Hyatt’s full-year outlook continues to point to resilient financial performance, although weaker net rooms growth expectations remain an important risk.
The company maintained its guidance for management, franchise, and related fee revenue at $1.305–1.335 billion, implying growth of 9–11%.
Adjusted EBITDA guidance remains at $1.155–1.205 billion, while adjusted free cash flow is expected to reach $580–630 million.
The next earnings report is expected in late October or early November, after the anticipated holding period for this trade.
Until then, the key factors to watch will be resilient U.S. demand, improving conditions in Mexico, and the absence of further delays to hotel openings.
Additional upside could come from the sale of another owned hotel or an acceleration in share repurchases, although neither catalyst is included in the base-case scenario.
Hyatt Trades at a Discount to Hilton
According to FactSet data as of August 4, 2026, Hyatt was trading at approximately 16.7x NTM EV/EBITDA at a share price of around $173.60, compared with approximately 19x for Hilton.
Based on our model, the $190 target price corresponds to an NTM EV/EBITDA multiple of approximately 18.2x.
This means the stock would need only a partial narrowing of its valuation discount to Hilton to reach our target.
Potential Catalysts
Three factors could drive the stock higher: continued strength in management and franchise fee revenue, improving conditions in Mexico, Jamaica, and the Middle East, and additional share repurchases or real estate disposals.
In Q2 2026, Hyatt spent only $12 million on share repurchases, partly due to temporary restrictions related to its Investor Day. However, significant capacity remains under the company’s share repurchase authorization.
That said, the timing of both share repurchases and asset sales remains uncertain.
Technical Setup
The technical setup supports opening a position, although the trade carries elevated risk.
The $174 entry price is below the 50-day moving average of approximately $189.50, but remains above the 200-day moving average of around $166.
The RSI is close to oversold territory.
Support is located in the $164–166 range, while a sustained move above $180 would signal improving momentum and open the way toward the $189–193 area.
The stop loss is set at $162. In the event of a gap down or significant slippage, the actual loss could exceed the planned amount.
Key Risks
The main risk is that temporary headwinds develop into a more prolonged slowdown.
New hotel openings could be delayed again, while the recovery in Cancun and the all-inclusive segment could take longer than expected.
Additional risks include continued weakness in the Middle East, hotel closures in Jamaica, volatility in the travel distribution business, and uncertainty surrounding the timing of real estate disposals.
The relatively low liquidity of Hyatt’s Class A shares could also contribute to sharper-than-usual price swings.
Hyatt Hotels Corporation (H)
Hotels, Resorts & Cruise Lines
Ticker: H
Price at time of analysis: $173.60
Current price (August 13, 2026): $178.37
Target: $190
Stop Loss: $162
Key Arguments Supporting the Idea
Following its July 30 earnings report, Hyatt shares fell 6.7%, closing at $173.60 on August 4. The main driver of the selloff was a reduction in the company’s net rooms growth guidance from 6–7% to approximately 6%.
At the same time, Hyatt raised its 2026 RevPAR growth guidance to 3.5–4.5% and maintained most of its other full-year targets. The main exception was net income guidance, which was lowered from $255–350 million to $250–335 million.
Over the next two months, the stock could find support from share repurchases, resilient demand, improving performance in Mexico, and potential hotel asset sales. During the first half of the year, Hyatt returned $175 million to shareholders, leaving another $150–200 million in combined dividends and share repurchases to reach its full-year target of $325–375 million.
Investment Thesis
Hyatt is a global hotel operator focused primarily on the premium segment. As of June 30, 2026, the company’s portfolio comprised 1,559 properties and 377,900 rooms across 83 countries.
According to the company, approximately 89% of adjusted EBITDA in 2025 was generated by asset-light businesses that require limited investment in real estate, including hotel management, franchising, and travel distribution.
Hyatt still owns 17 hotels with an estimated gross value of $2.2–2.5 billion.
The company operates across three main business segments: hotel management and franchising, owned and leased properties, and travel distribution.
The post-earnings decline was driven primarily by weaker net rooms growth guidance and temporary softness in Mexico and the Middle East. Meanwhile, Hyatt’s core hotel management and franchise businesses continued to show resilient underlying momentum.
Strong Q2 2026 Operating Results
Comparable RevPAR, or revenue per available room, increased 5.9% YoY. Average daily rate rose 5.0%, while occupancy improved by 0.6 percentage points.
RevPAR increased:
- 6.7% in the U.S.
- 9.5% in the Americas outside the U.S.
- 7.2% in Greater China
- 10.3% in Asia-Pacific excluding Greater China
- 4.5% in Europe
The weakest performance came from the Middle East and Africa, where RevPAR declined 28.3%.
During the earnings call, management noted that RevPAR in the Middle East alone fell 36%, primarily due to regional conflict.
Total revenue reached $1.829 billion, while adjusted EPS came in at $1.12.
In the all-inclusive resort segment, Net Package RevPAR declined 1.2%, reflecting the impact of a security incident in Mexico as well as reduced airline capacity on certain routes.
Asset-Light Revenue Remains Strong
Revenue from hotel management, franchising, and related services maintained solid growth momentum. In Q2 2026, combined revenue increased 7.8% to $324 million.
Base management fees rose 10.2%, franchise and other fee revenue increased 8.1%, and incentive management fees grew 2.6%.
Travel distribution remained under pressure due to softer demand in Mexico and temporary hotel closures in Jamaica following a hurricane.
Net rooms growth over the past 12 months was 3.9%, or 4.4% excluding Playa-related rooms that were removed from Hyatt’s reported room count in the second half of 2025.
The signed development pipeline reached a record 154,000 rooms, up 10% YoY.
More than half of the hotel openings planned for 2026 are scheduled for Q4, meaning some properties could ultimately be pushed into early 2027.
Full-Year Guidance Remains Resilient
Hyatt’s full-year outlook continues to point to resilient financial performance, although weaker net rooms growth expectations remain an important risk.
The company maintained its guidance for management, franchise, and related fee revenue at $1.305–1.335 billion, implying growth of 9–11%.
Adjusted EBITDA guidance remains at $1.155–1.205 billion, while adjusted free cash flow is expected to reach $580–630 million.
The next earnings report is expected in late October or early November, after the anticipated holding period for this trade.
Until then, the key factors to watch will be resilient U.S. demand, improving conditions in Mexico, and the absence of further delays to hotel openings.
Additional upside could come from the sale of another owned hotel or an acceleration in share repurchases, although neither catalyst is included in the base-case scenario.
Hyatt Trades at a Discount to Hilton
According to FactSet data as of August 4, 2026, Hyatt was trading at approximately 16.7x NTM EV/EBITDA at a share price of around $173.60, compared with approximately 19x for Hilton.
Based on our model, the $190 target price corresponds to an NTM EV/EBITDA multiple of approximately 18.2x.
This means the stock would need only a partial narrowing of its valuation discount to Hilton to reach our target.
Potential Catalysts
Three factors could drive the stock higher: continued strength in management and franchise fee revenue, improving conditions in Mexico, Jamaica, and the Middle East, and additional share repurchases or real estate disposals.
In Q2 2026, Hyatt spent only $12 million on share repurchases, partly due to temporary restrictions related to its Investor Day. However, significant capacity remains under the company’s share repurchase authorization.
That said, the timing of both share repurchases and asset sales remains uncertain.
Technical Setup
The technical setup supports opening a position, although the trade carries elevated risk.
The $174 entry price is below the 50-day moving average of approximately $189.50, but remains above the 200-day moving average of around $166.
The RSI is close to oversold territory.
Support is located in the $164–166 range, while a sustained move above $180 would signal improving momentum and open the way toward the $189–193 area.
The stop loss is set at $162. In the event of a gap down or significant slippage, the actual loss could exceed the planned amount.
Key Risks
The main risk is that temporary headwinds develop into a more prolonged slowdown.
New hotel openings could be delayed again, while the recovery in Cancun and the all-inclusive segment could take longer than expected.
Additional risks include continued weakness in the Middle East, hotel closures in Jamaica, volatility in the travel distribution business, and uncertainty surrounding the timing of real estate disposals.
The relatively low liquidity of Hyatt’s Class A shares could also contribute to sharper-than-usual price swings.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.