
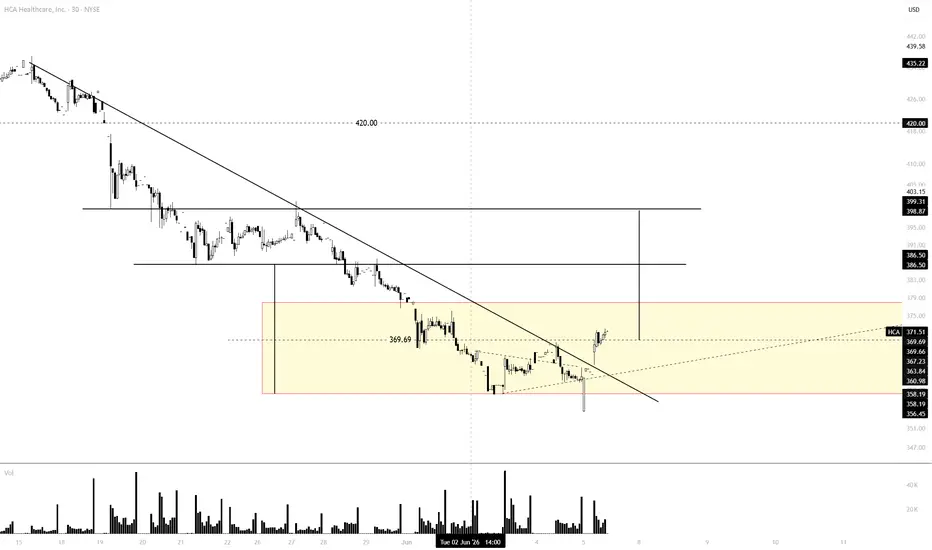
One policy question drives the whole fan: does Congress extend the ACA enhanced premium tax credits? They expired Jan 1, 2026, and HCA guided a $600–900M gross EBITDA hit for the year (mitigated to ~$200–500M net) on a 15–20% drop in exchange volumes, ~80–85% of which becomes uninsured. Crucially the damage is back-end-loaded: CBO has the uninsured count rising ~2.2M in 2026 but ~3.7M in 2027, so the bear rail actually dips through 2027 ($314→$273→$254) before the buyback and volume growth pull it back. The rails are the fork: bull/blue assume extension (the headwind reverses, EBITDA reaccelerates — bull ~$1754, +17%/yr); base/bear assume expiration (base = the mitigated guide path to ~$1126, +12%/yr; bear = full damage + DSH cuts + 2028 provider-tax limits, ~$545, +4%/yr). The reverse-DCF shows how negative the market already is: at $365 the EV (~$129b incl. ~$48b net debt) implies EBITDA shrinking to ~$14.3b by 2035 (purple) from ~$16b today — the stock is priced as if policy permanently impairs earnings power, with zero credit for 2–3% volume growth or the buyback. That is why HCA sits at ~8x EV/EBITDA and ~12.5x earnings, near a 52-wk low, while the Street is at $480–530. The buyback is the quiet engine: ~5–8%/yr share shrink (222M→~146M base by 2035) compounds per-share value even in bear, which is why the downside rail still grinds higher long-term. Devil’s advocate: the bull/blue cases depend on a political act (subsidy extension) that may not come — base it on policy as legislated, not hope; ~3x leverage ($48b net debt) means the buyback is debt-funded, so a higher-rate or weaker-EBITDA world pinches both the buyback and coverage at once; the 2027 cliff is real and the mitigation math is management’s, unproven; DSH cuts and the 2028 provider-tax limits are separate headwinds stacked behind the ACA one; and a recession would hit volumes and uninsured/bad-debt together. Blue-sky “what has to be true”: subsidies extended (or made permanent) AND aging-demographic volume + commercial share gains + outpatient/ASC margin mix — a high-single-digit EBITDA compounder re-rating back toward 10x+ (~$2483).

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.