
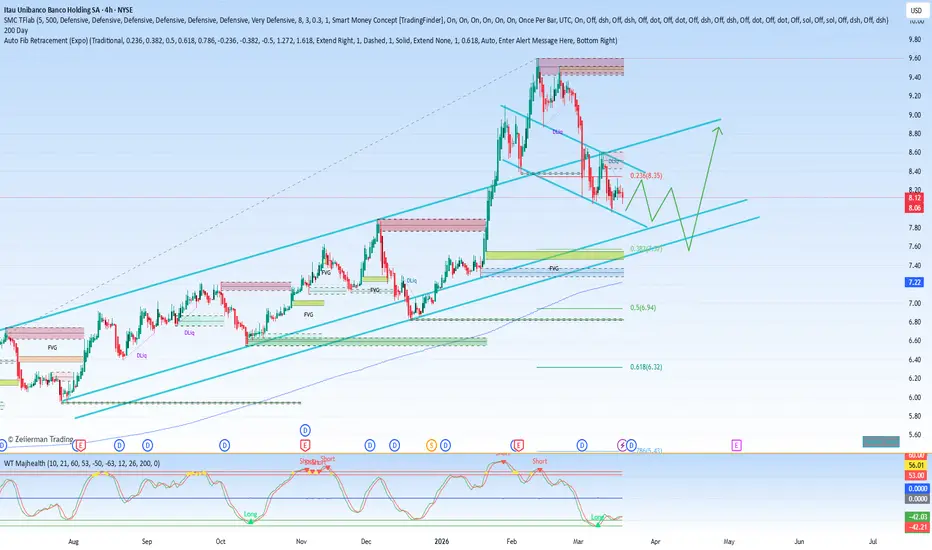
Itaú Unibanco Holding (NYSE: ITUB) has emerged as a standout performer in the Latin American financial sector, posting record-breaking results that underscore the success of its long-term strategic overhaul. The Brazilian banking giant, one of the largest and most influential financial institutions in the region, has solidified its position as a compelling option for investors seeking high-volume, fundamentally sound stocks. Its latest earnings report, released on February 5, 2026 , revealed a series of impressive metrics that highlight the bank's operational strength and the tangible benefits of its multi-year digital transformation journey.
A Deep Dive into the Record-Breaking 2025 Results
The numbers for the full fiscal year 2025 paint a picture of a bank firing on all cylinders. The most striking highlight is the surge in profitability, with Return on Equity (ROE) climbing to 23.4% . This represents a significant leap from the already respectable 19.3% recorded in 2021 and stands as a new record for the institution. This impressive return was fueled by a dramatic 40% expansion in the bank's loan portfolio , demonstrating robust demand across its customer base and successful market penetration strategies.
Complementing the top-line growth was a remarkable improvement in operational efficiency. Itaú's efficiency ratio improved to 38.8% , a best-in-class figure that indicates the bank is generating more revenue per real spent on operations. This improvement is a direct consequence of the bank's heavy and successful investments in digital transformation. By automating processes, migrating customers to digital channels, and modernizing its core technology stack, Itaú has streamlined its cost structure. A particularly striking testament to this technological upgrade is the 99% reduction in technology-related incidents , pointing to a more stable, reliable, and secure platform for both customers and employees.
Navigating Headwinds: Margin Pressure and Asset Quality Concerns
Despite the overwhelmingly positive results, the report was not without its challenges, which management addressed transparently. The bank experienced slight compression in its Net Interest Margin (NIM), which dipped to 8.9% . This pressure reflects the intensely competitive landscape in Brazil, where both agile fintechs and established traditional rivals are vying for market share, often putting pressure on lending spreads.
Furthermore, management flagged a specific concern regarding asset quality tied to a particular corporate client. While presented as an isolated issue rather than a systemic trend, it serves as a reminder of the risks inherent in corporate lending and the importance of rigorous credit analysis. The mention of this specific case has led to some investor caution, although it has not derailed the overall positive narrative.
Navigating a Dynamic Macro and Competitive Landscape
Looking ahead, Itaú's leadership team, helmed by its CEO, is acutely aware of the complex environment in which the bank operates. The competitive landscape in Brazil remains "intense," with traditional banks, digital challengers, and new entrants all vying for a piece of the financial services pie. This competition requires constant innovation and a relentless focus on customer experience.
On the macroeconomic front, the bank is preparing for a period of potential volatility. The upcoming 2026 election year in Brazil introduces an element of political and economic uncertainty, as market participants closely watch policy proposals and fiscal signals. Management is strategically positioning the bank to be resilient, whatever the outcome, by maintaining a strong capital base and a flexible balance sheet.
Strategic Pillars: AI, SMEs, and a Fortress Balance Sheet
Despite these near-term headwinds, the CEO's message was one of confident, long-term value creation. The bank's strategy rests on several key pillars. First and foremost is the continued integration of Artificial Intelligence (AI) across its operations. From credit scoring and fraud detection to personalized customer recommendations and operational efficiency, Itaú views AI as a fundamental tool for deepening customer relationships and driving future productivity gains.
Secondly, the bank has identified the Small and Medium Enterprise (SME) segment as a key driver of future profitability. SMEs are often underserved by traditional banks, and Itaú sees a significant opportunity to leverage its data and digital platforms to offer tailored financial products, including credit, cash management, and advisory services, to this vital part of the economy.
Finally, Itaú plans to continue leveraging its competitive funding structure—a result of its massive deposit base and strong market reputation—to maintain and even expand its leadership in key areas like real estate financing. By offering attractive rates funded by low-cost deposits, the bank can defend its substantial market share in this important and stable asset class.
Conclusion: A Latin American Powerhouse in the Digital Age
Itaú Unibanco's record 23.4% ROE is not a one-off achievement but the culmination of years of disciplined strategy, technological investment, and prudent risk management. While it must navigate a competitive landscape, potential margin pressure, and macroeconomic uncertainty, the bank has demonstrated a remarkable ability to adapt and thrive. For investors, ITUB represents a unique combination of scale, profitability, and forward-looking innovation, positioning it as a core holding for those seeking exposure to the growth and transformation of the Brazilian and Latin American financial sectors. The bank continues to provide a comprehensive suite of financial products and services to personal and corporate customers, both domestically and internationally, with a renewed focus on efficiency and customer-centric innovation.
A Deep Dive into the Record-Breaking 2025 Results
The numbers for the full fiscal year 2025 paint a picture of a bank firing on all cylinders. The most striking highlight is the surge in profitability, with Return on Equity (ROE) climbing to 23.4% . This represents a significant leap from the already respectable 19.3% recorded in 2021 and stands as a new record for the institution. This impressive return was fueled by a dramatic 40% expansion in the bank's loan portfolio , demonstrating robust demand across its customer base and successful market penetration strategies.
Complementing the top-line growth was a remarkable improvement in operational efficiency. Itaú's efficiency ratio improved to 38.8% , a best-in-class figure that indicates the bank is generating more revenue per real spent on operations. This improvement is a direct consequence of the bank's heavy and successful investments in digital transformation. By automating processes, migrating customers to digital channels, and modernizing its core technology stack, Itaú has streamlined its cost structure. A particularly striking testament to this technological upgrade is the 99% reduction in technology-related incidents , pointing to a more stable, reliable, and secure platform for both customers and employees.
Navigating Headwinds: Margin Pressure and Asset Quality Concerns
Despite the overwhelmingly positive results, the report was not without its challenges, which management addressed transparently. The bank experienced slight compression in its Net Interest Margin (NIM), which dipped to 8.9% . This pressure reflects the intensely competitive landscape in Brazil, where both agile fintechs and established traditional rivals are vying for market share, often putting pressure on lending spreads.
Furthermore, management flagged a specific concern regarding asset quality tied to a particular corporate client. While presented as an isolated issue rather than a systemic trend, it serves as a reminder of the risks inherent in corporate lending and the importance of rigorous credit analysis. The mention of this specific case has led to some investor caution, although it has not derailed the overall positive narrative.
Navigating a Dynamic Macro and Competitive Landscape
Looking ahead, Itaú's leadership team, helmed by its CEO, is acutely aware of the complex environment in which the bank operates. The competitive landscape in Brazil remains "intense," with traditional banks, digital challengers, and new entrants all vying for a piece of the financial services pie. This competition requires constant innovation and a relentless focus on customer experience.
On the macroeconomic front, the bank is preparing for a period of potential volatility. The upcoming 2026 election year in Brazil introduces an element of political and economic uncertainty, as market participants closely watch policy proposals and fiscal signals. Management is strategically positioning the bank to be resilient, whatever the outcome, by maintaining a strong capital base and a flexible balance sheet.
Strategic Pillars: AI, SMEs, and a Fortress Balance Sheet
Despite these near-term headwinds, the CEO's message was one of confident, long-term value creation. The bank's strategy rests on several key pillars. First and foremost is the continued integration of Artificial Intelligence (AI) across its operations. From credit scoring and fraud detection to personalized customer recommendations and operational efficiency, Itaú views AI as a fundamental tool for deepening customer relationships and driving future productivity gains.
Secondly, the bank has identified the Small and Medium Enterprise (SME) segment as a key driver of future profitability. SMEs are often underserved by traditional banks, and Itaú sees a significant opportunity to leverage its data and digital platforms to offer tailored financial products, including credit, cash management, and advisory services, to this vital part of the economy.
Finally, Itaú plans to continue leveraging its competitive funding structure—a result of its massive deposit base and strong market reputation—to maintain and even expand its leadership in key areas like real estate financing. By offering attractive rates funded by low-cost deposits, the bank can defend its substantial market share in this important and stable asset class.
Conclusion: A Latin American Powerhouse in the Digital Age
Itaú Unibanco's record 23.4% ROE is not a one-off achievement but the culmination of years of disciplined strategy, technological investment, and prudent risk management. While it must navigate a competitive landscape, potential margin pressure, and macroeconomic uncertainty, the bank has demonstrated a remarkable ability to adapt and thrive. For investors, ITUB represents a unique combination of scale, profitability, and forward-looking innovation, positioning it as a core holding for those seeking exposure to the growth and transformation of the Brazilian and Latin American financial sectors. The bank continues to provide a comprehensive suite of financial products and services to personal and corporate customers, both domestically and internationally, with a renewed focus on efficiency and customer-centric innovation.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.