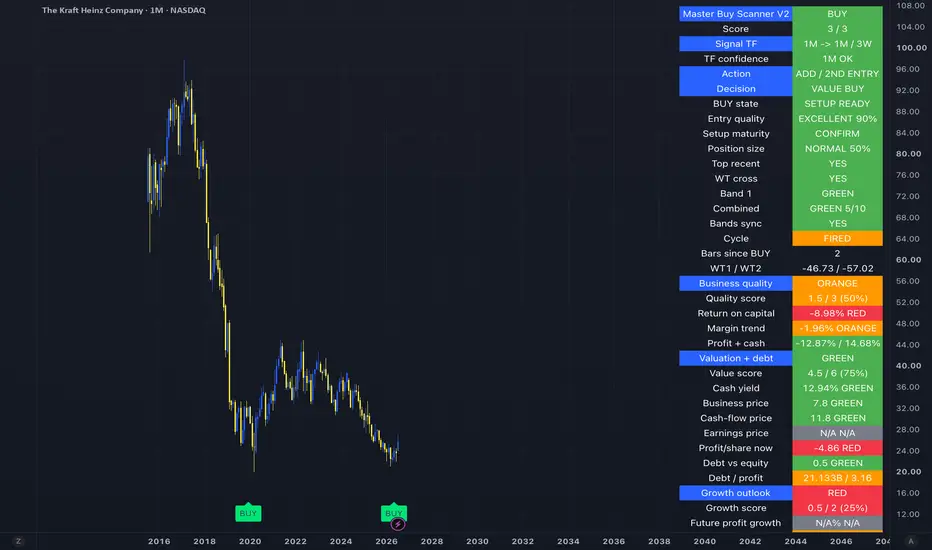
Kraft Heinz ( KHC) has been one of the worst long-term performers in consumer staples.
The stock has collapsed from almost $100 in 2017 to approximately $25 today. Sales are struggling, margins are falling, billions have been written off—and management has paused its proposed corporate separation.
So why has my Master Buy Scanner V2 just generated a 3/3 BUY signal?
Because this is not a QUALITY BUY.
It is a VALUE BUY.
That distinction is crucial.
THE SIGNAL
The monthly scanner currently shows:
• Overall signal: BUY — 3/3
• Action: ADD / SECOND ENTRY
• Decision: VALUE BUY
• Buy state: SETUP READY
• Entry quality: EXCELLENT — 90%
• Setup maturity: CONFIRM
• Model position size: NORMAL — 50%
• Technical cycle: FIRED
• Bars since BUY: 2
The technical setup has improved sharply—but the scanner is not pretending that Kraft Heinz has suddenly become a high-growth compounder.
Instead, it has identified a deeply discounted, cash-generative business where pessimism may already be reflected in the price.
WHY THIS SIGNAL IS DIFFERENT
Many stock scanners generate a generic “BUY” without explaining the type of opportunity.
Master Buy Scanner V2 separates the thesis into four layers:
• Technical timing
• Business quality
• Valuation and debt
• Growth outlook
For KHC, the conclusion is clear:
• Technical setup: BULLISH
• Valuation: ATTRACTIVE
• Business quality: MIXED
• Growth outlook: WEAK
This is precisely why the final decision is VALUE BUY—not QUALITY BUY or GROWTH BUY.
THE VALUE CASE
The scanner gives Kraft Heinz a 4.5/6 valuation score:
• Cash yield: 12.94%
• Business-price multiple: 7.8x
• Cash-flow multiple: 11.8x
• Debt-to-equity: 0.50
• Entry quality: 90%
The normal earnings multiple is unavailable because reported profits were distorted by enormous non-cash impairment charges.
Kraft Heinz recorded $9.3 billion of impairments in 2025, contributing to a full-year GAAP loss of $4.7 billion. This explains the scanner’s negative reported profit-per-share figure.
However, impairments do not necessarily mean cash disappeared during the year.
Kraft Heinz still generated:
• $4.5 billion of operating cash flow in 2025
• $3.7 billion of free cash flow
• $2.3 billion returned to shareholders
• $800 million of free cash flow in Q1 2026
That difference between terrible reported earnings and strong underlying cash generation is the foundation of the value thesis.
THE 6.2% DIVIDEND
Kraft Heinz currently pays a quarterly dividend of $0.40 per share.
That equals $1.60 annually—or an indicated yield of approximately 6.2% at a $25.67 share price.
The dividend is attractive, but it is not guaranteed.
With approximately $21 billion of debt, declining adjusted operating profit and substantial turnaround investment, dividend sustainability depends on continued cash generation.
The yield should therefore be treated as compensation for risk—not as free income.
THE FUNDAMENTALS ARE STILL WEAK
First-quarter 2026 results showed some stabilization:
• Net sales: $6.05 billion, up 0.8%
• Organic sales: down 0.4%
• Gross profit: $2.22 billion, up 7.5%
• Operating income: $1.15 billion, down 4.3%
• GAAP EPS: $0.67, up 13.6%
• Free cash flow: $800 million, up 58.9%
But the adjusted figures reveal the continuing pressure:
• Adjusted operating income: down 11.8%
• Adjusted EPS: $0.58, down 6.5%
• Volume and mix: down 1.2%
• North American sales: down 0.7%
Management expects 2026 organic sales to decline between 1.5% and 3.5%, with constant-currency adjusted operating income falling between 14% and 18%.
This is not yet a fundamental turnaround.
THE SCANNER’S WARNING SIGNS
Business quality is only ORANGE:
• Quality score: 1.5/3 — 50%
• Return on capital: -8.98% — RED
• Margin trend: -1.96% — ORANGE
• Reported profitability: RED
• Cash generation: GREEN
Growth is even weaker:
• Growth score: 0.5/2 — 25%
• Growth outlook: RED
• Future profit growth: Not available
The scanner is effectively saying:
“The stock may be cheap enough to buy—but the company has not yet proven that it can grow again.”
THE PAUSED BREAKUP
Kraft Heinz announced a plan in 2025 to separate into two businesses:
• A global Taste Elevation company containing Heinz, Philadelphia and Kraft Mac & Cheese
• A North American grocery company containing Oscar Mayer, Kraft Singles and Lunchables
The separation was initially expected during the second half of 2026.
However, new CEO Steve Cahillane paused the process in February to focus resources on restoring profitable growth.
Instead, management is investing an additional $600 million across:
• Marketing
• Sales
• Research and development
• Product improvements
• Selected pricing initiatives
Pausing the breakup removes a potential short-term catalyst—but it may be the correct decision if management can repair the business before attempting another major restructuring.
THE TECHNICAL SETUP
KHC recently tested a long-term support zone near $22 before rebounding strongly.
Key levels I am watching:
• $24–25: immediate support and second-entry area
• $21–22: major structural support
• $27–28: first confirmation and breakout zone
• $30–32: important resistance
• $35–36: major long-term recovery target
The scanner’s technical cycle has fired, and the latest monthly candle is constructive.
A confirmed move above $27–28 would strengthen the bottoming thesis. A sustained loss of $21–22 would suggest that the market expects another deterioration in earnings or the dividend.
THE BULL CASE
• Strong free-cash-flow generation
• Approximately 6.2% indicated dividend yield
• Attractive cash-flow valuation
• Globally recognized brands
• Improving market-share trends in Taste Elevation
• Emerging Markets organic sales grew 3.8% in Q1
• $600 million reinvestment could restore brand momentum
• Management is beginning to reduce near-term debt
• Technical cycle has fired after extreme pessimism
THE BEAR CASE
• Organic sales continue to decline
• Volume remains negative
• Adjusted operating profit is falling rapidly
• 2026 guidance implies further deterioration
• Private-label competition is increasing
• Consumers remain price-sensitive
• Debt remains substantial
• The proposed breakup has been paused
• Billions of dollars of impairments show that prior expectations were far too optimistic
• The dividend could eventually become part of the turnaround discussion
MY CURRENT PLAN
I would treat KHC as a measured value position—not as a high-conviction compounder.
My framework would be:
• Maintain or consider a partial position while $24–25 holds
• Add only after confirmation above $27–28
• Increase conviction if organic volumes and margins stabilize
• Reassess below $22
• Monitor the dividend, debt reduction and management’s $600 million reinvestment closely
Second-quarter results on August 5 will be an important test of the emerging recovery thesis.
TRY THE SCANNER
The distinction between VALUE BUY, QUALITY BUY, GROWTH WATCH and TACTICAL setups is one of the key features of Master Buy Scanner V2.
It does not simply tell you that a stock is “cheap.” It shows whether the opportunity is supported by quality, growth, valuation and technical timing.
Add it to your own TradingView charts here:

Run it on your watchlist and post the next ticker you want me to analyze in the comments.
THE QUESTION
At approximately $25, what matters most?
A — The 6.2% dividend and strong cash flow
B — Wait for confirmation above $28
C — Avoid because declining volumes make this a value trap
Comment A, B or C—and share your Kraft Heinz thesis.
KHC) has been one of the worst long-term performers in consumer staples.The stock has collapsed from almost $100 in 2017 to approximately $25 today. Sales are struggling, margins are falling, billions have been written off—and management has paused its proposed corporate separation.
So why has my Master Buy Scanner V2 just generated a 3/3 BUY signal?
Because this is not a QUALITY BUY.
It is a VALUE BUY.
That distinction is crucial.
THE SIGNAL
The monthly scanner currently shows:
• Overall signal: BUY — 3/3
• Action: ADD / SECOND ENTRY
• Decision: VALUE BUY
• Buy state: SETUP READY
• Entry quality: EXCELLENT — 90%
• Setup maturity: CONFIRM
• Model position size: NORMAL — 50%
• Technical cycle: FIRED
• Bars since BUY: 2
The technical setup has improved sharply—but the scanner is not pretending that Kraft Heinz has suddenly become a high-growth compounder.
Instead, it has identified a deeply discounted, cash-generative business where pessimism may already be reflected in the price.
WHY THIS SIGNAL IS DIFFERENT
Many stock scanners generate a generic “BUY” without explaining the type of opportunity.
Master Buy Scanner V2 separates the thesis into four layers:
• Technical timing
• Business quality
• Valuation and debt
• Growth outlook
For KHC, the conclusion is clear:
• Technical setup: BULLISH
• Valuation: ATTRACTIVE
• Business quality: MIXED
• Growth outlook: WEAK
This is precisely why the final decision is VALUE BUY—not QUALITY BUY or GROWTH BUY.
THE VALUE CASE
The scanner gives Kraft Heinz a 4.5/6 valuation score:
• Cash yield: 12.94%
• Business-price multiple: 7.8x
• Cash-flow multiple: 11.8x
• Debt-to-equity: 0.50
• Entry quality: 90%
The normal earnings multiple is unavailable because reported profits were distorted by enormous non-cash impairment charges.
Kraft Heinz recorded $9.3 billion of impairments in 2025, contributing to a full-year GAAP loss of $4.7 billion. This explains the scanner’s negative reported profit-per-share figure.
However, impairments do not necessarily mean cash disappeared during the year.
Kraft Heinz still generated:
• $4.5 billion of operating cash flow in 2025
• $3.7 billion of free cash flow
• $2.3 billion returned to shareholders
• $800 million of free cash flow in Q1 2026
That difference between terrible reported earnings and strong underlying cash generation is the foundation of the value thesis.
THE 6.2% DIVIDEND
Kraft Heinz currently pays a quarterly dividend of $0.40 per share.
That equals $1.60 annually—or an indicated yield of approximately 6.2% at a $25.67 share price.
The dividend is attractive, but it is not guaranteed.
With approximately $21 billion of debt, declining adjusted operating profit and substantial turnaround investment, dividend sustainability depends on continued cash generation.
The yield should therefore be treated as compensation for risk—not as free income.
THE FUNDAMENTALS ARE STILL WEAK
First-quarter 2026 results showed some stabilization:
• Net sales: $6.05 billion, up 0.8%
• Organic sales: down 0.4%
• Gross profit: $2.22 billion, up 7.5%
• Operating income: $1.15 billion, down 4.3%
• GAAP EPS: $0.67, up 13.6%
• Free cash flow: $800 million, up 58.9%
But the adjusted figures reveal the continuing pressure:
• Adjusted operating income: down 11.8%
• Adjusted EPS: $0.58, down 6.5%
• Volume and mix: down 1.2%
• North American sales: down 0.7%
Management expects 2026 organic sales to decline between 1.5% and 3.5%, with constant-currency adjusted operating income falling between 14% and 18%.
This is not yet a fundamental turnaround.
THE SCANNER’S WARNING SIGNS
Business quality is only ORANGE:
• Quality score: 1.5/3 — 50%
• Return on capital: -8.98% — RED
• Margin trend: -1.96% — ORANGE
• Reported profitability: RED
• Cash generation: GREEN
Growth is even weaker:
• Growth score: 0.5/2 — 25%
• Growth outlook: RED
• Future profit growth: Not available
The scanner is effectively saying:
“The stock may be cheap enough to buy—but the company has not yet proven that it can grow again.”
THE PAUSED BREAKUP
Kraft Heinz announced a plan in 2025 to separate into two businesses:
• A global Taste Elevation company containing Heinz, Philadelphia and Kraft Mac & Cheese
• A North American grocery company containing Oscar Mayer, Kraft Singles and Lunchables
The separation was initially expected during the second half of 2026.
However, new CEO Steve Cahillane paused the process in February to focus resources on restoring profitable growth.
Instead, management is investing an additional $600 million across:
• Marketing
• Sales
• Research and development
• Product improvements
• Selected pricing initiatives
Pausing the breakup removes a potential short-term catalyst—but it may be the correct decision if management can repair the business before attempting another major restructuring.
THE TECHNICAL SETUP
KHC recently tested a long-term support zone near $22 before rebounding strongly.
Key levels I am watching:
• $24–25: immediate support and second-entry area
• $21–22: major structural support
• $27–28: first confirmation and breakout zone
• $30–32: important resistance
• $35–36: major long-term recovery target
The scanner’s technical cycle has fired, and the latest monthly candle is constructive.
A confirmed move above $27–28 would strengthen the bottoming thesis. A sustained loss of $21–22 would suggest that the market expects another deterioration in earnings or the dividend.
THE BULL CASE
• Strong free-cash-flow generation
• Approximately 6.2% indicated dividend yield
• Attractive cash-flow valuation
• Globally recognized brands
• Improving market-share trends in Taste Elevation
• Emerging Markets organic sales grew 3.8% in Q1
• $600 million reinvestment could restore brand momentum
• Management is beginning to reduce near-term debt
• Technical cycle has fired after extreme pessimism
THE BEAR CASE
• Organic sales continue to decline
• Volume remains negative
• Adjusted operating profit is falling rapidly
• 2026 guidance implies further deterioration
• Private-label competition is increasing
• Consumers remain price-sensitive
• Debt remains substantial
• The proposed breakup has been paused
• Billions of dollars of impairments show that prior expectations were far too optimistic
• The dividend could eventually become part of the turnaround discussion
MY CURRENT PLAN
I would treat KHC as a measured value position—not as a high-conviction compounder.
My framework would be:
• Maintain or consider a partial position while $24–25 holds
• Add only after confirmation above $27–28
• Increase conviction if organic volumes and margins stabilize
• Reassess below $22
• Monitor the dividend, debt reduction and management’s $600 million reinvestment closely
Second-quarter results on August 5 will be an important test of the emerging recovery thesis.
TRY THE SCANNER
The distinction between VALUE BUY, QUALITY BUY, GROWTH WATCH and TACTICAL setups is one of the key features of Master Buy Scanner V2.
It does not simply tell you that a stock is “cheap.” It shows whether the opportunity is supported by quality, growth, valuation and technical timing.
Add it to your own TradingView charts here:
Run it on your watchlist and post the next ticker you want me to analyze in the comments.
THE QUESTION
At approximately $25, what matters most?
A — The 6.2% dividend and strong cash flow
B — Wait for confirmation above $28
C — Avoid because declining volumes make this a value trap
Comment A, B or C—and share your Kraft Heinz thesis.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.