
Synthesized Investment Thesis for Medtronic (MDT): A Defensive Dividend Aristocrat Poised for Strategic Catalysts
Medtronic's recent market outperformance amidst broader volatility highlights its status as a defensive, high-quality holding within the healthcare sector. The stock represents a compelling blend of stability, income, and exposure to long-term growth catalysts like surgical robotics and AI, albeit at a valuation that demands patience. Its appeal is particularly strong for investors seeking diversification, reliable income, and strategic optionality in a single large-cap name.
Part 1: Recent Performance & Upcoming Catalyst (The "What")
Relative Strength in a Weak Market: MDT's +1.94% gain on a day when major indices declined, coupled with its +5.14% rise over the past month against a falling medical sector, signals strong relative strength. This suggests investors are treating the stock as a safe-haven or "flight to quality" asset during market uncertainty, a testament to its resilient business model.
The Near-Term Focus: Q3 FY2026 Earnings (Feb. 17, 2026): All eyes are on the upcoming report. The market anticipates a mixed picture: a slight -4.32% decline in EPS to $1.33, overshadowed by a healthy +7.29% revenue increase to $8.9 billion. This dynamic suggests potential investments or margin pressures in the short term, but underlying top-line growth. The full-year estimates (+2.73% EPS, +7.46% Revenue) paint a more consistent picture of steady, mid-single-digit growth.
Part 2: Core Investment Proposition (The "Why")
Unmatched Diversification & Scale: As one of the world's largest medical device companies, Medtronic's portfolio spans cardiovascular, neuroscience, medical-surgical, and diabetes. This diversification provides natural hedging, ensuring that weakness in one segment (e.g., upcoming diabetes spin-off) can be offset by strength in others (e.g., robotics, structural heart).
The Dividend Aristocrat Advantage: With 48 consecutive years of dividend increases and a current yield of ~2.8%, MDT is a cornerstone for dividend growth investors. This yield is more than double that of the S&P 500, offering a tangible income stream while waiting for capital appreciation. The commitment to the dividend underscores financial discipline and a shareholder-friendly capital allocation policy.
Strategic Catalysts on the Horizon:
Diabetes Spin-Off: The planned separation of the diabetes business is a pivotal corporate restructuring catalyst. It aims to unlock value by allowing both the core Medtronic and the new diabetes entity to focus on their distinct markets, potentially improving growth profiles and operational efficiency for each.
The Hugo Robotics & AI Opportunity: While playing catch-up to Intuitive Surgical's da Vinci, Medtronic's Hugo Robotic-Assisted Surgery (RAS) system represents a massive long-term growth vector. The commentary that "all the AI opportunities for Intuitive... also exist for Medtronic's Hugo system" is key. Investing in MDT provides a lower-cost entry point into the surgical AI/robotics megatrend with significant global rollout potential.
Part 3: Valuation & Technical Perspective (The "When & Where")
Valuation Context: A forward P/E of ~27x is not cheap in absolute terms, but it is argued to be "far more reasonable" than the hyper-growth multiples of pure-play robotics peers. This valuation reflects MDT's mature, cash-generative businesses and is partially supported by its dividend yield. It is a premium paid for stability and optionality.
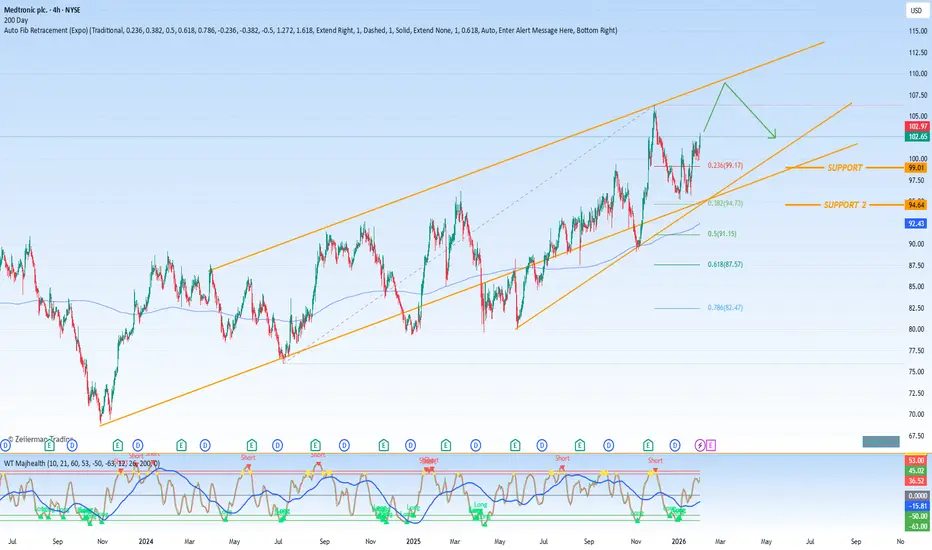
Technical Support Zone: The identified Fibonacci support zone between $99.17 (0.236) and $94.73 (0.382) provides a crucial framework for risk management. This zone represents a likely area of accumulation or buying interest on any pullback. For new investors, this zone offers a more attractive risk-adjusted entry point than chasing strength after a 5% monthly rally.
Integrated Final Judgment & Strategic Implications
Medtronic is not a speculative growth stock; it is a " compounder " with embedded optionality.
For Income & Defense-Focused Investors: MDT is a strong "Buy" or "Hold." Its dividend aristocrat status, sector defensiveness, and diversified cash flows make it a core healthcare holding for portfolios prioritizing capital preservation and growing income.
For Growth-Oriented Investors Seeking Value: MDT is a "Watchlist Buy on Weakness." The compelling story lies in the strategic catalysts (diabetes spin-off, Hugo rollout, AI integration). The optimal strategy may be to initiate or add to a position on a pullback into the $94-$99 support zone, thereby improving the margin of safety while positioning for these longer-term drivers.
Key Risks to Monitor: Execution risks with the Hugo platform rollout, integration challenges post-diabetes spin-off, and the potential for continued margin pressure in a competitive environment.
Conclusion:
Medtronic's recent strength is a microcosm of its broader appeal. It offers a unique triad: defensive diversification, a reliable and growing dividend, and strategic growth optionality in robotics/AI. While its valuation requires a long-term horizon, investors are essentially paying for a "steady-eddy" business with several free options on transformative growth. The upcoming earnings report will be a key test of its near-term operational momentum, but the long-term thesis remains intact for patient investors, especially if entry points align with the identified technical support.
Medtronic's recent market outperformance amidst broader volatility highlights its status as a defensive, high-quality holding within the healthcare sector. The stock represents a compelling blend of stability, income, and exposure to long-term growth catalysts like surgical robotics and AI, albeit at a valuation that demands patience. Its appeal is particularly strong for investors seeking diversification, reliable income, and strategic optionality in a single large-cap name.
Part 1: Recent Performance & Upcoming Catalyst (The "What")
Relative Strength in a Weak Market: MDT's +1.94% gain on a day when major indices declined, coupled with its +5.14% rise over the past month against a falling medical sector, signals strong relative strength. This suggests investors are treating the stock as a safe-haven or "flight to quality" asset during market uncertainty, a testament to its resilient business model.
The Near-Term Focus: Q3 FY2026 Earnings (Feb. 17, 2026): All eyes are on the upcoming report. The market anticipates a mixed picture: a slight -4.32% decline in EPS to $1.33, overshadowed by a healthy +7.29% revenue increase to $8.9 billion. This dynamic suggests potential investments or margin pressures in the short term, but underlying top-line growth. The full-year estimates (+2.73% EPS, +7.46% Revenue) paint a more consistent picture of steady, mid-single-digit growth.
Part 2: Core Investment Proposition (The "Why")
Unmatched Diversification & Scale: As one of the world's largest medical device companies, Medtronic's portfolio spans cardiovascular, neuroscience, medical-surgical, and diabetes. This diversification provides natural hedging, ensuring that weakness in one segment (e.g., upcoming diabetes spin-off) can be offset by strength in others (e.g., robotics, structural heart).
The Dividend Aristocrat Advantage: With 48 consecutive years of dividend increases and a current yield of ~2.8%, MDT is a cornerstone for dividend growth investors. This yield is more than double that of the S&P 500, offering a tangible income stream while waiting for capital appreciation. The commitment to the dividend underscores financial discipline and a shareholder-friendly capital allocation policy.
Strategic Catalysts on the Horizon:
Diabetes Spin-Off: The planned separation of the diabetes business is a pivotal corporate restructuring catalyst. It aims to unlock value by allowing both the core Medtronic and the new diabetes entity to focus on their distinct markets, potentially improving growth profiles and operational efficiency for each.
The Hugo Robotics & AI Opportunity: While playing catch-up to Intuitive Surgical's da Vinci, Medtronic's Hugo Robotic-Assisted Surgery (RAS) system represents a massive long-term growth vector. The commentary that "all the AI opportunities for Intuitive... also exist for Medtronic's Hugo system" is key. Investing in MDT provides a lower-cost entry point into the surgical AI/robotics megatrend with significant global rollout potential.
Part 3: Valuation & Technical Perspective (The "When & Where")
Valuation Context: A forward P/E of ~27x is not cheap in absolute terms, but it is argued to be "far more reasonable" than the hyper-growth multiples of pure-play robotics peers. This valuation reflects MDT's mature, cash-generative businesses and is partially supported by its dividend yield. It is a premium paid for stability and optionality.
Technical Support Zone: The identified Fibonacci support zone between $99.17 (0.236) and $94.73 (0.382) provides a crucial framework for risk management. This zone represents a likely area of accumulation or buying interest on any pullback. For new investors, this zone offers a more attractive risk-adjusted entry point than chasing strength after a 5% monthly rally.
Integrated Final Judgment & Strategic Implications
Medtronic is not a speculative growth stock; it is a " compounder " with embedded optionality.
For Income & Defense-Focused Investors: MDT is a strong "Buy" or "Hold." Its dividend aristocrat status, sector defensiveness, and diversified cash flows make it a core healthcare holding for portfolios prioritizing capital preservation and growing income.
For Growth-Oriented Investors Seeking Value: MDT is a "Watchlist Buy on Weakness." The compelling story lies in the strategic catalysts (diabetes spin-off, Hugo rollout, AI integration). The optimal strategy may be to initiate or add to a position on a pullback into the $94-$99 support zone, thereby improving the margin of safety while positioning for these longer-term drivers.
Key Risks to Monitor: Execution risks with the Hugo platform rollout, integration challenges post-diabetes spin-off, and the potential for continued margin pressure in a competitive environment.
Conclusion:
Medtronic's recent strength is a microcosm of its broader appeal. It offers a unique triad: defensive diversification, a reliable and growing dividend, and strategic growth optionality in robotics/AI. While its valuation requires a long-term horizon, investors are essentially paying for a "steady-eddy" business with several free options on transformative growth. The upcoming earnings report will be a key test of its near-term operational momentum, but the long-term thesis remains intact for patient investors, especially if entry points align with the identified technical support.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.