
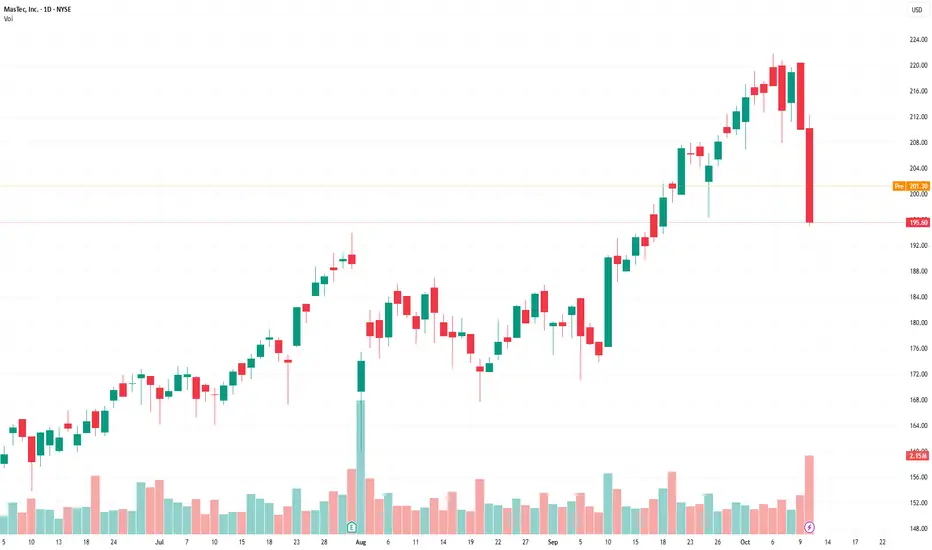
MasTec Inc. (MTZ): Record Backlog and Margin Expansion Support Sustained Growth Outlook
MasTec Inc. (MTZ) is a North American engineering and construction company specializing in the design, construction, maintenance, and modernization of infrastructure assets. Its core areas include telecommunications, energy, utilities, and transportation infrastructure projects. The company executes projects involving the development of wireless and fiber-optic networks, power systems, renewable energy, pipelines, and heavy civil infrastructure — including roads, bridges, and railways. MasTec’s client base comprises leading companies in the telecommunications, energy, and utilities sectors. The company has a broad presence across North America, with headquarters in Coral Gables, Florida, USA.
Investment Highlights
MasTec benefits significantly from the large-scale expansion of telecommunications and data infrastructure in the U.S. Key drivers include the accelerated deployment of fiber-optic networks, the development of wireless technologies, and growing demand from hyperscaler companies for inter–data center connectivity and AI-related infrastructure. Federal broadband development programs also provide a steady flow of projects.
In Q2 2025, the Communications segment backlog rose 13% year over year to a record $5 billion,
reflecting sustained demand for both fiber and wireless solutions. The company maintains active partnerships with AT&T, Verizon, T-Mobile, and technology clients (including Microsoft via a contract with Lumen Technologies), ensuring a diversified order portfolio and a multi-year growth horizon.
MasTec is focused on enhancing profitability through process optimization, execution discipline,
and digitalization of project management. In Q2 2025, the Communications and Power Delivery
segments saw a substantial increase in EBITDA, driven by improved productivity and operating
leverage. Power Delivery and Communications margins improved by 300 bps quarter over quarter, while the Clean Energy segment rose by 120 bps. Management expects further margin expansion in the second half of 2025.
The expanding backlog provides MasTec with a solid base for multi-year revenue growth. As of
June 30, 2025, the 18-month backlog totaled $16.45 billion, up 23% year over year and 4% quarter over quarter. The main growth drivers were the Clean Energy & Infrastructure and Communications segments.
The record order volume led to an upward revision of 2025 guidance:
Revenue: $13.9–14.0 billion
Adjusted EBITDA: $1.13–1.16 billion
Adjusted EPS: $6.23–6.44
The record backlog and high project diversification enhance resilience and reduce cyclical risks, providing a strong foundation for continued growth into 2026.
As of Q2 2025, MasTec’s total liquidity stood at approximately $2 billion, and net leverage was 2.0× EBITDA, which the company plans to reduce in the second half of 2025. It expects operating cash flow of $700–750 million for 2025. In June 2025, the company successfully refinanced its credit facilities, achieving improved terms and extended maturities.
Target price for MTZ: $225
Price at time of analysis: $195.60
Upside potential: 15%
MasTec Inc. (MTZ) is a North American engineering and construction company specializing in the design, construction, maintenance, and modernization of infrastructure assets. Its core areas include telecommunications, energy, utilities, and transportation infrastructure projects. The company executes projects involving the development of wireless and fiber-optic networks, power systems, renewable energy, pipelines, and heavy civil infrastructure — including roads, bridges, and railways. MasTec’s client base comprises leading companies in the telecommunications, energy, and utilities sectors. The company has a broad presence across North America, with headquarters in Coral Gables, Florida, USA.
Investment Highlights
- Expansion of communications and data center infrastructure
MasTec benefits significantly from the large-scale expansion of telecommunications and data infrastructure in the U.S. Key drivers include the accelerated deployment of fiber-optic networks, the development of wireless technologies, and growing demand from hyperscaler companies for inter–data center connectivity and AI-related infrastructure. Federal broadband development programs also provide a steady flow of projects.
In Q2 2025, the Communications segment backlog rose 13% year over year to a record $5 billion,
reflecting sustained demand for both fiber and wireless solutions. The company maintains active partnerships with AT&T, Verizon, T-Mobile, and technology clients (including Microsoft via a contract with Lumen Technologies), ensuring a diversified order portfolio and a multi-year growth horizon.
- Margin improvement through operational efficiency
MasTec is focused on enhancing profitability through process optimization, execution discipline,
and digitalization of project management. In Q2 2025, the Communications and Power Delivery
segments saw a substantial increase in EBITDA, driven by improved productivity and operating
leverage. Power Delivery and Communications margins improved by 300 bps quarter over quarter, while the Clean Energy segment rose by 120 bps. Management expects further margin expansion in the second half of 2025.
- Strong growth and resilience of the order backlog
The expanding backlog provides MasTec with a solid base for multi-year revenue growth. As of
June 30, 2025, the 18-month backlog totaled $16.45 billion, up 23% year over year and 4% quarter over quarter. The main growth drivers were the Clean Energy & Infrastructure and Communications segments.
The record order volume led to an upward revision of 2025 guidance:
Revenue: $13.9–14.0 billion
Adjusted EBITDA: $1.13–1.16 billion
Adjusted EPS: $6.23–6.44
The record backlog and high project diversification enhance resilience and reduce cyclical risks, providing a strong foundation for continued growth into 2026.
- Financial stability and discipline
As of Q2 2025, MasTec’s total liquidity stood at approximately $2 billion, and net leverage was 2.0× EBITDA, which the company plans to reduce in the second half of 2025. It expects operating cash flow of $700–750 million for 2025. In June 2025, the company successfully refinanced its credit facilities, achieving improved terms and extended maturities.
Target price for MTZ: $225
Price at time of analysis: $195.60
Upside potential: 15%

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.