Micron’s Memory Business Is Booming. Why the Stock Stayed Flat.
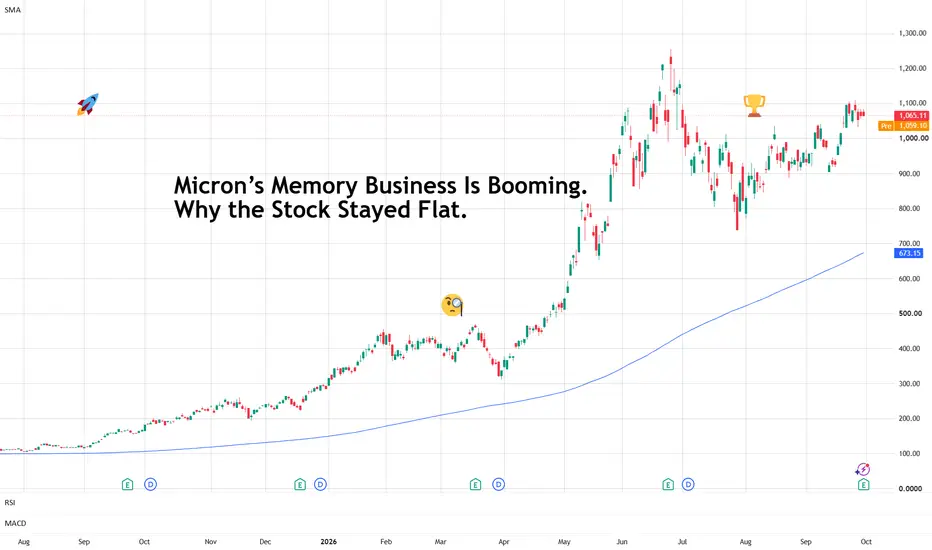
Micron  MU just had a ridiculous quarter. Stock didn’t care.
Micron'sMU memory business is booming. Revenue is exploding, margins have reached levels that would make many software companies jealous and customers are asking for more chips than the company can produce.
MicronMU reported fiscal fourth-quarter revenue of $54.2 billion, up from $11.32 billion a year earlier. Adjusted earnings reached $33.42 per share, while gross margin climbed to a whopping 87%. Operating cash flow came in just shy of $44 billion.
The outlook wasn't exactly disappointing either. Micron expects roughly $61.5 billion in revenue this quarter, comfortably ahead of Wall Street estimates.
YetMU shares were roughly flat after hours. What gives?
🤖 AI Has Developed a Memory Problem
The answer starts with why Micron's numbers have become so enormous. Artificial intelligence needs GPUs, but GPUs need enormous amounts of fast memory to feed them data. That's where high-bandwidth memory, or HBM, comes in.
Think of the GPU as an extremely powerful engine. HBM is the fuel system keeping enough data flowing into it. Build a faster engine without supplying enough fuel and much of that horsepower goes unused.
The AI infrastructure boom has transformed memory from a relatively overlooked component into one of the industry's biggest bottlenecks.
Micron says customer orders are now exceeding available capacity, while long-term supply agreements have grown from $22 billion in June to $32 billion.
Much of its 2027 production is already committed and management expects tight supply conditions to persist through fiscal 2027 and 2028. That's a wonderful problem to have.
🚀MU Is Already on the Moon
Before Wednesday's earnings, Micron shares had climbed roughly 240% in 2026 and more than 540% over the trailing 12 months. That changes how traders interpret the earnings reaction.
After such a powerful rally, the hurdle gets considerably higher.
🏗️ Now Comes the Spending
There is another complication. Micron spent $27.4 billion on capital expenditure during fiscal 2026, and investment is climbing further as the company races to expand production.
That's necessary when customers want everything you can manufacture. But memory is famously cyclical.
Micron, Samsung and SK Hynix are all responding to today's shortages by investing in tomorrow's capacity. Eventually, more factories and equipment mean more supply. If supply catches demand, today's extraordinary pricing power can weaken remarkably quickly.
That said, the earnings season of Q3 just wrapped up and now it’s time to enter into the final stretch of 2026. The fourth quarter earnings season is right around the corner. Watch the Earnings calendar to stay ahead of the curve.
Off to you: What do you make of Micron's earnings? Are you long or short? Share in the comments!
MU just had a ridiculous quarter. Stock didn’t care.Micron's
MU memory business is booming. Revenue is exploding, margins have reached levels that would make many software companies jealous and customers are asking for more chips than the company can produce.Micron
MU reported fiscal fourth-quarter revenue of $54.2 billion, up from $11.32 billion a year earlier. Adjusted earnings reached $33.42 per share, while gross margin climbed to a whopping 87%. Operating cash flow came in just shy of $44 billion.The outlook wasn't exactly disappointing either. Micron expects roughly $61.5 billion in revenue this quarter, comfortably ahead of Wall Street estimates.
Yet
MU shares were roughly flat after hours. What gives?🤖 AI Has Developed a Memory Problem
The answer starts with why Micron's numbers have become so enormous. Artificial intelligence needs GPUs, but GPUs need enormous amounts of fast memory to feed them data. That's where high-bandwidth memory, or HBM, comes in.
Think of the GPU as an extremely powerful engine. HBM is the fuel system keeping enough data flowing into it. Build a faster engine without supplying enough fuel and much of that horsepower goes unused.
The AI infrastructure boom has transformed memory from a relatively overlooked component into one of the industry's biggest bottlenecks.
Micron says customer orders are now exceeding available capacity, while long-term supply agreements have grown from $22 billion in June to $32 billion.
Much of its 2027 production is already committed and management expects tight supply conditions to persist through fiscal 2027 and 2028. That's a wonderful problem to have.
🚀
MU Is Already on the MoonBefore Wednesday's earnings, Micron shares had climbed roughly 240% in 2026 and more than 540% over the trailing 12 months. That changes how traders interpret the earnings reaction.
After such a powerful rally, the hurdle gets considerably higher.
- Record revenue? Expected.
- Exploding HBM demand? Expected.
- Supply shortages? Expected.
- Better guidance? Also increasingly expected.
🏗️ Now Comes the Spending
There is another complication. Micron spent $27.4 billion on capital expenditure during fiscal 2026, and investment is climbing further as the company races to expand production.
That's necessary when customers want everything you can manufacture. But memory is famously cyclical.
Micron, Samsung and SK Hynix are all responding to today's shortages by investing in tomorrow's capacity. Eventually, more factories and equipment mean more supply. If supply catches demand, today's extraordinary pricing power can weaken remarkably quickly.
That said, the earnings season of Q3 just wrapped up and now it’s time to enter into the final stretch of 2026. The fourth quarter earnings season is right around the corner. Watch the Earnings calendar to stay ahead of the curve.
Off to you: What do you make of Micron's earnings? Are you long or short? Share in the comments!

Share TradingView with a friend:
tradingview.com/share-your-love/
Check out all #tradingviewtips
tradingview.com/ideas/tradingviewtips/?type=education
New Tools and Features:
tradingview.com/blog/en/
tradingview.com/share-your-love/
Check out all #tradingviewtips
tradingview.com/ideas/tradingviewtips/?type=education
New Tools and Features:
tradingview.com/blog/en/
Related publications
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.