
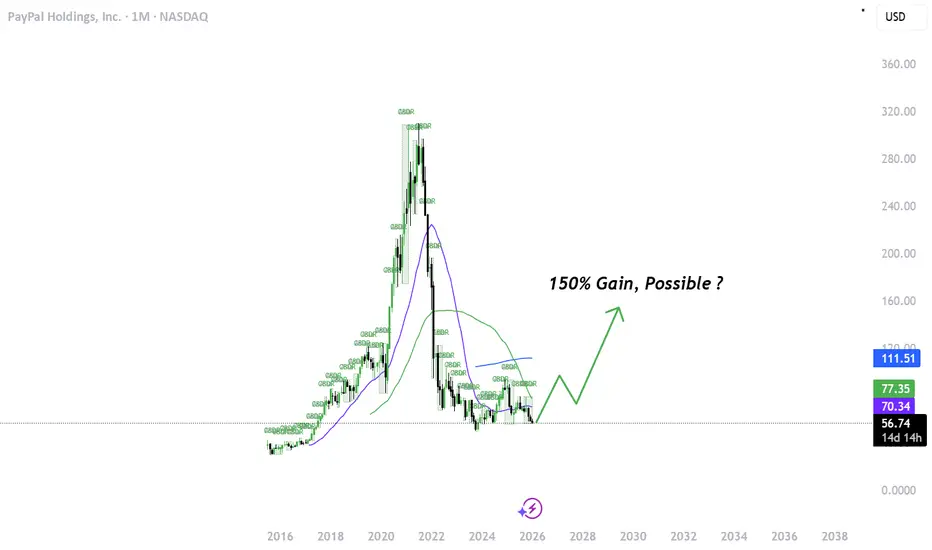
Why PayPal Stock Has Dropped ~80% From Its Highs
PayPal’s share price decline has been driven by several structural and market factors:
1. Growth Slowdown After Pandemic Surge
After booming during the pandemic, PayPal’s revenue growth slowed considerably, more moderate growth rather than rapid expansion. Growth that was double digits slowed to mid-single digits.
2. Loss of eBay Exclusive Payments
PayPal lost eBay as a major payments partner in 2021, a business that had contributed a large share of transaction volume historically.
3. Heavy Competition
PayPal faces strong competition from modern fintechs and big tech players:
-Stripe and Square (Block) in online payments
-Apple Pay & Google Pay in digital wallets/contactless
This has pressured growth and margins.
4. Investor Sentiment and Market Expectations
Even when PayPal beat earnings forecasts, the stock has often fallen, because investors want faster growth and more aggressive new-revenue drivers.
5. Macro and Regulatory Risks
Broader macro pressures and regulatory uncertainty in key markets have added volatility and risk.
The Bullish Case:
PayPal trades at a low forward P/E relative to its history and the market.
Solid Cash Flow & Share Buybacks
The company continues generating strong free cash flow and has committed significant capital to share repurchases and a small dividend, which returns value to shareholders.
Growth in Core Areas
Venmo and branded checkout volumes are growing, Venmo especially shows solid user and revenue expansion (Paypal owns Venmo).
Strategic Initiatives
Management is making bets on:
-embedded/AI-driven commerce
-wallet/crypto integration
-higher-margin branded processing services
These could eventually accelerate growth.
Risks & Cons:
Growth Still Slow
Revenue and transaction volumes are improving but not at the pace investors typically reward in tech.
Competition Remains Intense
Big tech wallets and fintech processors may win share, particularly in mobile and contactless payments.
Potential Further Downside
Analysts and some commentators argue PayPal could decline further if growth falters or execution slows, this risk makes it look like a value trap if the turnaround doesn’t materialize.
Market Sentiment Still Weak
Recent downgrades and neutral analyst ratings reflect caution about the pace of improvement under current leadership
Disclaimer:
This analysis is for informational and educational purposes only and does not constitute financial advice, investment recommendation, or an offer to buy or sell any securities. Asset prices, valuations, and performance metrics are subject to change and may be outdated. Always conduct your own due diligence and consult with a licensed financial advisor before making investment decisions. The information presented may contain inaccuracies and should not be solely relied upon for financial decisions. I am not a licensed financial advisor or professional trader. I am not personally liable for your own losses; this is not financial advice.
PayPal’s share price decline has been driven by several structural and market factors:
1. Growth Slowdown After Pandemic Surge
After booming during the pandemic, PayPal’s revenue growth slowed considerably, more moderate growth rather than rapid expansion. Growth that was double digits slowed to mid-single digits.
2. Loss of eBay Exclusive Payments
PayPal lost eBay as a major payments partner in 2021, a business that had contributed a large share of transaction volume historically.
3. Heavy Competition
PayPal faces strong competition from modern fintechs and big tech players:
-Stripe and Square (Block) in online payments
-Apple Pay & Google Pay in digital wallets/contactless
This has pressured growth and margins.
4. Investor Sentiment and Market Expectations
Even when PayPal beat earnings forecasts, the stock has often fallen, because investors want faster growth and more aggressive new-revenue drivers.
5. Macro and Regulatory Risks
Broader macro pressures and regulatory uncertainty in key markets have added volatility and risk.
The Bullish Case:
PayPal trades at a low forward P/E relative to its history and the market.
Solid Cash Flow & Share Buybacks
The company continues generating strong free cash flow and has committed significant capital to share repurchases and a small dividend, which returns value to shareholders.
Growth in Core Areas
Venmo and branded checkout volumes are growing, Venmo especially shows solid user and revenue expansion (Paypal owns Venmo).
Strategic Initiatives
Management is making bets on:
-embedded/AI-driven commerce
-wallet/crypto integration
-higher-margin branded processing services
These could eventually accelerate growth.
Risks & Cons:
Growth Still Slow
Revenue and transaction volumes are improving but not at the pace investors typically reward in tech.
Competition Remains Intense
Big tech wallets and fintech processors may win share, particularly in mobile and contactless payments.
Potential Further Downside
Analysts and some commentators argue PayPal could decline further if growth falters or execution slows, this risk makes it look like a value trap if the turnaround doesn’t materialize.
Market Sentiment Still Weak
Recent downgrades and neutral analyst ratings reflect caution about the pace of improvement under current leadership
Disclaimer:
This analysis is for informational and educational purposes only and does not constitute financial advice, investment recommendation, or an offer to buy or sell any securities. Asset prices, valuations, and performance metrics are subject to change and may be outdated. Always conduct your own due diligence and consult with a licensed financial advisor before making investment decisions. The information presented may contain inaccuracies and should not be solely relied upon for financial decisions. I am not a licensed financial advisor or professional trader. I am not personally liable for your own losses; this is not financial advice.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.