
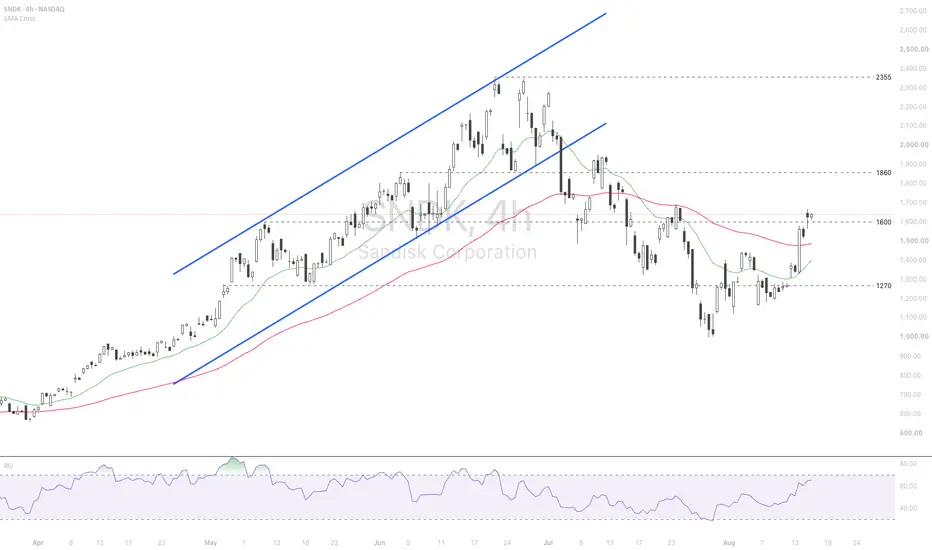
SNDK | 4H Technical Analysis — Aug 17, 2026
SanDisk held its Investor Day, guiding to mid-to-high-teens revenue growth annually through FY2028–2030, with gross margins sustained near 80%. The company announced long-term agreements with 8 customers, 3 of which are US hyperscalers, with committed volumes representing roughly half of FY2027 storage production capacity and two-thirds of FY2028. SanDisk also unveiled its first completed High Bandwidth Flash prototype, with early customer samples targeted for next year. Internal testing against Alibaba's Qwen3 showed HBF GPU 1 unit handling workloads requiring HBM GPU 8 units, with HBF GPU 4 matching HBM GPU 8 output — delivering 8x capex efficiency and 2x GPU efficiency. CTO Alper Ilkbahar stated, "HBF will fundamentally change the economics of AI." First HBF revenue is expected in 2028. SanDisk also committed to returning 100% of free cash flow to shareholders and announced a $15.5B buyback. The stock surged 13.67% intraday, bringing the YTD gain to 543.74%.
SNDK has been in a recovery phase since the July low near 990, after breaking down sharply from the ascending channel that carried price from the April base near 630 to the 2,355 cycle high. The channel breakdown in early July, driven by hyperscaler capex fears, brought price down nearly 60% from the peak before stabilizing at the 1,270 support zone. The current recovery has reclaimed 1,270, 1,400, and now 1,600 on the Investor Day catalyst.
RSI at 65.28 has recovered strongly from oversold lows near 30 seen during the July flush, now approaching elevated territory without yet hitting overbought, suggesting room remains before the next meaningful resistance test.
Key levels to watch:
Resistance: 1,860 / 2,355 (cycle high)
Support: 1,600 / 1,270 / 1,050 (July low)
Bear case: Failure to hold above 1,600 and both EMAs would suggest the move is being faded. A rollover below 1,270 would retest the July low structure and call into question whether the recovery has legs ahead of 2028 HBF revenue materializing.
Bull case: A hold above 1,600 and a clean break above 1860 would confirm the recovery is gaining structural traction. Follow-through above 1,860, with the hyperscaler LTA commitments and HBF efficiency narrative providing a durable multi-year fundamental catalyst.
Bias is cautiously bullish — the Investor Day disclosures represent a significant de-risking of the demand and technology narrative, the 1,270 support held cleanly, and RSI has room to extend. A reclaim and hold above EMA78 and 1,600 would be the confirmation needed for higher conviction.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.