
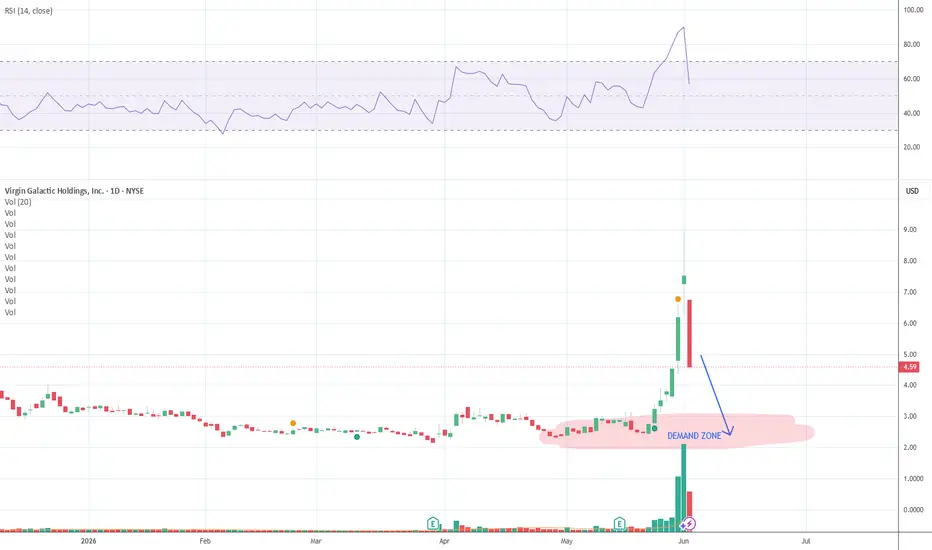
Virgin Galactic is not a normal growth stock. This is a very high-risk speculative company, and I am not interested in chasing it after a vertical move. In fact, I am actually happy to see the recent decline, because the previous move looked like a typical speculative pump: huge volume, aggressive price spike, emotional buying, and then a fast rejection.
For me, that is not a reason to panic. That is exactly the kind of behavior I want to see before even considering an entry. I do not want to buy SPCE when everyone is chasing it. I want to see the price come back into a more reasonable demand zone, where the risk/reward becomes less stupid.
Technically, the chart shows a very sharp move up followed by a strong pullback. The highlighted demand zone is the area I am watching. If the price continues falling toward that zone, I would see it as potentially constructive, not necessarily bearish. The stock needed to cool down. The pump needed to be cleaned out.
But SPCE is not a clean investment. The company has a terrible history.
Virgin Galactic stopped commercial flights because the old VSS Unity vehicle was retired in 2024. Unity was not scalable. It carried only 4 passengers, had low flight frequency, required too much maintenance, and did not generate enough revenue to cover its flight support costs. Management itself admitted that Unity’s operating costs exceeded its modest monthly revenue. So the old business model did not work.
That is why the current thesis is not about Unity.
The entire investment case now depends on Delta Class.
Delta Class is supposed to fix the economic problem. Unlike Unity, which was closer to a hand-built prototype, Delta is designed for higher frequency, faster turnaround, more passengers, and better unit economics. The goal is to move from a prestige demonstration vehicle to something closer to a repeatable commercial operation.
That is the bullish case.
But the bear case is also very serious.
Virgin Galactic is still basically a pre-revenue company. Revenue is almost nonexistent. So yes, cash burn is improving, but it is still huge.
This is the central risk: SPCE must survive long enough to launch Delta commercially.
The market also knows that Virgin Galactic has a long history of delays, broken expectations, overpromising, and poor execution. This is not just normal skepticism. It is earned skepticism.
The company also has a serious credibility problem. In the past, management and Richard Branson presented flights as successful or flawless while important technical issues were allegedly not fully disclosed. Investors are right not to trust the story blindly.
However, there are also important changes.
First, the company is now under much more legal and disclosure pressure. Hiding major technical problems would be much more dangerous.
Second, the Delta milestones are now specific and verifiable. This is not just “soon” or “next year.” The current roadmap is clear:
Ground testing in 2026.
Flight testing targeted in 2026.
Commercial Delta flights targeted for Q4 2026.
Second Delta ship targeted around late 2026 or early 2027.
Higher flight cadence targeted after that.
This is exactly why the next few quarters matter so much.
The company does not need investors to believe a 10-year fantasy today. It needs to prove step by step that Delta is real, testable, flyable, and economically better than Unity.
That is the key point:
One Delta ship is not enough.
The model needs cadence.
Cadence needs multiple vehicles.
Multiple vehicles need capital.
Capital requires either investor confidence or dilution.
This is why SPCE is extremely risky.
But unlike many speculative bankrupt-looking names, SPCE does have a real possible economic path. It is not guaranteed, but it is understandable.
If Delta works, the company can move from almost no revenue to a real commercial phase. If Delta does not work, or if testing is delayed, or if cash runs out before meaningful revenue begins, shareholders may face more dilution, restructuring risk, or worse.
From a chart perspective, I am not interested in buying the top of a hype candle. The recent move looked too emotional. I prefer the pullback. A drop back toward the demand zone could offer a better speculative setup, especially if the company continues to confirm Delta progress and cash burn does not accelerate.
My current view:
SPCE is not a safe investment.
SPCE is not a normal growth company.
SPCE is not yet a proven business.
It is a high-risk turnaround/speculation setup based on one question:
Can Delta Class turn Virgin Galactic from a failed prototype-era story into a scalable commercial spaceflight business?
If the answer is yes, the current valuation could eventually look extremely cheap.
If the answer is no, the stock can continue destroying shareholders through dilution and cash burn.
For now, I am watching the pullback, not chasing the pump. I want to see whether price can return to the demand zone and whether the company can keep delivering real Delta milestones before the next report.
This is high risk, high uncertainty, and high volatility.
But if Delta testing continues, cash burn keeps improving, and commercial flights really start in Q4 2026, SPCE could become one of the more interesting speculative recovery setups in the market.
For me, that is not a reason to panic. That is exactly the kind of behavior I want to see before even considering an entry. I do not want to buy SPCE when everyone is chasing it. I want to see the price come back into a more reasonable demand zone, where the risk/reward becomes less stupid.
Technically, the chart shows a very sharp move up followed by a strong pullback. The highlighted demand zone is the area I am watching. If the price continues falling toward that zone, I would see it as potentially constructive, not necessarily bearish. The stock needed to cool down. The pump needed to be cleaned out.
But SPCE is not a clean investment. The company has a terrible history.
Virgin Galactic stopped commercial flights because the old VSS Unity vehicle was retired in 2024. Unity was not scalable. It carried only 4 passengers, had low flight frequency, required too much maintenance, and did not generate enough revenue to cover its flight support costs. Management itself admitted that Unity’s operating costs exceeded its modest monthly revenue. So the old business model did not work.
That is why the current thesis is not about Unity.
The entire investment case now depends on Delta Class.
Delta Class is supposed to fix the economic problem. Unlike Unity, which was closer to a hand-built prototype, Delta is designed for higher frequency, faster turnaround, more passengers, and better unit economics. The goal is to move from a prestige demonstration vehicle to something closer to a repeatable commercial operation.
That is the bullish case.
But the bear case is also very serious.
Virgin Galactic is still basically a pre-revenue company. Revenue is almost nonexistent. So yes, cash burn is improving, but it is still huge.
This is the central risk: SPCE must survive long enough to launch Delta commercially.
The market also knows that Virgin Galactic has a long history of delays, broken expectations, overpromising, and poor execution. This is not just normal skepticism. It is earned skepticism.
The company also has a serious credibility problem. In the past, management and Richard Branson presented flights as successful or flawless while important technical issues were allegedly not fully disclosed. Investors are right not to trust the story blindly.
However, there are also important changes.
First, the company is now under much more legal and disclosure pressure. Hiding major technical problems would be much more dangerous.
Second, the Delta milestones are now specific and verifiable. This is not just “soon” or “next year.” The current roadmap is clear:
Ground testing in 2026.
Flight testing targeted in 2026.
Commercial Delta flights targeted for Q4 2026.
Second Delta ship targeted around late 2026 or early 2027.
Higher flight cadence targeted after that.
This is exactly why the next few quarters matter so much.
The company does not need investors to believe a 10-year fantasy today. It needs to prove step by step that Delta is real, testable, flyable, and economically better than Unity.
That is the key point:
One Delta ship is not enough.
The model needs cadence.
Cadence needs multiple vehicles.
Multiple vehicles need capital.
Capital requires either investor confidence or dilution.
This is why SPCE is extremely risky.
But unlike many speculative bankrupt-looking names, SPCE does have a real possible economic path. It is not guaranteed, but it is understandable.
If Delta works, the company can move from almost no revenue to a real commercial phase. If Delta does not work, or if testing is delayed, or if cash runs out before meaningful revenue begins, shareholders may face more dilution, restructuring risk, or worse.
From a chart perspective, I am not interested in buying the top of a hype candle. The recent move looked too emotional. I prefer the pullback. A drop back toward the demand zone could offer a better speculative setup, especially if the company continues to confirm Delta progress and cash burn does not accelerate.
My current view:
SPCE is not a safe investment.
SPCE is not a normal growth company.
SPCE is not yet a proven business.
It is a high-risk turnaround/speculation setup based on one question:
Can Delta Class turn Virgin Galactic from a failed prototype-era story into a scalable commercial spaceflight business?
If the answer is yes, the current valuation could eventually look extremely cheap.
If the answer is no, the stock can continue destroying shareholders through dilution and cash burn.
For now, I am watching the pullback, not chasing the pump. I want to see whether price can return to the demand zone and whether the company can keep delivering real Delta milestones before the next report.
This is high risk, high uncertainty, and high volatility.
But if Delta testing continues, cash burn keeps improving, and commercial flights really start in Q4 2026, SPCE could become one of the more interesting speculative recovery setups in the market.
Trade active
as for now , everything seems oke. price going downNote
earth gravity still working fine :) 
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.