
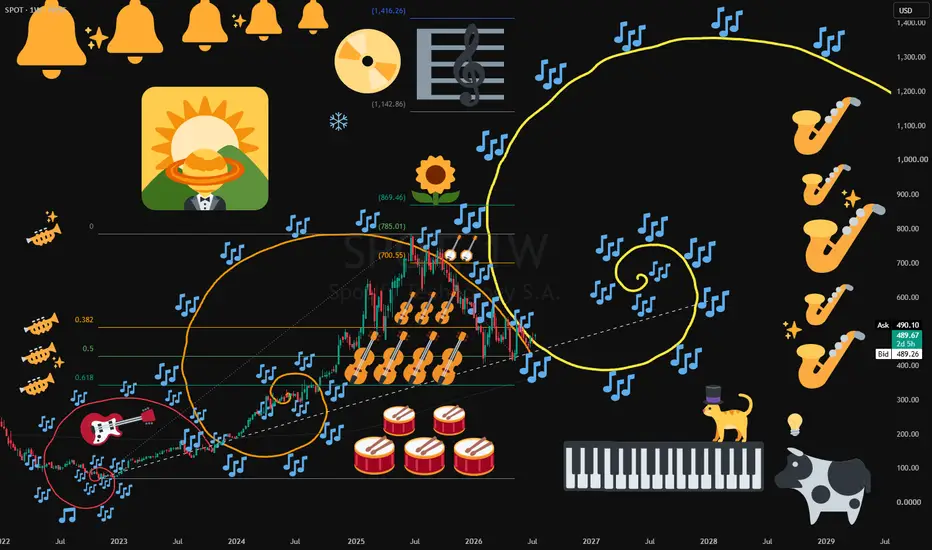
The recent sell-off in Spotify provides a classic case study in market heuristic misalignment, wherein short-horizon market participants overweight near-term volume metrics over structural inflection in the company’s underlying unit economics.
The primary catalyst was a 1.4-million variance in Q2 Premium subscriber forward guidance (299M versus 300.4M consensus). While some view this 0.4% discrepancy as a sign of slowing user acquisition, evaluating this miss in isolation misconstrues the underlying mechanics of Spotify's current scaling phase.
Rather than relying on raw volume growth, the platform's long-term valuation is increasingly dictated by structural gross margin expansion, which reached a record 33.0% in Q1. This margin profile effectively invalidates the legacy bear thesis, which posited that Spotify’s gross margins were hard-capped by a linear, variable-cost 70% royalty payout architecture to major music labels.
Today, Spotify is leveraging high-margin software mechanisms, principally its two-sided marketplace suite, algorithmic sponsored recommendations and verticalized audiobook content to decouple gross profit generation from stream velocity. These marketplace tools function as a negative variable cost, allowing Spotify to extract promotional fees from rights holders, thereby expanding contribution margins and unlocking significant operating leverage.
This structural shift is supported by recent financial performance; while reported Q1 2026 revenue grew 8% to €4.53 billion, revenue accelerated by 14% to 15% on a constant-currency basis, proving fears of "top-line deceleration" were primarily an artifact of foreign exchange distortion.
This underlying momentum, coupled with a total user ecosystem expanding to 761 million Monthly Active Users, indicates the platform's core monetization engine remains functional.
Finally, generating a record €824 million in Free Cash Flow in a single quarter highlights a notable valuation asymmetry.
Unlike video streaming peers that must continuously deploy billions in upfront capital for high-risk content production, Spotify’s audio infrastructure requires minimal capital expenditures. This enables a high cash conversion rate, meaning the stock may be mispriced on legacy metrics just as its structural cash engine scales.
The primary catalyst was a 1.4-million variance in Q2 Premium subscriber forward guidance (299M versus 300.4M consensus). While some view this 0.4% discrepancy as a sign of slowing user acquisition, evaluating this miss in isolation misconstrues the underlying mechanics of Spotify's current scaling phase.
Rather than relying on raw volume growth, the platform's long-term valuation is increasingly dictated by structural gross margin expansion, which reached a record 33.0% in Q1. This margin profile effectively invalidates the legacy bear thesis, which posited that Spotify’s gross margins were hard-capped by a linear, variable-cost 70% royalty payout architecture to major music labels.
Today, Spotify is leveraging high-margin software mechanisms, principally its two-sided marketplace suite, algorithmic sponsored recommendations and verticalized audiobook content to decouple gross profit generation from stream velocity. These marketplace tools function as a negative variable cost, allowing Spotify to extract promotional fees from rights holders, thereby expanding contribution margins and unlocking significant operating leverage.
This structural shift is supported by recent financial performance; while reported Q1 2026 revenue grew 8% to €4.53 billion, revenue accelerated by 14% to 15% on a constant-currency basis, proving fears of "top-line deceleration" were primarily an artifact of foreign exchange distortion.
This underlying momentum, coupled with a total user ecosystem expanding to 761 million Monthly Active Users, indicates the platform's core monetization engine remains functional.
Finally, generating a record €824 million in Free Cash Flow in a single quarter highlights a notable valuation asymmetry.
Unlike video streaming peers that must continuously deploy billions in upfront capital for high-risk content production, Spotify’s audio infrastructure requires minimal capital expenditures. This enables a high cash conversion rate, meaning the stock may be mispriced on legacy metrics just as its structural cash engine scales.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.