
Synthesized Investment Thesis for STERIS plc (STE): A Defensive Business with Questionable Capital Allocation at a Rich Valuation
STERIS represents a classic investment dilemma: it operates in a stable, mission-critical industry but appears to be a mediocre capital allocator, making its current valuation difficult to justify for growth-oriented investors. The stock's recent market underperformance and technical positioning suggest a "wait-and-see" or cautious approach is prudent.
Core Fundamental Analysis: The "Why" Behind the Lack of Excitement
The Critical Flaw: Chronic Underperformance on Capital Efficiency
The central and most damning argument against STERIS is its persistently low Return on Invested Capital (ROIC). With a five-year average ROIC of 4.9%, the company generates a return that is likely below its own weighted average cost of capital (WACC). This implies that for years, management's investments—whether in R&D, acquisitions, or capacity expansion—have, in aggregate, destroyed shareholder value rather than created it. Capital allocation is a primary driver of long-term returns, and STERIS's track record here is uninspiring.
A Strong Moat Undermined by Weak Execution
STERIS's business model is inherently defensive and valuable. Its role in infection prevention, sterilization, and medical device reprocessing is non-discretionary for healthcare and life sciences clients. This provides recurring revenue, high customer retention, and resilience during economic downturns. However, the low ROIC indicates that this strong market position has not been translated into superior profitability on the capital employed. The company's "shakier fundamentals" refer to this disconnect between a great industry position and subpar financial returns.
Rich Valuation Amidst Mediocre Metrics
Trading at approximately 24.3x forward P/E, the market is pricing STERIS as a high-quality healthcare growth stock. This multiple is difficult to square with a company whose core profitability metric (ROIC) signals value destruction. The valuation appears to reflect the stability and necessity of the industry rather than the excellence of the company's execution. This creates asymmetric downside risk; if growth slows or margins contract, the elevated multiple is vulnerable to compression.
Technical Analysis & Price Action Context
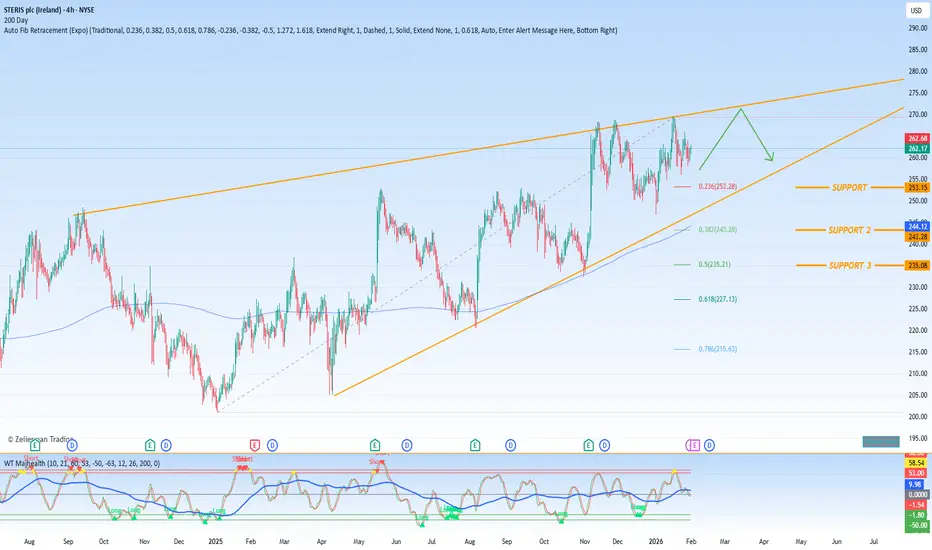
The stock's 7.1% gain over six months, which lagged the S&P 500's 14.4% return, reflects the market's tepid response to its fundamentals. The provided Fibonacci retracement levels offer a clear roadmap for potential support and risk assessment:
Defined Support Zone: The analysis identifies a critical Fibonacci support cluster between $253.28 and $235.21. This zone is derived from key retracement levels of a prior price move:
0.236 Level: $253.28 (Initial, weaker support)
0.382 Level: $243.28 (A standard, stronger Fibonacci support)
0.500 Level: $235.21 (The most significant psychological and technical midline support)
Interpretation: This zone represents a likely area where buyers may step in, based on historical price patterns. A decisive breakdown below $235.21 would be a significant technical failure, potentially opening the door to much lower prices and validating the fundamental bear case.
Integrated Final Judgment & Strategic Implications
STERIS is not a "terrible" business, but it is a potentially disappointing investment at current levels. The combination of poor historical capital allocation (low ROIC) and a full valuation (high P/E) presents an unfavorable risk/reward profile.
For Current Investors: The stock may serve as a stable, defensive holding, but with muted expectations for alpha generation. The technical support zone ($253 - $235) is crucial; a break below it, especially on high volume, would be a strong sell signal.
For Potential Investors: There is no compelling catalyst for entry here. The stock is not cheap enough to be a deep-value play, and its growth/capital efficiency is not strong enough to be a growth compounder. A more attractive entry point would be closer to the lower end of the technical support zone ($235-$240), where the valuation would be more palatable, providing a margin of safety against the fundamental weaknesses.
The Alternative: As the analysis suggests, there are likely higher-quality companies within the healthcare sector or industrials with better ROIC profiles trading at similar or lower valuations. Capital is likely better deployed in businesses that demonstrably earn high returns on invested capital.
In summary, STERIS is a "show me" story. The market is rightly skeptical. Until the company demonstrates a sustained improvement in capital efficiency—translating its strong market position into higher ROIC—the stock is likely to continue its pattern of lagging the broader market. The prudent action is to avoid or hold with a tight stop-loss below the key $235 support, awaiting either a more attractive price or clearer evidence of fundamental improvement.
STERIS represents a classic investment dilemma: it operates in a stable, mission-critical industry but appears to be a mediocre capital allocator, making its current valuation difficult to justify for growth-oriented investors. The stock's recent market underperformance and technical positioning suggest a "wait-and-see" or cautious approach is prudent.
Core Fundamental Analysis: The "Why" Behind the Lack of Excitement
The Critical Flaw: Chronic Underperformance on Capital Efficiency
The central and most damning argument against STERIS is its persistently low Return on Invested Capital (ROIC). With a five-year average ROIC of 4.9%, the company generates a return that is likely below its own weighted average cost of capital (WACC). This implies that for years, management's investments—whether in R&D, acquisitions, or capacity expansion—have, in aggregate, destroyed shareholder value rather than created it. Capital allocation is a primary driver of long-term returns, and STERIS's track record here is uninspiring.
A Strong Moat Undermined by Weak Execution
STERIS's business model is inherently defensive and valuable. Its role in infection prevention, sterilization, and medical device reprocessing is non-discretionary for healthcare and life sciences clients. This provides recurring revenue, high customer retention, and resilience during economic downturns. However, the low ROIC indicates that this strong market position has not been translated into superior profitability on the capital employed. The company's "shakier fundamentals" refer to this disconnect between a great industry position and subpar financial returns.
Rich Valuation Amidst Mediocre Metrics
Trading at approximately 24.3x forward P/E, the market is pricing STERIS as a high-quality healthcare growth stock. This multiple is difficult to square with a company whose core profitability metric (ROIC) signals value destruction. The valuation appears to reflect the stability and necessity of the industry rather than the excellence of the company's execution. This creates asymmetric downside risk; if growth slows or margins contract, the elevated multiple is vulnerable to compression.
Technical Analysis & Price Action Context
The stock's 7.1% gain over six months, which lagged the S&P 500's 14.4% return, reflects the market's tepid response to its fundamentals. The provided Fibonacci retracement levels offer a clear roadmap for potential support and risk assessment:
Defined Support Zone: The analysis identifies a critical Fibonacci support cluster between $253.28 and $235.21. This zone is derived from key retracement levels of a prior price move:
0.236 Level: $253.28 (Initial, weaker support)
0.382 Level: $243.28 (A standard, stronger Fibonacci support)
0.500 Level: $235.21 (The most significant psychological and technical midline support)
Interpretation: This zone represents a likely area where buyers may step in, based on historical price patterns. A decisive breakdown below $235.21 would be a significant technical failure, potentially opening the door to much lower prices and validating the fundamental bear case.
Integrated Final Judgment & Strategic Implications
STERIS is not a "terrible" business, but it is a potentially disappointing investment at current levels. The combination of poor historical capital allocation (low ROIC) and a full valuation (high P/E) presents an unfavorable risk/reward profile.
For Current Investors: The stock may serve as a stable, defensive holding, but with muted expectations for alpha generation. The technical support zone ($253 - $235) is crucial; a break below it, especially on high volume, would be a strong sell signal.
For Potential Investors: There is no compelling catalyst for entry here. The stock is not cheap enough to be a deep-value play, and its growth/capital efficiency is not strong enough to be a growth compounder. A more attractive entry point would be closer to the lower end of the technical support zone ($235-$240), where the valuation would be more palatable, providing a margin of safety against the fundamental weaknesses.
The Alternative: As the analysis suggests, there are likely higher-quality companies within the healthcare sector or industrials with better ROIC profiles trading at similar or lower valuations. Capital is likely better deployed in businesses that demonstrably earn high returns on invested capital.
In summary, STERIS is a "show me" story. The market is rightly skeptical. Until the company demonstrates a sustained improvement in capital efficiency—translating its strong market position into higher ROIC—the stock is likely to continue its pattern of lagging the broader market. The prudent action is to avoid or hold with a tight stop-loss below the key $235 support, awaiting either a more attractive price or clearer evidence of fundamental improvement.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.