
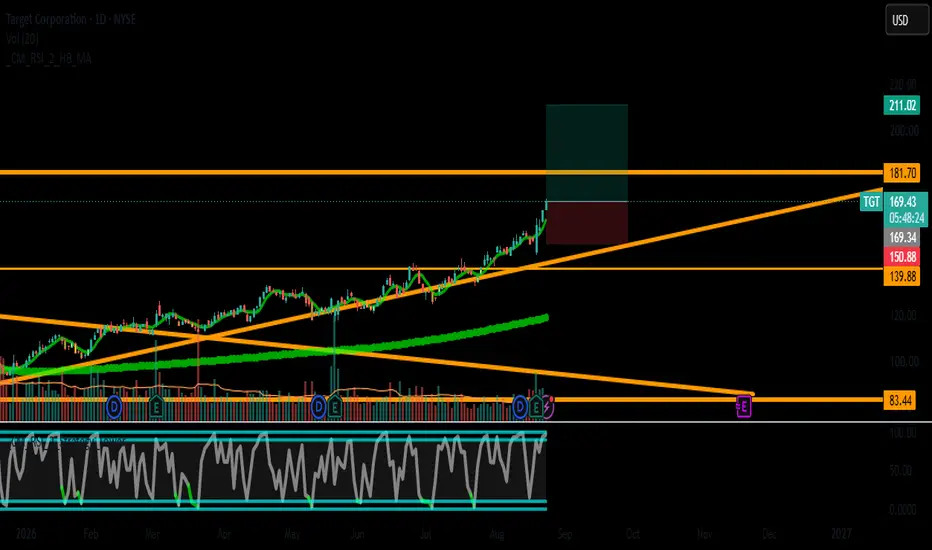
Idea: Long TGT (Target Corporation)
Entry: $169.00
**Stop Loss:** $150.00
Take Profit: $211.00
**Risk/Reward:** ~1:2.8 (Risk $19.00 / Reward $42.00)
Timeframe: Swing / Position Trading (Weeks to Months)
The Setup
Target delivered a blowout Q2 2026 earnings beat on August 19, reporting adjusted EPS of $4.11**, more than doubling from $2.05 a year earlier, crushing the $2.30 consensus by a wide margin, on revenue of **$26.54 billion, also surpassing estimates. Total comparable sales grew 3.8%, driven entirely by a 3.6% increase in traffic — a sign of genuine demand.
The stock has since rallied to new 52-week highs, hitting $165.48** and closing Friday at **$165.44, up 4.54% on the session. The $169 entry level represents a breakout above the recent consolidation, with the stock having established strong momentum post-earnings.
The Fundamentals
Q2 2026 highlights:
Revenue: $26.54 billion, +5.3% YoY, beating estimates
Adjusted EPS: $4.11, more than doubled YoY
Comparable Sales: +3.8%, driven by +3.6% traffic growth
Digital Sales: +8.7% YoY
Net Income: $1.88 billion including a **$752 million tariff refund**
The tariff refund factor: The $4.11 adjusted EPS included **$1.65 per share** from tariff refunds. Excluding this one-time benefit, underlying EPS still grew approximately 20% year-over-year — a solid performance that validates the turnaround thesis.
Guidance raised significantly:
Full-year EPS: Raised to $9.90–$10.90, representing roughly 30% growth
Net sales growth: Raised to ~5% from ~4% previously
Excluding tariff refunds, the midpoint of the guidance still represents a meaningful raise
Valuation: Target trades at a P/E of approximately 17.1x, which is reasonable given the accelerating growth trajectory and raised guidance.
Analyst Backing
Wall Street has been raising targets following the Q2 beat:
DA Davidson: Raised target from $155 to **$170** (Buy)
RBC Capital: Maintains Buy with $166 target
24/7 Wall St: Price target of $183.19, implying 12.2% upside
BofA Securities: Raised target from $110 to **$124** (Underperform)
Zacks Research: Downgraded from Strong Buy to Hold post-earnings
Consensus: The overall analyst sentiment is mixed, with some raising targets aggressively (DA Davidson to $170) while others remain cautious (BofA at $124). However, the average target has been trending higher since the earnings beat, and our $211 take profit sits well above the current average, targeting a continuation of the strong momentum.
Jim Cramer noted that Target's numbers were "strong enough to send shares up more than 5% that morning".
Technical Setup
The stock is breaking out to new 52-week highs after a strong post-earnings rally:
52-Week High: $165.48 (set August 24)
Current Price: ~$165.44 (Friday close)
YTD Performance: +66% year-to-date
1-Year Return: +77.2%
Key levels:
Support: $155–$160 (recent breakout zone and prior resistance)
Primary support: $150.00 (our stop level, below the 50-day MA)
Resistance: $170 (DA Davidson target and psychological level)
Major resistance: $183 (24/7 Wall St target)
Ultimate target: $211 (our take profit)
Technical context: The stock has been in a strong uptrend since the turnaround began under new CEO Michael Fiddelke, with the Q2 earnings beat acting as a powerful catalyst. The recent breakout above the 52-week high suggests institutional accumulation is continuing.
Entry at $169** offers a clean entry above the 52-week high and the recent consolidation zone, with the stock having established strong momentum. **Stop at $150 sits below the 50-day moving average and recent support levels, providing structural protection. Target at $211 represents a measured move to the upside, aligning with the stock's strong momentum and the raised guidance.
The Catalyst
The Q2 earnings beat on August 19 was the primary catalyst. The post-earnings rally represents confirmation of the turnaround thesis — not a one-time event. The fundamental story remains intact:
Traffic-driven growth: 3.6% increase in comparable traffic — the strongest indicator of sustainable demand
Digital acceleration: 8.7% digital sales growth
Raised guidance: Full-year EPS raised to $9.90–$10.90
New CEO execution: Michael Fiddelke's turnaround strategy is gaining traction
Upcoming catalysts:
Continued share buybacks and capital returns
Holiday season ramp in Q3 and Q4
Potential further analyst upgrades as the Street digests Q2 results
Key Risks
Tariff refund is one-time: The $1.65 per share benefit will not repeat, creating a tough compare next year
Mixed analyst sentiment: Zacks downgraded to Hold post-earnings, and BofA maintains Underperform with a $124 target
Valuation run-up: The stock is up 66% YTD and 77.2% over the past year — expectations are elevated
Competitive pressure: Intense competition from Walmart, Costco, and Amazon
Break below $150 would invalidate the support thesis
Conclusion
Target offers a high-probability setup on three pillars:
Fundamental: Blowout Q2 earnings beat ($4.11 vs $2.30 consensus), 5.3% revenue growth, 3.8% comparable sales driven by 3.6% traffic growth, raised full-year guidance to $9.90–$10.90 EPS, and a 20% underlying EPS growth (excluding tariff refunds)
Technical: Clean breakout to new 52-week highs ($165.48), strong momentum with 66% YTD gains, and a clear path to $183–$211 resistance
Institutional: Rising analyst targets post-earnings (DA Davidson to $170, RBC to $166, 24/7 Wall St at $183.19), with the stock having gained 4.54% on Friday amid a series of price target hikes
Entry $169, Stop $150, Target $211 — a clean, risk-defined setup with favorable 1:2.8 asymmetry. Buying this post-earnings breakout at new highs, with strong institutional backing and a raised guidance, should be well-rewarded as the stock continues its re-rating toward fair value.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.