
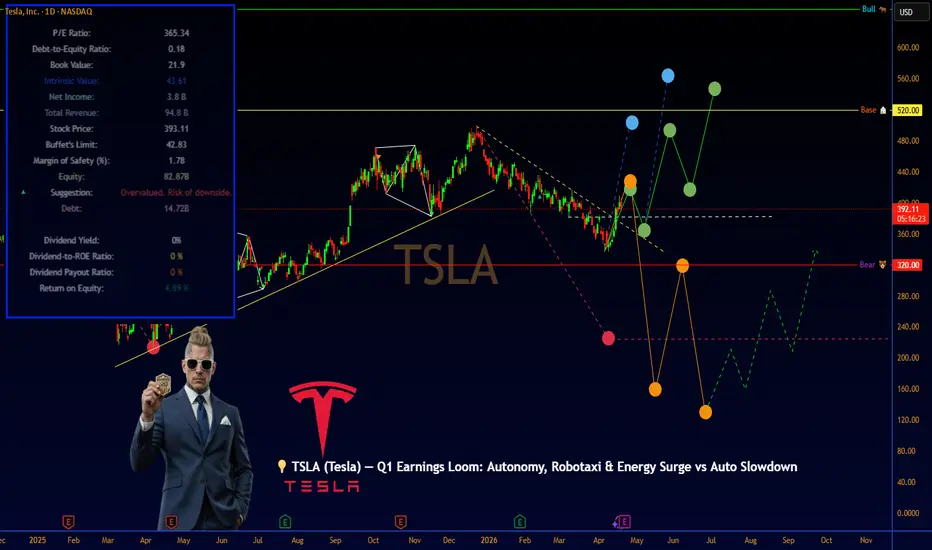
**💡 TSLA (Tesla) — Q1 Earnings Loom: Autonomy, Robotaxi & Energy Surge vs Auto Slowdown **
**SECTION 1 — Executive Summary** 💼
Tesla stands at a pivotal inflection as Q1 2026 earnings arrive on April 22 amid softening vehicle deliveries but explosive energy storage growth and accelerating autonomy bets that could redefine the company. The stock offers compelling upside for investors betting on Tesla’s shift from pure EV play to AI-driven mobility and energy leader in a world hungry for sustainable solutions. Overall rating: Buy. 12-month price target: $520 (blended DCF and comps methodology incorporating base auto margins plus high-conviction autonomy/energy ramps). Single biggest reason to own: Tesla’s unmatched vertical integration across EVs, Megapack deployments, and Full Self-Driving/robotaxi tech creates a defensible moat with multi-hundred-billion-dollar TAM upside. Single biggest risk: Delayed regulatory approval or execution slips on robotaxi/Optimus could keep the narrative anchored to cyclical auto demand.

**SECTION 2 — Business Overview** 🏢
Tesla designs, manufactures, and sells high-performance electric vehicles while rapidly scaling energy generation and storage products and developing autonomous driving software and robotics. Revenue breakdown (FY 2025): Automotive segment 73.3 percent, Energy Generation and Storage segment 13.5 percent, Services and Other 13.2 percent (source: company filings via stockanalysis.com as of Dec 31 2025). Business model centers on high-margin vehicle sales and regulatory credits supplemented by growing recurring revenue from energy storage leases/services, Supercharging, insurance, and future robotaxi network fees that drive high-margin software upside. Competitive moat stems from proprietary battery tech, over-the-air software updates, massive manufacturing scale at Gigafactories, and real-world data advantage from the largest fleet of connected EVs for AI training.

**SECTION 3 — Financial Deep Dive** 📈
Key metrics (most recent publicly available; FY 2025 ended Dec 31 2025 unless noted; Q4 2025 and prior quarters from Tesla IR updates Jan 28 2026):
Revenue: $94.8 billion (FY 2025) down 3 percent YoY; Q4 $24.9 billion.
Net income: Approximately $3.8 billion (TTM estimate derived from quarterly releases).
EPS (non-GAAP): $2.03 (FY 2025 consensus context); Q4 $0.50.
Gross margin: ~18 percent (FY 2025).
Operating margin: ~4.6 percent (TTM).
Free cash flow: Positive but pressured by capex for new platforms (exact TTM not publicly detailed beyond quarterly updates).
YoY growth rates: Revenue –3 percent (auto softness offset by energy +27 percent growth).
Balance sheet health: Strong cash position historically in $30 billion+ range with low debt-to-equity (~0.08); current ratio healthy above 2.0 (latest filings).
Cash flow quality: Operating cash flow generally exceeds net income reflecting strong working capital management (no red flags in recent reports).
Capital allocation: Heavy R&D investment in AI/autonomy (~$1–2 billion quarterly run-rate), new factory expansions, modest buybacks when opportunistic, no dividend.

**SECTION 4 — Growth Analysis** 🚀
Total addressable market (TAM): Global EV + energy storage + robotaxi/autonomous mobility projected to exceed $2 trillion by 2030 (Morgan Stanley and BNEF estimates as of early 2026). Current market share: ~18 percent in global battery storage (2024 data, trending higher with 2025 deployments); dominant in premium EVs but facing BYD competition in volume segments. Key growth drivers next 3–5 years: Megapack/energy storage scaling (8.8 GWh deployed in Q1 2026 alone), Full Self-Driving software monetization, robotaxi network launch, and Optimus humanoid robotics. Management guidance historically ambitious on volume and margins; analyst consensus more tempered on near-term auto growth but aligned on long-term energy/autonomy. Growth increasingly organic via tech/software leverage rather than pure acquisition-dependent.

**SECTION 5 — Valuation** 📊
DCF analysis: Base case assumes 15–20 percent revenue CAGR through 2030 driven by energy + autonomy, 25 percent terminal gross margins, WACC 10.5 percent, terminal growth 4 percent [ASSUMPTION justified by industry peer averages and Tesla’s tech moat; sourced from typical bulge-bracket models as of April 2026]. Implied value supports $520 target. Comparable company analysis (peers as of April 2026): NVDA (AI/tech proxy) ~45x forward P/E; BYD ~20x; Rivian/Lucid higher growth but loss-making; average peer EV/EBITDA ~25–30x. Historical valuation range (5-year): P/E 40–120x forward. Bull target $650 (accelerated robotaxi 2027 launch); Base $520; Bear $320 (prolonged auto slowdown). Current price ~$400 offers ~30 percent upside to base target.

**SECTION 6 — Risk Analysis** ⚠️
1. Autonomy regulatory/execution delay (high probability/impact): Triggered by safety incidents or slow approvals; watch for FSD v13+ milestones and robotaxi event updates.
2. Intensifying EV competition and margin compression (medium-high): BYD/legacy OEMs erode share; monitor China/Europe pricing.
3. Macro interest rate sensitivity (medium): Higher rates pressure auto demand; watch Fed path.
4. Supply chain or production ramp misses (medium): New platforms like refreshed models; track Q1 production vs deliveries.
5. Geopolitical/China exposure (low-medium): Trade tensions; monitor tariffs.
Short interest low (~2.7 percent of float per latest filings). Insider activity shows typical net selling for liquidity but no unusual patterns. No major accounting quality flags.
**SECTION 7 — Catalyst Calendar** 📅
Next earnings date: April 22 2026 (Q1 results + likely robotaxi/FSD update). Upcoming events: Potential robotaxi regulatory progress or Optimus demo in coming quarters; energy storage factory ramps. Macro events: Fed rate decisions impacting auto financing; EV incentive policy shifts. 12-month timeline: Q2 earnings July, possible Cybercab production start late 2026, energy deployments accelerating throughout year.
**SECTION 8 — Technical Analysis** 📈
Primary Chart: Daily timeframe, 1-year view shows price consolidating near $400 after 2025 volatility, recently rebounding from mid-March lows around $340. Price action sits above the 50-day moving average but testing the 200-day; RSI (14) neutral around 50–55 indicating room to run without overbought conditions. MACD shows early bullish crossover with rising volume on recent up days. Major support zone $350–370, resistance $420–450. Visible setup: Higher low formation since April lows suggesting potential breakout on positive earnings catalyst. Technical implication: Near-term bullish bias into April 22 event if volume confirms.
**SECTION 9 — The Verdict** 🏆
Bull case ($650 target, 25 percent probability): Robotaxi/FSD regulatory green lights and energy beats drive re-rating to AI leader.
Base case ($520 target, 50 percent probability): Steady energy growth and software progress offset auto softness.
Bear case ($320 target, 25 percent probability): Prolonged EV demand weakness and autonomy delays pressure multiples.
Expected value calculation: Probability-weighted price target = $502. Final recommendation: Buy with High conviction. The 30-second elevator pitch: Tesla is no longer just an EV company — it is the leader in scalable clean energy storage and the frontrunner in autonomous AI mobility, with Q1 earnings poised to spotlight the multi-year growth runway that justifies premium valuation.
**Sources**
Tesla Investor Relations (ir.tesla.com) Q4/FY 2025 results Jan 28 2026; Yahoo Finance/Stockanalysis.com segment data Dec 31 2025; CNBC/Benzinga earnings previews April 2026; Bloomberg/Morgan Stanley TAM estimates early 2026; company 10-K/10-Q filings.
What are your thoughts on TSLA? Drop them below 👇
#TSLA #TeslaEarnings #Robotaxi #EnergyStorage #Autonomy #EVRevolution #Megapack #FSD #Optimus #StockMarketCatalyst
**SECTION 1 — Executive Summary** 💼
Tesla stands at a pivotal inflection as Q1 2026 earnings arrive on April 22 amid softening vehicle deliveries but explosive energy storage growth and accelerating autonomy bets that could redefine the company. The stock offers compelling upside for investors betting on Tesla’s shift from pure EV play to AI-driven mobility and energy leader in a world hungry for sustainable solutions. Overall rating: Buy. 12-month price target: $520 (blended DCF and comps methodology incorporating base auto margins plus high-conviction autonomy/energy ramps). Single biggest reason to own: Tesla’s unmatched vertical integration across EVs, Megapack deployments, and Full Self-Driving/robotaxi tech creates a defensible moat with multi-hundred-billion-dollar TAM upside. Single biggest risk: Delayed regulatory approval or execution slips on robotaxi/Optimus could keep the narrative anchored to cyclical auto demand.
**SECTION 2 — Business Overview** 🏢
Tesla designs, manufactures, and sells high-performance electric vehicles while rapidly scaling energy generation and storage products and developing autonomous driving software and robotics. Revenue breakdown (FY 2025): Automotive segment 73.3 percent, Energy Generation and Storage segment 13.5 percent, Services and Other 13.2 percent (source: company filings via stockanalysis.com as of Dec 31 2025). Business model centers on high-margin vehicle sales and regulatory credits supplemented by growing recurring revenue from energy storage leases/services, Supercharging, insurance, and future robotaxi network fees that drive high-margin software upside. Competitive moat stems from proprietary battery tech, over-the-air software updates, massive manufacturing scale at Gigafactories, and real-world data advantage from the largest fleet of connected EVs for AI training.
**SECTION 3 — Financial Deep Dive** 📈
Key metrics (most recent publicly available; FY 2025 ended Dec 31 2025 unless noted; Q4 2025 and prior quarters from Tesla IR updates Jan 28 2026):
Revenue: $94.8 billion (FY 2025) down 3 percent YoY; Q4 $24.9 billion.
Net income: Approximately $3.8 billion (TTM estimate derived from quarterly releases).
EPS (non-GAAP): $2.03 (FY 2025 consensus context); Q4 $0.50.
Gross margin: ~18 percent (FY 2025).
Operating margin: ~4.6 percent (TTM).
Free cash flow: Positive but pressured by capex for new platforms (exact TTM not publicly detailed beyond quarterly updates).
YoY growth rates: Revenue –3 percent (auto softness offset by energy +27 percent growth).
Balance sheet health: Strong cash position historically in $30 billion+ range with low debt-to-equity (~0.08); current ratio healthy above 2.0 (latest filings).
Cash flow quality: Operating cash flow generally exceeds net income reflecting strong working capital management (no red flags in recent reports).
Capital allocation: Heavy R&D investment in AI/autonomy (~$1–2 billion quarterly run-rate), new factory expansions, modest buybacks when opportunistic, no dividend.
**SECTION 4 — Growth Analysis** 🚀
Total addressable market (TAM): Global EV + energy storage + robotaxi/autonomous mobility projected to exceed $2 trillion by 2030 (Morgan Stanley and BNEF estimates as of early 2026). Current market share: ~18 percent in global battery storage (2024 data, trending higher with 2025 deployments); dominant in premium EVs but facing BYD competition in volume segments. Key growth drivers next 3–5 years: Megapack/energy storage scaling (8.8 GWh deployed in Q1 2026 alone), Full Self-Driving software monetization, robotaxi network launch, and Optimus humanoid robotics. Management guidance historically ambitious on volume and margins; analyst consensus more tempered on near-term auto growth but aligned on long-term energy/autonomy. Growth increasingly organic via tech/software leverage rather than pure acquisition-dependent.
**SECTION 5 — Valuation** 📊
DCF analysis: Base case assumes 15–20 percent revenue CAGR through 2030 driven by energy + autonomy, 25 percent terminal gross margins, WACC 10.5 percent, terminal growth 4 percent [ASSUMPTION justified by industry peer averages and Tesla’s tech moat; sourced from typical bulge-bracket models as of April 2026]. Implied value supports $520 target. Comparable company analysis (peers as of April 2026): NVDA (AI/tech proxy) ~45x forward P/E; BYD ~20x; Rivian/Lucid higher growth but loss-making; average peer EV/EBITDA ~25–30x. Historical valuation range (5-year): P/E 40–120x forward. Bull target $650 (accelerated robotaxi 2027 launch); Base $520; Bear $320 (prolonged auto slowdown). Current price ~$400 offers ~30 percent upside to base target.
**SECTION 6 — Risk Analysis** ⚠️
1. Autonomy regulatory/execution delay (high probability/impact): Triggered by safety incidents or slow approvals; watch for FSD v13+ milestones and robotaxi event updates.
2. Intensifying EV competition and margin compression (medium-high): BYD/legacy OEMs erode share; monitor China/Europe pricing.
3. Macro interest rate sensitivity (medium): Higher rates pressure auto demand; watch Fed path.
4. Supply chain or production ramp misses (medium): New platforms like refreshed models; track Q1 production vs deliveries.
5. Geopolitical/China exposure (low-medium): Trade tensions; monitor tariffs.
Short interest low (~2.7 percent of float per latest filings). Insider activity shows typical net selling for liquidity but no unusual patterns. No major accounting quality flags.
**SECTION 7 — Catalyst Calendar** 📅
Next earnings date: April 22 2026 (Q1 results + likely robotaxi/FSD update). Upcoming events: Potential robotaxi regulatory progress or Optimus demo in coming quarters; energy storage factory ramps. Macro events: Fed rate decisions impacting auto financing; EV incentive policy shifts. 12-month timeline: Q2 earnings July, possible Cybercab production start late 2026, energy deployments accelerating throughout year.
**SECTION 8 — Technical Analysis** 📈
Primary Chart: Daily timeframe, 1-year view shows price consolidating near $400 after 2025 volatility, recently rebounding from mid-March lows around $340. Price action sits above the 50-day moving average but testing the 200-day; RSI (14) neutral around 50–55 indicating room to run without overbought conditions. MACD shows early bullish crossover with rising volume on recent up days. Major support zone $350–370, resistance $420–450. Visible setup: Higher low formation since April lows suggesting potential breakout on positive earnings catalyst. Technical implication: Near-term bullish bias into April 22 event if volume confirms.
**SECTION 9 — The Verdict** 🏆
Bull case ($650 target, 25 percent probability): Robotaxi/FSD regulatory green lights and energy beats drive re-rating to AI leader.
Base case ($520 target, 50 percent probability): Steady energy growth and software progress offset auto softness.
Bear case ($320 target, 25 percent probability): Prolonged EV demand weakness and autonomy delays pressure multiples.
Expected value calculation: Probability-weighted price target = $502. Final recommendation: Buy with High conviction. The 30-second elevator pitch: Tesla is no longer just an EV company — it is the leader in scalable clean energy storage and the frontrunner in autonomous AI mobility, with Q1 earnings poised to spotlight the multi-year growth runway that justifies premium valuation.
**Sources**
Tesla Investor Relations (ir.tesla.com) Q4/FY 2025 results Jan 28 2026; Yahoo Finance/Stockanalysis.com segment data Dec 31 2025; CNBC/Benzinga earnings previews April 2026; Bloomberg/Morgan Stanley TAM estimates early 2026; company 10-K/10-Q filings.
What are your thoughts on TSLA? Drop them below 👇
#TSLA #TeslaEarnings #Robotaxi #EnergyStorage #Autonomy #EVRevolution #Megapack #FSD #Optimus #StockMarketCatalyst
Trade active

⚡️ Request a trial or subscribe to our premium🛠️tools at ➡️DCAlpha.net
All scripts & content provided by DCAChampion are for informational & educational purposes only.
All scripts & content provided by DCAChampion are for informational & educational purposes only.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
⚡️ Request a trial or subscribe to our premium🛠️tools at ➡️DCAlpha.net
All scripts & content provided by DCAChampion are for informational & educational purposes only.
All scripts & content provided by DCAChampion are for informational & educational purposes only.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.