
Executive Summary:
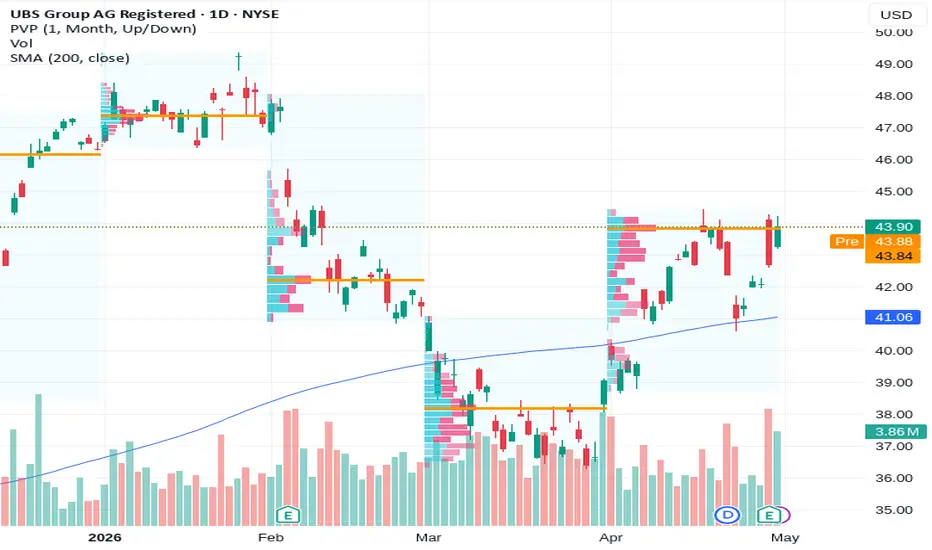
UBS today stands as one of the strongest global wealth management franchises, reinforced by the absorption of Credit Suisse and the enduring strength of the Swiss safe haven brand. The underlying business looks durable and capable of compounding book value over time. However, the stock currently trades close to estimated intrinsic value. Margin of safety verdict: insufficient. At today’s price, the analysis is informative from an intellectual standpoint but does not present an actionable value investment.
One Stock, Dozens of Voices:
This is not the view of a single analyst. CrowdWisdom aggregated 32 independent sources for UBS (20 financial research articles (web); 11 prior CrowdWisdom analysis snapshots (internal archive); 1 verified financial data checks (Yahoo Finance)) and distilled the shared thesis: where dozens of traders, investors, and researchers broadly agree, where their views diverge, and what the market may be overlooking.
Those perspectives were then pressure-tested by setting opposing arguments against each other. The process examined a bull case, a bear case that challenges the consensus, and a review of what expectations are already embedded in the current price. All financial metrics were cross-validated against live market data.
The sections that follow highlight where opinion converges, where it breaks apart, and whether the stock offers any real margin of safety at today’s price.
Business Quality and Moat Durability:
UBS operates at the center of global private banking. Its core engine is wealth management serving high net worth and ultra high net worth clients across Europe, Asia, and the Americas.
Three structural advantages underpin the business.
The first is global scale. Wealth management demands large advisory teams, deep investment product infrastructure, extensive regulatory compliance capabilities, and international tax expertise. Building a platform of this kind takes decades. The Credit Suisse acquisition dramatically expanded UBS’s client assets and advisory capacity, strengthening its global reach.
The second advantage is reputation. Swiss banking has long been associated with stability and discretion. For wealthy families managing multigenerational capital, trust often carries as much weight as pricing. UBS benefits from that intangible asset in a way many competitors cannot easily replicate.
The third is switching friction. Ultra wealthy clients typically maintain diversified portfolios structured through trusts, estate plans, cross border tax arrangements, and bespoke investment mandates. Moving those structures to another institution can take months and introduces operational risk. As a result, client relationships tend to be sticky.
The integration of Credit Suisse further strengthens the competitive position. UBS effectively removed its largest domestic competitor while absorbing a large base of wealth clients and advisors.
At present, the moat appears stable with the possibility of modest expansion. Consolidation has increased scale. However, fee pressure from passive investing and aggressive competition from American wealth platforms such as Morgan Stanley and JPMorgan remain long term risks.
Return on Invested Capital (ROIC):
Traditional ROIC measures are difficult to apply to banks because capital is defined largely by regulatory requirements rather than operating assets. The closest economic equivalent is return on equity relative to the cost of equity.
UBS currently produces approximately 10.81 percent return on equity. Under an excess returns framework, the company generates economic profit above its estimated cost of equity, producing roughly CHF0.64 per share in excess returns.
This indicates the bank is creating value, though the margin is not particularly wide. Banks that earn only modestly above their cost of equity can see that advantage disappear quickly during downturns.
Historically, wealth management has been relatively capital light compared with lending or trading operations. Revenue scales primarily with client assets under management rather than balance sheet growth.
The Credit Suisse integration complicates that picture. The combined bank must support a larger balance sheet and maintain stronger regulatory capital buffers. UBS has also announced plans to invest roughly two billion dollars in operational improvements starting in 2026.
Those investments are intended to improve efficiency and reduce the cost to income ratio. If they succeed, the larger platform could generate operating leverage and modestly improve returns on capital. If integration proves more challenging than expected, the expanded capital base could dilute returns.
Quality of Earnings:
Bank earnings often appear stronger than their underlying economics because accounting profits fluctuate with market conditions.
UBS reported strong profitability in recent results, including a substantial increase in quarterly net income. Trading activity and wealth management transaction income contributed to the improvement.
That said, earnings quality is closely tied to asset prices and client activity. Wealth management revenue rises and falls with assets under management and transaction volumes. In bull markets those figures naturally expand.
Free cash flow is also difficult to interpret for banks because balance sheet changes and regulatory capital adjustments distort the traditional definition used in industrial companies. Available data shows meaningful volatility in cash generation across recent periods.
For long term investors, the key issue is not quarterly profit but whether UBS can steadily grow client assets and retain advisory relationships. If those conditions hold, earnings should follow.
Capital Allocation Scorecard:
Capital allocation in banking generally revolves around four levers: dividends, share repurchases, acquisitions, and internal investment.
UBS currently pays a dividend yielding around 2.6 percent. Share repurchase activity appears limited in the available data, likely reflecting the need to conserve capital during the Credit Suisse integration.
The most consequential capital allocation decision was the acquisition of Credit Suisse. This was effectively a government supported rescue rather than a conventional strategic purchase. UBS acquired a major competitor and absorbed a large client base at an attractive price.
Strategically, the transaction strengthens the bank’s position in global wealth management. Financially, the long term outcome remains uncertain. Large bank integrations frequently promise synergies that take years to fully materialize.
The planned two billion dollar operational investment beginning in 2026 signals that management is still in the early stages of restructuring and platform integration.
Overall capital allocation grade: reasonable but unproven. The strategic logic is clear, but investors will need to see whether the integration ultimately produces durable economic returns.
Customer and Revenue Concentration:
Precise customer concentration metrics are not available in the dataset.
However, wealth management businesses naturally exhibit asset concentration. A relatively small number of ultra wealthy clients typically control a large share of total assets under management.
That creates a structural risk. If a handful of large families or institutional clients shift assets to competitors, fee revenue could decline materially even without broader client attrition.
Competitors include large U.S. private banks, global asset managers, and increasingly sophisticated family offices.
The integration of Credit Suisse introduces an additional risk window. Advisor departures or service disruptions during integration could trigger client outflows.
Management Alignment:
Leadership stability is especially important during large bank integrations.
UBS is led by CEO Sergio Ermotti, who previously ran the bank and returned to oversee the Credit Suisse integration. His earlier experience restructuring UBS during prior crises provides institutional knowledge that could reduce execution risk.
Detailed insider ownership and compensation alignment data is not available in the current dataset. In large financial institutions, compensation structures often emphasize short term performance metrics rather than long term capital returns.
As a result, investors will largely judge management on execution over the next several years.
10-Year Durability Test:
Looking out ten years forces investors to move beyond quarterly earnings and ask whether the competitive structure of the industry will still hold.
Wealth management appears structurally durable. Ultra wealthy families continue accumulating assets globally, and the growing complexity of cross border wealth planning increases demand for professional advisory services.
Several risks could affect UBS over a decade.
Regulatory pressure remains a constant for global systemically important banks. After the Credit Suisse merger, regulators may require higher capital buffers or impose tighter supervision.
Technology may gradually compress fees as digital investment platforms and algorithmic portfolio construction reduce costs and increase transparency.
Competition from large American wealth platforms continues to intensify, particularly in Asia and other international markets.
Despite these pressures, the core structure of global wealth management has remained stable for decades. Large trusted institutions still dominate the industry.
Predictability verdict: moderate. The franchise appears durable, but regulatory and macroeconomic forces introduce uncertainty.
Multi-Year Thesis (3 to 7 years):
Base Case Scenario:
Probability: 50 percent
Assumptions:
Credit Suisse integration proceeds successfully with moderate cost synergies.
Net wealth inflows remain positive.
Return on equity stabilizes around 10 to 11 percent.
Book value grows steadily as retained earnings accumulate.
Estimated intrinsic value:
Applying a normalized earnings multiple around 16 times forward earnings implies a value in the range of roughly 40 to 45 dollars per share.
Bull Case Scenario:
Probability: 25 percent
Assumptions:
Integration delivers stronger than expected cost savings.
Advisor productivity improves across the combined platform.
Wealth inflows accelerate in Asia and the Middle East.
Return on equity rises toward 14 to 15 percent.
Estimated intrinsic value:
High quality wealth managers can command valuation multiples closer to 20 times earnings, implying a potential value range of 55 to 60 dollars per share.
Bear Case Scenario:
Probability: 25 percent
Assumptions:
Client attrition occurs during the integration process.
Regulatory capital requirements increase.
Return on equity declines toward 7 to 8 percent typical for European banks during weak cycles.
Estimated intrinsic value:
Banks with sub 10 percent returns typically trade closer to 12 times earnings, implying a value range around 25 to 30 dollars per share.
The probability weighted intrinsic value from these scenarios clusters around the low 40 dollar range, which sits very close to the current market price.
Margin of Safety Verdict:
Intrinsic value estimates suggest UBS trades approximately at fair value and possibly slightly above depending on assumptions.
Value investors typically require at least a 20 percent discount to intrinsic value before purchasing a stock.
That discount is not present here.
As a result, the investment case rests primarily on successful execution of the Credit Suisse integration rather than on buying a clearly mispriced asset.
From a strict value perspective, UBS belongs on a watchlist rather than in a portfolio at the current price.
Peak Margin Stress Test:
Current profitability may represent a relatively favorable point in the cycle.
If return on equity declines from roughly 10.8 percent toward 7 percent during weaker capital markets conditions, earnings would fall meaningfully.
At the same time, valuation multiples for banks could compress toward 12 to 14 times earnings.
A simultaneous decline in earnings and valuation multiples could plausibly produce downside of roughly 30 to 45 percent in a severe stress scenario.
Valuation Framing:
Several valuation perspectives help frame the current price.
Relative valuation shows UBS trading around 21 times earnings, modestly above the capital markets industry average but below some global wealth peers.
Forward earnings estimates imply a lower forward multiple near 10.7 times earnings, reflecting expectations for profit normalization after the integration.
Excess return models indicate the stock trades about 2.9 percent above estimated intrinsic value.
Taken together, the market appears to be pricing UBS as a successful consolidation story capable of generating steady double digit returns.
Perception vs Reality:
Perception: UBS has emerged from the Credit Suisse crisis as the undisputed leader in global wealth management.
Reality: the integration process is still underway and may take several years before the final economics become fully visible.
Perception: wealth management delivers highly stable fee income.
Reality: revenues remain closely tied to asset prices and investor activity.
Why This May Be Misunderstood:
Many investors underestimate how complex large bank mergers can be. Cultural differences, advisor turnover, and system integration challenges can quietly erode the benefits that looked straightforward on paper.
At the same time, the market may underestimate the long term strategic value of scale if UBS successfully consolidates its leadership position in global wealth management.
The debate is therefore not about whether UBS is a strong bank. It clearly is.
The real question is whether that strength is already reflected in the stock price.
Three Measurable Things to Watch Next Quarter:
Investors should watch net asset inflows in the global wealth management division, since sustained inflows would signal client retention and confidence following the Credit Suisse integration.
Another important indicator is improvement in the cost to income ratio. Evidence of cost synergies would confirm that the merger is producing operating leverage.
Return on equity trends will also matter. Sustained movement toward mid teen returns would support a higher valuation multiple.
Historical Conviction Drift:
Investor sentiment toward UBS has shifted sharply over the past several years.
The stock has risen approximately 36 percent over the past year, more than 120 percent over three years, and roughly 277 percent over five years.
Earlier skepticism toward European banks has gradually given way to optimism around consolidation and wealth management growth.
A large portion of the re rating in UBS’s valuation reflects this change in narrative.
Disconfirming Evidence:
The strongest argument against owning UBS is straightforward.
Large global banks have historically struggled to maintain returns on equity above their cost of capital over long economic cycles.
If UBS’s profitability eventually settles in the 7 to 9 percent range that is common among European banks, today’s valuation multiple would appear generous.
Integration risk related to Credit Suisse also remains significant and could expose unexpected liabilities or client outflows.
Risks:
Integration failure related to legacy Credit Suisse assets or cultural conflicts remains a possibility. Client asset outflows could occur during advisor or platform transitions. Higher regulatory capital requirements could reduce returns on equity. A global equity market downturn could reduce assets under management. Fee compression from passive investment products and digital advisory platforms could also pressure long term profitability.
Summary:
UBS represents a high quality global wealth management franchise strengthened by the consolidation of Swiss banking following the Credit Suisse rescue.
The business benefits from scale, reputation, and switching costs that make client relationships relatively durable.
However, the current stock price already reflects considerable optimism around integration success and steady profitability.
Without a meaningful margin of safety, UBS currently looks more like a strong business trading at a reasonable price than a clear bargain.
Value investors may prefer to wait for either a lower entry price or clearer evidence that returns on equity can sustainably exceed current expectations.
Data Snapshot:
Metric | Value
Metric: Value
Current Price (UBS): $42.10
Market Capitalization: $130.16 billion
Shares Outstanding: 3,091,699,191
Trailing P/E: 17.84x
Forward P/E: 10.68x
Enterprise Value (EV): $198.16 billion
EV/EBITDA: N/A
Revenue (TTM): $49.60 billion
Gross Margin: 0.00%
Operating Margin: 54.64%
Free Cash Flow (FCF): N/A
FCF Yield: N/A
52-Week Range: $29.73 to $49.36
Sector: Financial Services
Industry: Banks - Diversified
References:
1. Yahoo Finance. What Does UBS Stock’s 36% Jump and Credit Suisse Integration Mean for Its Value? finance.yahoo.com/news/does-ubs-stock-36-jump-111112858.html
2. Yahoo Finance. UBS: Target investing $2 billion to execute turnaround in 2026. finance.yahoo.com/news/ubs-target-investing-2-billion-144822932.html
3. Yahoo Finance. UBS Raises Price Target on Vistra (VST) to $233 After Meta Nuclear Power Deal. finance.yahoo.com/news/ubs-raises-price-target-vistra-202230220.html
4. Yahoo Finance. Looking At The UDR Narrative As Analyst Views And Fair Value Gradually Shift. finance.yahoo.com/news/looking-udr-narrative-analyst-views-160650096.html
5. Yahoo Finance. UBS Sees Yuan's Global Reserve Share Rising as Investors Reassess US Assets. finance.yahoo.com/news/ubs-sees-yuans-global-share-181340799.html
6. Yahoo Finance. Gold to $5,000? What Bank of America and UBS Have to Say. finance.yahoo.com/news/gold-5-000-bank-america-135100493.html
7. Wall Street Journal. UBS Gets Everything It Wants From Credit Suisse. wsj.com/finance/banking/ubs-gets-everything-it-wants-from-credit-suisse-7a4f8328
8. Yahoo Finance. How The PulteGroup (PHM) Story Is Evolving As Fair Value And Street Views Shift. finance.yahoo.com/news/pultegroup-phm-story-evolving-fair-080658164.html
9. Yahoo Finance. Investors question gold’s safe-haven status as prices fall. ca.finance.yahoo.com/news/investors-gold-safe-haven-status-113209414.html
10. Yahoo Finance. UBS Cuts ServiceNow to Neutral With a $100 Target: Yesterday’s Selloff Was Just the Beginning? finance.yahoo.com/markets/stocks/articles/ubs-cuts-servicenow-neutral-100-125737103.html
11. Yahoo Finance. How The SBA Communications (SBAC) Investment Story Is Evolving With Mixed Analyst Signals. finance.yahoo.com/markets/stocks/articles/sba-communications-sbac-investment-story-181250674.html
12. Yahoo Finance. How The Blue Owl Capital (OWL) Narrative Is Shifting As Analysts Reset Expectations. finance.yahoo.com/news/blue-owl-capital-owl-narrative-151226281.html
13. Yahoo Finance. How The RTX (RTX) Investment Story Is Shifting As Analysts Reassess Risk And Upside. finance.yahoo.com/markets/stocks/articles/rtx-rtx-investment-story-shifting-030944129.html
14. Yahoo Finance. How The McDonald's (MCD) Investment Story Is Shifting As Analysts Rework Growth And Valuation. finance.yahoo.com/markets/stocks/articles/mcdonalds-mcd-investment-story-shifting-190443882.html
15. Yahoo Finance. How Recent Street Shifts Are Rewriting Ares Management's Valuation Story. finance.yahoo.com/news/recent-street-shifts-rewriting-ares-130618455.html
16. Yahoo Finance. What Analysts Think Is Quietly Reshaping The Blackstone (BX) Story Now. finance.yahoo.com/news/analysts-think-quietly-reshaping-blackstone-090727902.html
17. Finance Yahoo syndication reference for UBS valuation discussion. finance.yahoo.com/news/does-ubs-stock-36-jump-111112858.html
18. Finance Yahoo reference for UBS macro outlook commentary. finance.yahoo.com/news/gold-5-000-bank-america-135100493.html
19. Finance Yahoo reference for UBS currency and reserve outlook. finance.yahoo.com/news/ubs-sees-yuans-global-share-181340799.html
20. CryptoBanterGroup YouTube Channel. Discussion mentioning UBS and institutional adoption of real world asset platforms. youtube.com/watch?v=KZ13-O9_u3I
Disclaimer:
This analysis is for informational purposes only and should not be considered investment advice. Investors should conduct their own research and consider their financial circumstances before making investment decisions.
UBS today stands as one of the strongest global wealth management franchises, reinforced by the absorption of Credit Suisse and the enduring strength of the Swiss safe haven brand. The underlying business looks durable and capable of compounding book value over time. However, the stock currently trades close to estimated intrinsic value. Margin of safety verdict: insufficient. At today’s price, the analysis is informative from an intellectual standpoint but does not present an actionable value investment.
One Stock, Dozens of Voices:
This is not the view of a single analyst. CrowdWisdom aggregated 32 independent sources for UBS (20 financial research articles (web); 11 prior CrowdWisdom analysis snapshots (internal archive); 1 verified financial data checks (Yahoo Finance)) and distilled the shared thesis: where dozens of traders, investors, and researchers broadly agree, where their views diverge, and what the market may be overlooking.
Those perspectives were then pressure-tested by setting opposing arguments against each other. The process examined a bull case, a bear case that challenges the consensus, and a review of what expectations are already embedded in the current price. All financial metrics were cross-validated against live market data.
The sections that follow highlight where opinion converges, where it breaks apart, and whether the stock offers any real margin of safety at today’s price.
Business Quality and Moat Durability:
UBS operates at the center of global private banking. Its core engine is wealth management serving high net worth and ultra high net worth clients across Europe, Asia, and the Americas.
Three structural advantages underpin the business.
The first is global scale. Wealth management demands large advisory teams, deep investment product infrastructure, extensive regulatory compliance capabilities, and international tax expertise. Building a platform of this kind takes decades. The Credit Suisse acquisition dramatically expanded UBS’s client assets and advisory capacity, strengthening its global reach.
The second advantage is reputation. Swiss banking has long been associated with stability and discretion. For wealthy families managing multigenerational capital, trust often carries as much weight as pricing. UBS benefits from that intangible asset in a way many competitors cannot easily replicate.
The third is switching friction. Ultra wealthy clients typically maintain diversified portfolios structured through trusts, estate plans, cross border tax arrangements, and bespoke investment mandates. Moving those structures to another institution can take months and introduces operational risk. As a result, client relationships tend to be sticky.
The integration of Credit Suisse further strengthens the competitive position. UBS effectively removed its largest domestic competitor while absorbing a large base of wealth clients and advisors.
At present, the moat appears stable with the possibility of modest expansion. Consolidation has increased scale. However, fee pressure from passive investing and aggressive competition from American wealth platforms such as Morgan Stanley and JPMorgan remain long term risks.
Return on Invested Capital (ROIC):
Traditional ROIC measures are difficult to apply to banks because capital is defined largely by regulatory requirements rather than operating assets. The closest economic equivalent is return on equity relative to the cost of equity.
UBS currently produces approximately 10.81 percent return on equity. Under an excess returns framework, the company generates economic profit above its estimated cost of equity, producing roughly CHF0.64 per share in excess returns.
This indicates the bank is creating value, though the margin is not particularly wide. Banks that earn only modestly above their cost of equity can see that advantage disappear quickly during downturns.
Historically, wealth management has been relatively capital light compared with lending or trading operations. Revenue scales primarily with client assets under management rather than balance sheet growth.
The Credit Suisse integration complicates that picture. The combined bank must support a larger balance sheet and maintain stronger regulatory capital buffers. UBS has also announced plans to invest roughly two billion dollars in operational improvements starting in 2026.
Those investments are intended to improve efficiency and reduce the cost to income ratio. If they succeed, the larger platform could generate operating leverage and modestly improve returns on capital. If integration proves more challenging than expected, the expanded capital base could dilute returns.
Quality of Earnings:
Bank earnings often appear stronger than their underlying economics because accounting profits fluctuate with market conditions.
UBS reported strong profitability in recent results, including a substantial increase in quarterly net income. Trading activity and wealth management transaction income contributed to the improvement.
That said, earnings quality is closely tied to asset prices and client activity. Wealth management revenue rises and falls with assets under management and transaction volumes. In bull markets those figures naturally expand.
Free cash flow is also difficult to interpret for banks because balance sheet changes and regulatory capital adjustments distort the traditional definition used in industrial companies. Available data shows meaningful volatility in cash generation across recent periods.
For long term investors, the key issue is not quarterly profit but whether UBS can steadily grow client assets and retain advisory relationships. If those conditions hold, earnings should follow.
Capital Allocation Scorecard:
Capital allocation in banking generally revolves around four levers: dividends, share repurchases, acquisitions, and internal investment.
UBS currently pays a dividend yielding around 2.6 percent. Share repurchase activity appears limited in the available data, likely reflecting the need to conserve capital during the Credit Suisse integration.
The most consequential capital allocation decision was the acquisition of Credit Suisse. This was effectively a government supported rescue rather than a conventional strategic purchase. UBS acquired a major competitor and absorbed a large client base at an attractive price.
Strategically, the transaction strengthens the bank’s position in global wealth management. Financially, the long term outcome remains uncertain. Large bank integrations frequently promise synergies that take years to fully materialize.
The planned two billion dollar operational investment beginning in 2026 signals that management is still in the early stages of restructuring and platform integration.
Overall capital allocation grade: reasonable but unproven. The strategic logic is clear, but investors will need to see whether the integration ultimately produces durable economic returns.
Customer and Revenue Concentration:
Precise customer concentration metrics are not available in the dataset.
However, wealth management businesses naturally exhibit asset concentration. A relatively small number of ultra wealthy clients typically control a large share of total assets under management.
That creates a structural risk. If a handful of large families or institutional clients shift assets to competitors, fee revenue could decline materially even without broader client attrition.
Competitors include large U.S. private banks, global asset managers, and increasingly sophisticated family offices.
The integration of Credit Suisse introduces an additional risk window. Advisor departures or service disruptions during integration could trigger client outflows.
Management Alignment:
Leadership stability is especially important during large bank integrations.
UBS is led by CEO Sergio Ermotti, who previously ran the bank and returned to oversee the Credit Suisse integration. His earlier experience restructuring UBS during prior crises provides institutional knowledge that could reduce execution risk.
Detailed insider ownership and compensation alignment data is not available in the current dataset. In large financial institutions, compensation structures often emphasize short term performance metrics rather than long term capital returns.
As a result, investors will largely judge management on execution over the next several years.
10-Year Durability Test:
Looking out ten years forces investors to move beyond quarterly earnings and ask whether the competitive structure of the industry will still hold.
Wealth management appears structurally durable. Ultra wealthy families continue accumulating assets globally, and the growing complexity of cross border wealth planning increases demand for professional advisory services.
Several risks could affect UBS over a decade.
Regulatory pressure remains a constant for global systemically important banks. After the Credit Suisse merger, regulators may require higher capital buffers or impose tighter supervision.
Technology may gradually compress fees as digital investment platforms and algorithmic portfolio construction reduce costs and increase transparency.
Competition from large American wealth platforms continues to intensify, particularly in Asia and other international markets.
Despite these pressures, the core structure of global wealth management has remained stable for decades. Large trusted institutions still dominate the industry.
Predictability verdict: moderate. The franchise appears durable, but regulatory and macroeconomic forces introduce uncertainty.
Multi-Year Thesis (3 to 7 years):
Base Case Scenario:
Probability: 50 percent
Assumptions:
Credit Suisse integration proceeds successfully with moderate cost synergies.
Net wealth inflows remain positive.
Return on equity stabilizes around 10 to 11 percent.
Book value grows steadily as retained earnings accumulate.
Estimated intrinsic value:
Applying a normalized earnings multiple around 16 times forward earnings implies a value in the range of roughly 40 to 45 dollars per share.
Bull Case Scenario:
Probability: 25 percent
Assumptions:
Integration delivers stronger than expected cost savings.
Advisor productivity improves across the combined platform.
Wealth inflows accelerate in Asia and the Middle East.
Return on equity rises toward 14 to 15 percent.
Estimated intrinsic value:
High quality wealth managers can command valuation multiples closer to 20 times earnings, implying a potential value range of 55 to 60 dollars per share.
Bear Case Scenario:
Probability: 25 percent
Assumptions:
Client attrition occurs during the integration process.
Regulatory capital requirements increase.
Return on equity declines toward 7 to 8 percent typical for European banks during weak cycles.
Estimated intrinsic value:
Banks with sub 10 percent returns typically trade closer to 12 times earnings, implying a value range around 25 to 30 dollars per share.
The probability weighted intrinsic value from these scenarios clusters around the low 40 dollar range, which sits very close to the current market price.
Margin of Safety Verdict:
Intrinsic value estimates suggest UBS trades approximately at fair value and possibly slightly above depending on assumptions.
Value investors typically require at least a 20 percent discount to intrinsic value before purchasing a stock.
That discount is not present here.
As a result, the investment case rests primarily on successful execution of the Credit Suisse integration rather than on buying a clearly mispriced asset.
From a strict value perspective, UBS belongs on a watchlist rather than in a portfolio at the current price.
Peak Margin Stress Test:
Current profitability may represent a relatively favorable point in the cycle.
If return on equity declines from roughly 10.8 percent toward 7 percent during weaker capital markets conditions, earnings would fall meaningfully.
At the same time, valuation multiples for banks could compress toward 12 to 14 times earnings.
A simultaneous decline in earnings and valuation multiples could plausibly produce downside of roughly 30 to 45 percent in a severe stress scenario.
Valuation Framing:
Several valuation perspectives help frame the current price.
Relative valuation shows UBS trading around 21 times earnings, modestly above the capital markets industry average but below some global wealth peers.
Forward earnings estimates imply a lower forward multiple near 10.7 times earnings, reflecting expectations for profit normalization after the integration.
Excess return models indicate the stock trades about 2.9 percent above estimated intrinsic value.
Taken together, the market appears to be pricing UBS as a successful consolidation story capable of generating steady double digit returns.
Perception vs Reality:
Perception: UBS has emerged from the Credit Suisse crisis as the undisputed leader in global wealth management.
Reality: the integration process is still underway and may take several years before the final economics become fully visible.
Perception: wealth management delivers highly stable fee income.
Reality: revenues remain closely tied to asset prices and investor activity.
Why This May Be Misunderstood:
Many investors underestimate how complex large bank mergers can be. Cultural differences, advisor turnover, and system integration challenges can quietly erode the benefits that looked straightforward on paper.
At the same time, the market may underestimate the long term strategic value of scale if UBS successfully consolidates its leadership position in global wealth management.
The debate is therefore not about whether UBS is a strong bank. It clearly is.
The real question is whether that strength is already reflected in the stock price.
Three Measurable Things to Watch Next Quarter:
Investors should watch net asset inflows in the global wealth management division, since sustained inflows would signal client retention and confidence following the Credit Suisse integration.
Another important indicator is improvement in the cost to income ratio. Evidence of cost synergies would confirm that the merger is producing operating leverage.
Return on equity trends will also matter. Sustained movement toward mid teen returns would support a higher valuation multiple.
Historical Conviction Drift:
Investor sentiment toward UBS has shifted sharply over the past several years.
The stock has risen approximately 36 percent over the past year, more than 120 percent over three years, and roughly 277 percent over five years.
Earlier skepticism toward European banks has gradually given way to optimism around consolidation and wealth management growth.
A large portion of the re rating in UBS’s valuation reflects this change in narrative.
Disconfirming Evidence:
The strongest argument against owning UBS is straightforward.
Large global banks have historically struggled to maintain returns on equity above their cost of capital over long economic cycles.
If UBS’s profitability eventually settles in the 7 to 9 percent range that is common among European banks, today’s valuation multiple would appear generous.
Integration risk related to Credit Suisse also remains significant and could expose unexpected liabilities or client outflows.
Risks:
Integration failure related to legacy Credit Suisse assets or cultural conflicts remains a possibility. Client asset outflows could occur during advisor or platform transitions. Higher regulatory capital requirements could reduce returns on equity. A global equity market downturn could reduce assets under management. Fee compression from passive investment products and digital advisory platforms could also pressure long term profitability.
Summary:
UBS represents a high quality global wealth management franchise strengthened by the consolidation of Swiss banking following the Credit Suisse rescue.
The business benefits from scale, reputation, and switching costs that make client relationships relatively durable.
However, the current stock price already reflects considerable optimism around integration success and steady profitability.
Without a meaningful margin of safety, UBS currently looks more like a strong business trading at a reasonable price than a clear bargain.
Value investors may prefer to wait for either a lower entry price or clearer evidence that returns on equity can sustainably exceed current expectations.
Data Snapshot:
Metric | Value
Metric: Value
Current Price (UBS): $42.10
Market Capitalization: $130.16 billion
Shares Outstanding: 3,091,699,191
Trailing P/E: 17.84x
Forward P/E: 10.68x
Enterprise Value (EV): $198.16 billion
EV/EBITDA: N/A
Revenue (TTM): $49.60 billion
Gross Margin: 0.00%
Operating Margin: 54.64%
Free Cash Flow (FCF): N/A
FCF Yield: N/A
52-Week Range: $29.73 to $49.36
Sector: Financial Services
Industry: Banks - Diversified
References:
1. Yahoo Finance. What Does UBS Stock’s 36% Jump and Credit Suisse Integration Mean for Its Value? finance.yahoo.com/news/does-ubs-stock-36-jump-111112858.html
2. Yahoo Finance. UBS: Target investing $2 billion to execute turnaround in 2026. finance.yahoo.com/news/ubs-target-investing-2-billion-144822932.html
3. Yahoo Finance. UBS Raises Price Target on Vistra (VST) to $233 After Meta Nuclear Power Deal. finance.yahoo.com/news/ubs-raises-price-target-vistra-202230220.html
4. Yahoo Finance. Looking At The UDR Narrative As Analyst Views And Fair Value Gradually Shift. finance.yahoo.com/news/looking-udr-narrative-analyst-views-160650096.html
5. Yahoo Finance. UBS Sees Yuan's Global Reserve Share Rising as Investors Reassess US Assets. finance.yahoo.com/news/ubs-sees-yuans-global-share-181340799.html
6. Yahoo Finance. Gold to $5,000? What Bank of America and UBS Have to Say. finance.yahoo.com/news/gold-5-000-bank-america-135100493.html
7. Wall Street Journal. UBS Gets Everything It Wants From Credit Suisse. wsj.com/finance/banking/ubs-gets-everything-it-wants-from-credit-suisse-7a4f8328
8. Yahoo Finance. How The PulteGroup (PHM) Story Is Evolving As Fair Value And Street Views Shift. finance.yahoo.com/news/pultegroup-phm-story-evolving-fair-080658164.html
9. Yahoo Finance. Investors question gold’s safe-haven status as prices fall. ca.finance.yahoo.com/news/investors-gold-safe-haven-status-113209414.html
10. Yahoo Finance. UBS Cuts ServiceNow to Neutral With a $100 Target: Yesterday’s Selloff Was Just the Beginning? finance.yahoo.com/markets/stocks/articles/ubs-cuts-servicenow-neutral-100-125737103.html
11. Yahoo Finance. How The SBA Communications (SBAC) Investment Story Is Evolving With Mixed Analyst Signals. finance.yahoo.com/markets/stocks/articles/sba-communications-sbac-investment-story-181250674.html
12. Yahoo Finance. How The Blue Owl Capital (OWL) Narrative Is Shifting As Analysts Reset Expectations. finance.yahoo.com/news/blue-owl-capital-owl-narrative-151226281.html
13. Yahoo Finance. How The RTX (RTX) Investment Story Is Shifting As Analysts Reassess Risk And Upside. finance.yahoo.com/markets/stocks/articles/rtx-rtx-investment-story-shifting-030944129.html
14. Yahoo Finance. How The McDonald's (MCD) Investment Story Is Shifting As Analysts Rework Growth And Valuation. finance.yahoo.com/markets/stocks/articles/mcdonalds-mcd-investment-story-shifting-190443882.html
15. Yahoo Finance. How Recent Street Shifts Are Rewriting Ares Management's Valuation Story. finance.yahoo.com/news/recent-street-shifts-rewriting-ares-130618455.html
16. Yahoo Finance. What Analysts Think Is Quietly Reshaping The Blackstone (BX) Story Now. finance.yahoo.com/news/analysts-think-quietly-reshaping-blackstone-090727902.html
17. Finance Yahoo syndication reference for UBS valuation discussion. finance.yahoo.com/news/does-ubs-stock-36-jump-111112858.html
18. Finance Yahoo reference for UBS macro outlook commentary. finance.yahoo.com/news/gold-5-000-bank-america-135100493.html
19. Finance Yahoo reference for UBS currency and reserve outlook. finance.yahoo.com/news/ubs-sees-yuans-global-share-181340799.html
20. CryptoBanterGroup YouTube Channel. Discussion mentioning UBS and institutional adoption of real world asset platforms. youtube.com/watch?v=KZ13-O9_u3I
Disclaimer:
This analysis is for informational purposes only and should not be considered investment advice. Investors should conduct their own research and consider their financial circumstances before making investment decisions.

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.