
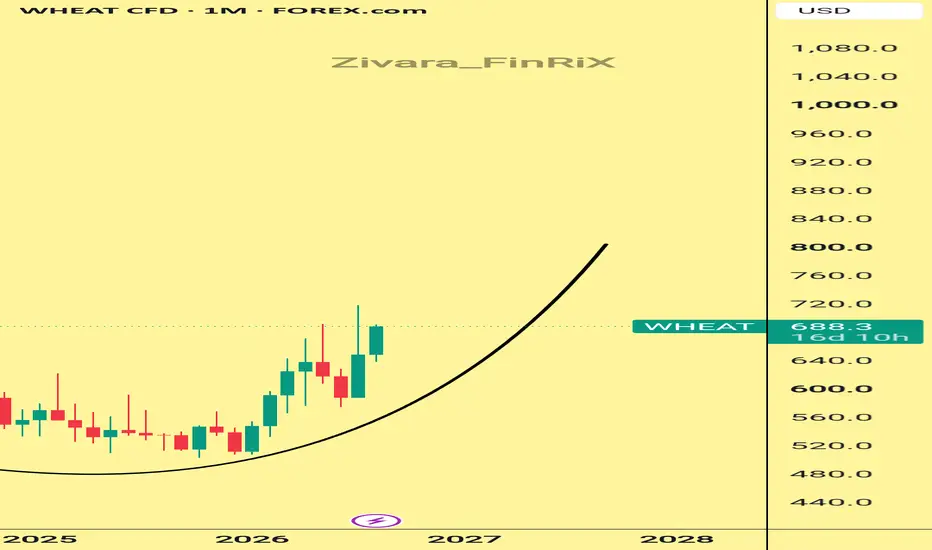
War in Black Sea drives up world wheat prices
The US Department of Agriculture has reduced its forecasts for Russian and Ukrainian grain exports because of the Black Sea shipping war, and every rival exporter’s price has gone up.
The department's monthly Grain
World Markets and Trade report, published on August 12 by its Foreign Agricultural Service, cuts Russia's 2026/27 wheat exports to 46mn tonnes and Ukraine's to 13.5mn, blaming disruption to Black Sea shipping since hostilities intensified in mid-July.
The report's own headline is elsewhere - EU grain imports rising and exports falling on the back of a crop wrecked by heat and drought - but the two findings are the same story from opposite ends.
Grain trade has spent four years being reshaped by this war, and this is the month the price data caught up with the shipping data. Russia has been the world's cheapest large wheat seller throughout; in August it is discounting while everyone else raises quotes, because a discount is worth nothing if the cargo cannot leave Novorossiysk. All three of that port's big grain terminals stopped work this week.
Since the July estimates, wheat export quotes rose sharply among every major exporter apart from Russia. Russian quotes fell $3 a tonne to $224 on early harvest pressure and mounting supplies with some export routes inaccessible.
EU quotes jumped $25 to $262 a tonne on expected import demand despite a much smaller crop; US quotes rose $26 to $321, Canadian $20 to $292, Australian $13 to $291 and Argentine $12 to $239 - still the next most competitive after Russia. The US season-average farm price was raised 20 cents to $6.20 a bushel.
A seller with the world's cheapest wheat and no way to load it is not a price-setter. Russia is discounting into a market that is repricing upward around it, which is the clearest measure yet of what the port campaign has cost Moscow.
The department cut Russian wheat exports for 2026/27 by 1.5mn tonnes to 46mn, citing "disruptions in the Black Sea hindering shipments, especially from ports in the Sea of Azov", and Ukraine's by 1mn tonnes to 13.5mn, on disruption to its deep seaports. Kazakhstan and Canada picked up 1mn tonnes each, to 10mn and 28.5mn.
EU wheat and coarse grain production for 2026/27 is now forecast at 264.8mn tonnes, down 8% on the year, after excessive heat and dryness through the late spring and summer cut yields on wheat and barley. Corn is forecast at 50.2mn tonnes - which would be the smallest EU corn crop in nearly 20 years.
EU corn imports are raised 1mn tonnes to 23.5mn as a result, and its own corn exports cut to 1.6mn. Barley exports, at 9.1mn tonnes in 2025/26 and the highest since 2015/16, are forecast to fall 19%.
Filling that gap is harder than it looks. Ukraine, normally a top corn supplier to the EU, is dealing with the same Black Sea shipping disruption; Brazil's exports have started slowly despite a record crop, as domestic biofuel demand absorbs the corn; and Ukrainian wheat into the bloc is still constrained by EU import policy, particularly for the Visegrad Group. The department notes significant recent EU purchases of US corn instead
The US Department of Agriculture has reduced its forecasts for Russian and Ukrainian grain exports because of the Black Sea shipping war, and every rival exporter’s price has gone up.
The department's monthly Grain
World Markets and Trade report, published on August 12 by its Foreign Agricultural Service, cuts Russia's 2026/27 wheat exports to 46mn tonnes and Ukraine's to 13.5mn, blaming disruption to Black Sea shipping since hostilities intensified in mid-July.
The report's own headline is elsewhere - EU grain imports rising and exports falling on the back of a crop wrecked by heat and drought - but the two findings are the same story from opposite ends.
Grain trade has spent four years being reshaped by this war, and this is the month the price data caught up with the shipping data. Russia has been the world's cheapest large wheat seller throughout; in August it is discounting while everyone else raises quotes, because a discount is worth nothing if the cargo cannot leave Novorossiysk. All three of that port's big grain terminals stopped work this week.
Since the July estimates, wheat export quotes rose sharply among every major exporter apart from Russia. Russian quotes fell $3 a tonne to $224 on early harvest pressure and mounting supplies with some export routes inaccessible.
EU quotes jumped $25 to $262 a tonne on expected import demand despite a much smaller crop; US quotes rose $26 to $321, Canadian $20 to $292, Australian $13 to $291 and Argentine $12 to $239 - still the next most competitive after Russia. The US season-average farm price was raised 20 cents to $6.20 a bushel.
A seller with the world's cheapest wheat and no way to load it is not a price-setter. Russia is discounting into a market that is repricing upward around it, which is the clearest measure yet of what the port campaign has cost Moscow.
The department cut Russian wheat exports for 2026/27 by 1.5mn tonnes to 46mn, citing "disruptions in the Black Sea hindering shipments, especially from ports in the Sea of Azov", and Ukraine's by 1mn tonnes to 13.5mn, on disruption to its deep seaports. Kazakhstan and Canada picked up 1mn tonnes each, to 10mn and 28.5mn.
EU wheat and coarse grain production for 2026/27 is now forecast at 264.8mn tonnes, down 8% on the year, after excessive heat and dryness through the late spring and summer cut yields on wheat and barley. Corn is forecast at 50.2mn tonnes - which would be the smallest EU corn crop in nearly 20 years.
EU corn imports are raised 1mn tonnes to 23.5mn as a result, and its own corn exports cut to 1.6mn. Barley exports, at 9.1mn tonnes in 2025/26 and the highest since 2015/16, are forecast to fall 19%.
Filling that gap is harder than it looks. Ukraine, normally a top corn supplier to the EU, is dealing with the same Black Sea shipping disruption; Brazil's exports have started slowly despite a record crop, as domestic biofuel demand absorbs the corn; and Ukrainian wheat into the bloc is still constrained by EU import policy, particularly for the Visegrad Group. The department notes significant recent EU purchases of US corn instead

Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.