NVDA: Do not buy hope before earningsNvidia reports earnings on 26 August after the U.S. close — results are expected around 20:20 UTC, with the conference call later around 21:00 UTC.
This is not just one stock report. Nvidia is a major part of the AI trade and represents roughly 8% of the S&P 500, so its results can affect NASDAQ, semiconductors, AI names, risk sentiment, and the broader market mood.
The psychology here is simple: the market wants a reason to believe again.
After recent pressure in tech, many traders are looking at NVDA and thinking: “If Nvidia beats, the AI trade is back.” That is where FOMO starts before the actual data.
But buying before earnings only because “Nvidia always delivers” is not analysis. It is hope.
The bar is already high. Analysts expect very strong growth, especially from data-center demand. But the market will not only watch revenue and EPS. It will watch guidance, margins, China risk, AI infrastructure demand, competition, and whether customers keep spending aggressively.
On the chart, NVDA is trying to stabilize near the 211–212 area, close to the 200 SMA. Resistance is higher near 227–228, where the previous high / breakout area sits.
That means the market is waiting between two emotions:
fear that the AI story is already priced in;
FOMO that earnings will restart the rally.
What I would do
If already long: I would reduce emotional risk before earnings and know my invalidation.
If not in: I would not chase before the report. I would wait for the reaction.
If price reclaims 216–220 after earnings, that would be the first sign buyers are trying to regain control.
If price loses the 211–212 area after earnings, it would show that buyers failed to defend the key support zone.
A stronger bullish reaction needs follow-through toward 227–228.
The main lesson: earnings are not a place to guess. They are a place to watch who gets trapped.
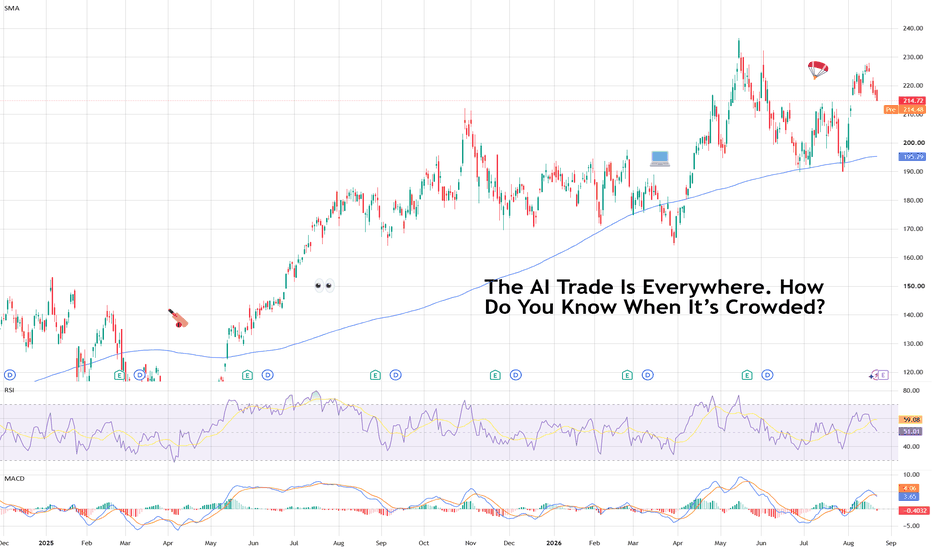
Personal market commentary, not financial advice. The AI Trade Is Everywhere. How Do You Know When It’s Crowded?Not too long ago, the AI trade meant buying Nvidia NASDAQ:NVDA and watching Jensen Huang explain why the world needed more GPUs.
Now artificial intelligence stretches across chipmakers, memory producers, cloud providers, data centers, utilities, nuclear power and almost anything capable of supplying electricity to a server rack.
Nvidia remains the obvious heavyweight, but the supporting cast has exploded. Micron NASDAQ:MU and Sandisk NASDAQ:SNDK have ridden extraordinary demand for memory. Obviously, it’s been reflected in the share price .
Nebius NASDAQ:NBIS and CoreWeave NASDAQ:CRWV are building AI cloud infrastructure at breakneck speed.
Power companies have become AI-adjacent because data centers need staggering amounts of electricity. We even watched Allbirds (now rebranded to Smartbirds NASDAQ:BIRD ) announce a pivot from wool sneakers toward AI compute infrastructure and briefly send its shares flying more than 500%. Only to fall back to pre-pop prices .
👥 Welcome to the Crowded Trade
That brings us to one of investing's more slippery concepts: the crowded trade.
A trade becomes crowded when large numbers of investors pile into the same asset, sector or investment thesis. Prices rise, attention grows and eventually everybody from hedge funds to your basketball group chat seems to own some version of the same idea.
But crowded and wrong mean different things. AI demand can remain enormous, Nvidia can keep selling mountains of chips and Nebius can continue signing billion-dollar contracts while the trade itself becomes increasingly crowded.
The risk comes from expectations. Once investors collectively expect extraordinary results (or realize they’ve taken things too far), delivering good results can feel disappointing. And that can hit the stock’s valuation.
📈 First Clue: Everything Keeps Going Up
Price action provides the most obvious warning. Consider the extraordinary moves across parts of the AI ecosystem. Nebius has multiplied several times over during the AI infrastructure boom.
Micron has enjoyed an enormous rally as memory prices surged, while Sandisk became an extreme example of investors chasing scarce memory capacity.
Big gains can reflect genuine improvements in a business. The interesting part begins when share prices start rising much faster than earnings, revenue or other metrics of fundamental performance.
Question for such times: Is the company truly in a fantastic shape with an upbeat outlook or is that mostly froth and speculation? Sometimes the answer is both. That's what makes this difficult.
💰 Second Clue: Valuations Start Assuming Perfection
Valuation offers another useful signal. A stock trading at a very high multiple of expected earnings isn't automatically expensive. Investors routinely pay premium prices for businesses expected to grow quickly.
The trouble arrives when today's price already assumes several years of exceptional growth.
Imagine analysts expect an AI company to double revenue. The stock rallies because investors anticipate that growth. Then the company reports revenue growth of 80%.
As much as 80% growth sounds fantastic in isolation. Against expectations for 100%, Wall Street may treat it like a total failure.
Crowded markets frequently produce this strange dynamic where excellent numbers generate mediocre stock reactions because investors had already priced in something even better.
🎯 Third Clue: Everyone Agrees, Even Your Barber
Consensus can become another useful temperature gauge. When analysts overwhelmingly recommend buying, earnings estimates keep rising, fund flows pour into the same sector and traders aggressively purchase call options, optimism may be approaching saturation.
Again, consensus can be correct. Markets sometimes recognize powerful structural trends early and continue rewarding them for years.
The issue is what happens when everyone who wants exposure already has it. Rising markets need incremental buyers, meaning someone willing to purchase at the next higher price.
When positioning becomes extremely crowded, that pool can shrink while the number of potential sellers grows. Suddenly, one disappointing earnings report can create a very crowded doorway.
😬 Being Right Can Still Hurt
Nebius recently provided a particularly useful lesson through (yes, you guessed it) investor Leopold Aschenbrenner.
His highly leveraged fund built major positions around the AI infrastructure boom, but severe losses triggered margin pressure and forced it to sell holdings, including Nebius, to Citadel.
Nebius subsequently rallied roughly 80% from his exit. Crowded trades can produce violent corrections precisely because many investors may be holding similar leveraged positions.
🛡️ So, Should You Avoid Crowded Trades?
Avoiding every popular investment would have kept traders away from some of history's greatest winners. The better approach is recognizing that crowding changes the risk equation.
Entry price becomes more important. Position size deserves greater attention. Leverage deserves considerably more respect. Earnings expectations matter alongside actual earnings (keep an eye on the Earnings Calendar ).
Most importantly, separate the company thesis from the stock thesis. A company can dominate its industry while its shares struggle because investors previously priced in even greater domination or something else entirely.
Off to you: What’s your way of knowing if a trade is overcrowded? Share your approach in the comments!  Education
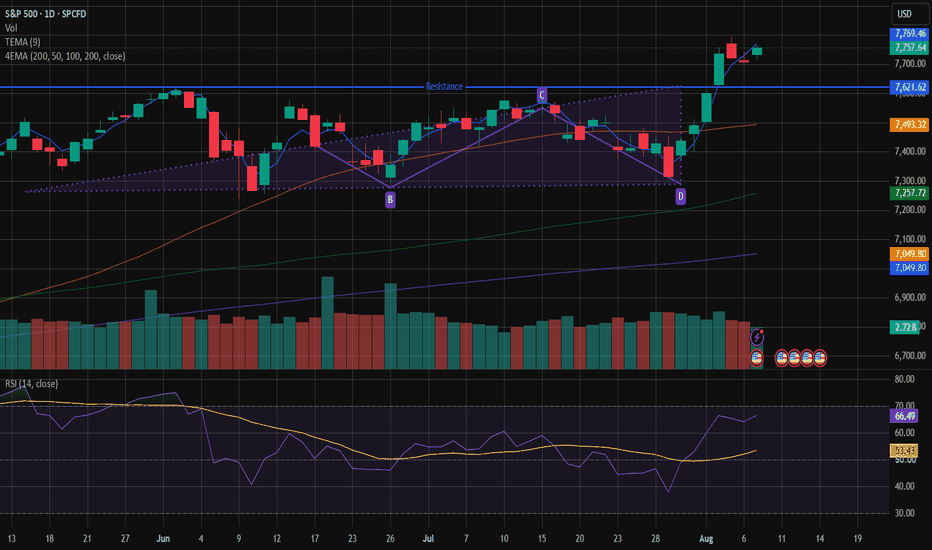
S&P 500: Jobs fell, market rose, triangle held!This video is an update on the S&P 500 trade setup that I put out on 7 August 2026, the day of the release of the July jobs report. The economy lost a shocking -23,000 jobs, the first negative jobs print in this cycle and contrary to expectations of +80,000 jobs, and the S&P 500 went on to close the session near record highs at 7,757. In this video, I discuss precisely how bad news turned good news for the stock market and how the decline in the Fed rate hike probability from 57% to 43.9% led to a 1.3% gain in the Nasdaq and an even stronger run for the semiconductor ETF to +7% on the week. Also discussed is how the ascending triangle breakout at 7,620 held even as the markets saw one of the worst data prints of the year. We discuss the updated trailing stop, the targets that are now achievable, and one statistic from the job report 921,000 temporary layoffs;that you need to watch out for in September.  Long
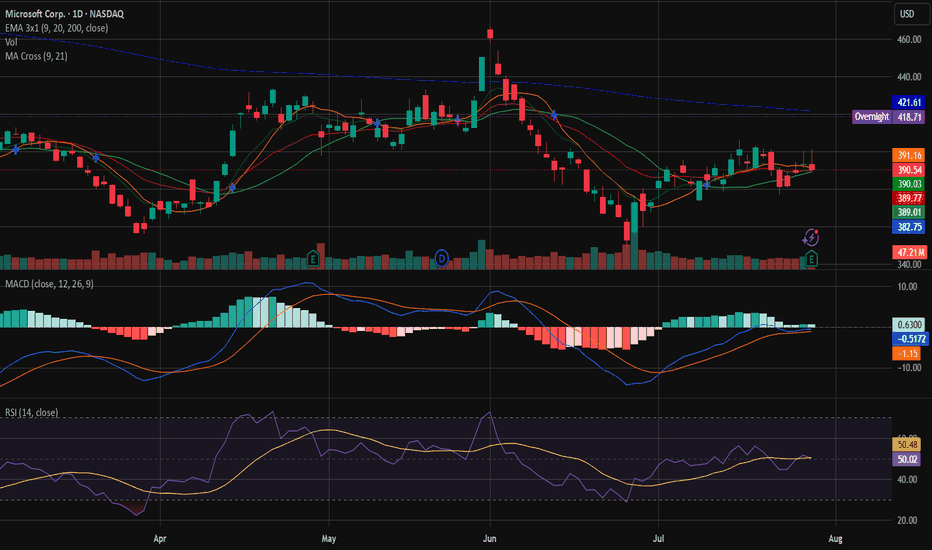
MSFT: Q4 earnings beat, Azure $100B, MACD breakout!The market had been discounting Microsoft for the past six months based on which last night’s earnings report is making this valuation very hard to justify. The stock closed on July 29 after reporting revenue of $90.01 billion in its fiscal Q4 2026, beating the $87.61 billion estimate from Wall Street by $2.4 billion while delivering an adjusted earnings per share of $4.74 instead of $4.24. This represents an 18% increase YOY, marking the second consecutive quarter of such revenue growth. Azure annual revenue surpassed $100 billion for the first time in the company's history, showing 41% growth for the entire fiscal year. Microsoft 365 Copilot gained more than 30 million paid seats from the 20 million reported in the previous quarter,the quickest enterprise AI adoption curve in the company's history. Net Income of $35.77 billion included a gain of $3.2 billion from the company’s investments in Anthropic and from the voluntary retirement plan that helped cut costs despite capital expenditure of $35.8 billion being more than double of the prior-year period. But the figure that got the stock to rally eight percent in after hours was not part of the earnings report. It was a sentence in CFO Amy Hood’s earnings call script: “Total calendar year 2026 capex guidance remains unchanged at $175 billion despite accounting policy change.” This was lower than the $190 billion feared by the Street and much lower than the $255-$260 billion fiscal 2027 capex forecast that has been hanging over the stock like a cloud since April. The Alphabet earnings template was not applicable here. Microsoft defied the mold. In doing so, it has taken off one major overhang that has weighed the stock twenty five percent down year-to-date despite 18% revenue growth.
The daily price was already starting to tell this tale even before yesterday’s confirmation came through. What the price action had been saying all along for weeks leading up to this print was of a stock establishing itself at a level much stronger than what its performance number actually said it was building a base around $382-$392 area with its short-term moving averages narrowing from above and not breaking down below its structural support line established since the June low points. The MACD had already given out its early stage bullish cross over before the earnings,histogram turning from negative to positive,just like how it happened with the Meta comeback and Hang Seng bounce in this same trade sequence I have written. As mentioned, it was the RSI holding just shy of the neutral fifty mark heading into earnings that was the chart hanging on by a thread and now with the after-hours move of eight percent, the tension in that chart is no more. What the chart needs to illustrate with its opening trade is a gapped move above the EMA cluster that has been topping out the price action since July, where both the EMA 9 and EMA 20 have been sitting within the $389 to $398 range, turning those resistance levels into support and opening up the run to the June highs of $421 and ultimately the $456 fifty-two week highs. The MACD histogram will gapped into positive territory with its opening trade, and the RSI will push past the 60 level for the first time since June.
Trade recommendation
Direction : Long;post-earnings breakout, buy the first pullback to the EMA cluster
Entry horizon : $415 – $422
Primary target : $456
Secondary target : $510
Stop loss : Daily close below $398
Technical scenarios
Bullish confirmation;Institutional rotation : Today's regular session validates the 8% after-hours surge as price reclaiming the EMA 9 and EMA 20 cluster on a closing basis triggers a decisive shift in sentiment. The MACD histogram, reflecting its first major positive expansion since May, signals that the momentum is structural rather than speculative. With 41 buy ratings already on the tape and a median target of $540, the street is beginning to re-rate this multiple from 20x forward earnings toward the 25–27x range that a 41% Azure growth rate and 30 million Copilot seats effectively mandate. A reclaim of the $456 fifty-two week high serves as the immediate objective, with the $510 secondary target coming into view as the market digests guidance for a 45% constant currency acceleration in Azure for fiscal 2027.
The gap-fill setup;Healthy absorption : The overnight move likely invites immediate profit-taking from event-driven traders, potentially driving price back toward the $415 to $422 support zone. Far from a reversal, this would represent a classic absorption of the gap before the broader institutional bid takes hold. Watch for the RSI to retreat toward 55 and the MACD histogram to compress; if volume on the dip remains below the opening surge, it confirms that institutions are accumulating into weakness. This zone offers the high-probability entry for those looking to avoid chasing the initial 8% volatility while positioning for the eventual continuation toward multi-year highs.
Bearish rejection;The capex overhang returns : Despite Microsoft holding its 2026 capex guidance steady, the $35.8 billion quarterly spend remains a massive figure that could re-ignite concerns if upcoming commentary hints at further upward revisions. We saw the Alphabet and Meta templates serve as warnings: even stellar growth can be eclipsed by spending anxieties. A failure to hold the gap, resulting in a daily close below the $398 EMA cluster, would invalidate the breakout and suggest that the market is not yet ready to abandon the capex discount. Until such a breakdown occurs, the technical structure remains firmly biased to the upside, treating the post-earnings gap as a new floor for the stock.
 Long
SPX Forecast: Key Levels to Watch as Earnings Season Kicks OffThe S&P 500 (SPX) has jumped 11% since the start of the year, boosted by ongoing enthusiasm for the AI trade and resilient consumer spending. As earnings season gets into full swing this week, with reports from major banks including Wells Fargo (WFC), Bank of America (BAC) and JPMorgan Chase (JPM), let's look at several technical levels worth watching.
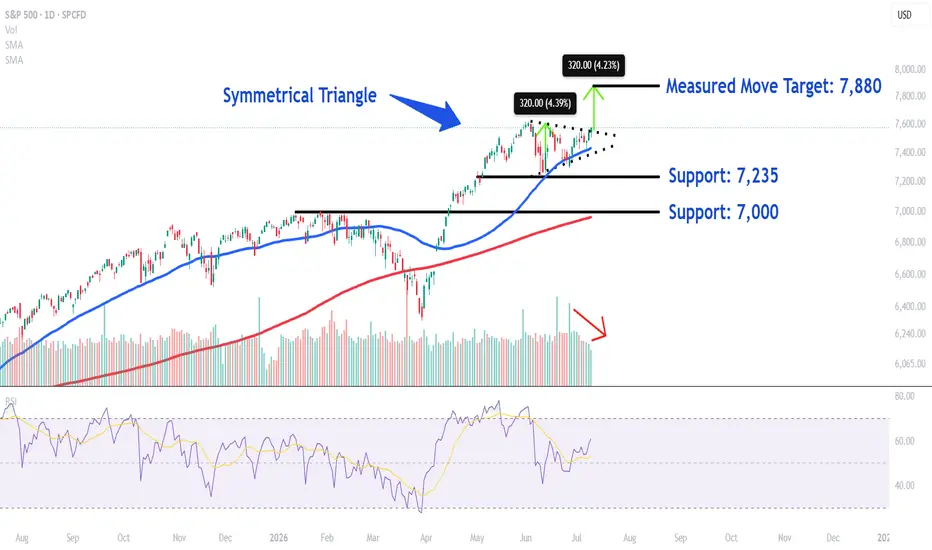
Firstly, a breakdown below a month-long symmetrical triangle opens the door to a retracement toward 7,235. This area may attract buying interest near a horizontal line that connects the low of the pattern with the opening price of a rare gravestone doji candlestick, which appeared on the chart in early May.
A close below this level could see the index test lower support around the phycological 7K area. This location would likely see bulls defend a series of peaks that formed throughout January and February near the rising 200 MA.
If the index breaks out above the symmetrical triangle, we can use a measured move to project a bullish target. In this case, we calculate the distance of the symmetrical triangle near its widest point and add that amount to the likely breakout area, which forecasts a target of 7,880. (320 + 7,560 = 7,880) Big Tech Rotation TradeFor most of the last three months, the market narrative has been simple: buy the companies building AI infrastructure.
But the chart below hints that the next trade may not be about *whether* AI spending continues — it may be about where that capital flows.
While the hyperscalers ( NASDAQ:MSFT , NASDAQ:AMZN , NASDAQ:GOOG , NASDAQ:META , NYSE:ORCL ) have gained a respectable 6% since March, semiconductors have absolutely exploded, with the NASDAQ:SOX basket up nearly 60%.
That move wasn't driven by one company alone. The biggest beneficiaries have been the names supplying the picks and shovels of the AI boom:
• Nvidia ( NASDAQ:NVDA ) — still the center of AI compute.
• AMD ( NASDAQ:AMD ) — increasingly competitive in AI accelerators and data center CPUs.
• Micron ( NASDAQ:MU ) — riding insatiable demand for HBM and memory.
• Broadcom ( NASDAQ:AVGO ) — powering networking and custom silicon.
• Intel ( NASDAQ:INTC ) — a more speculative bet on manufacturing and foundry capacity.
The question now is whether semis have simply outrun the customers writing the checks.
Hyperscalers are the ones deploying hundreds of billions into data centers, chips, networking, and power infrastructure. Microsoft, Amazon, Google, Meta, and Oracle ultimately monetize AI through cloud services, advertising, enterprise software, and compute rentals.
If AI capex remains elevated, semiconductors can continue to outperform.
But if investors begin asking when all of this spending translates into durable profits, we could see capital rotate back toward the hyperscalers that own the customer relationships and recurring revenue streams.
The AI trade isn't disappearing.
It may just be changing hands.
What do you think: are semis taking a breather, or is the next leg higher still ahead? 📈
 Short
Micron: An 820% rally walks into earnings does the trend hold?Micron Technology has been one of the single best stock performances of this cycle. Stocks have gained around 300% year-to-date and have increased by more than 820% in the last twelve months, closing Friday's trade up 8.70% at $1,133.99 following Rosenblatt, Stifel and Wedbush raising their price targets significantly, with Stifel's Brian Chin hiking his target to $1,500. This move has been driven by structure rather than speculation. AI-related demand is using up all existing memory production capacity, DRAM contract prices have been rising at double-digit rates during this quarter, and Micron is squarely in the middle of the high-bandwidth memory ramp-up for which every major AI accelerator needs. The thing to note in this situation is that the easy part of this story could be behind it. Micron is set to report its fiscal third-quarter financials after hours on Wednesday, 24 June just two trading days away and the Street expects revenues of $34.8 billion and earnings per share of $19.72. At this level of valuation, the market is not just rewarding good numbers anymore.
The price, however, is starting to send out a message that needs careful thought about it. Indeed, what the price action is saying is that the stock has done practically everything right technically-speaking, but it is already showing signs of being part of a trend that has struggled to gain its strength and needs a new impetus to continue with it. Indeed, the structure of the EMAs is still bullish as the price respects the EMA 9 and EMA 20 throughout the entire uptrend since May, while the EMA 200 is way behind , which is already indicative of how strong this trend has been compared to its longer term trend. The RSI also shows a very similar pattern that other charts have shown recently when breaking out as the RSI is still above the signal line, thus, signaling that buying pressure is still technically in control, but the spread between the two has shrunk significantly compared to May, when the RSI managed to rise above 70.This contraction represents what the chart is saying in its own language that the momentum is no longer accelerating as confidently as it did.The MACD line stays above the signal line, and thus, technically, the bullish scenario remains in place, although the histogram has contracted compared to the highs registered in May and in the first half of June, with a strong red candle on the early-June retracement. This is not a reversal signal. This is the price asking if the next leg up needs a shock from Wednesday’s report, and the answer will be known in two days.
Trade recommendation
Direction : Long
Entry horizon : $1,100 – $1,150
Primary target : $1,200
Secondary target : $1,500
Stop loss : $1,025
Technical scenarios
Beat-and-raise breakout : Micron exceeds revenue and EPS and raises guidance. RSI reclaims >70, MACD turns positive. Target $1,200+, with $1,300–$1,500 if guidance surprises.
In-line print, sell-the-news : Results meet expectations but lack meaningful surprise; profit-taking likely. RSI cools to 50–55; MACD contracts. Watch EMA 20 near $1,025 for stabilisation.
Guidance miss or margin disappointment : Management signals margin pressure or HBM oversupply. RSI breaks <50, EMA 20 fails, risking a move toward $846–$952 support. Primary risk despite low probability.
Long 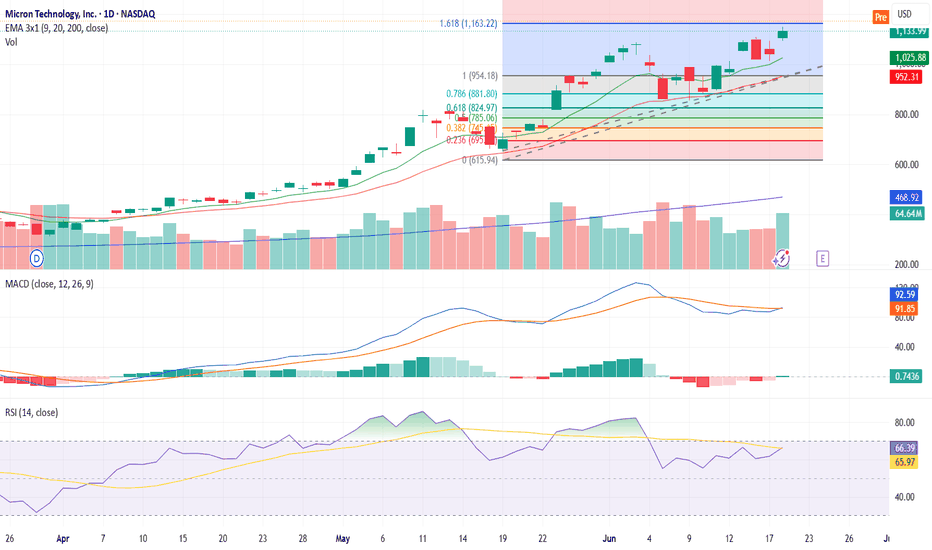
Wall Street raises Kospi targets Did investors and analysts underestimate the role Samsung, SK Hynix, and other South Korean companies in the global AI trade?
JPMorgan has now raised its bull-case target for the Kospi to 10,000, up from 9,000. That would imply more than 25% upside from current levels.
South Korea’s equity market has become increasingly tied to AI, with chip stocks now making up around half of the Kospi’s total weight. Those stocks have driven roughly 70% of the index’s gains this year. The Kospi is up more than 80% this year, following a 76% advance in 2025.
“Korea remains our most preferred market in the region and we raise our base/bull/bear case Kospi targets to 9,000/10,000/6,000,” JPMorgan strategists said.
Still, the bank noted that the market looks technically stretched after such a sharp move, meaning periods of consolidation are likely.
Other major banks have also turned more bullish. Goldman Sachs raised its 12-month base target for the Kospi to 9,000 from 8,000, while Citi lifted its target to 8,500 from 7,000.  Long