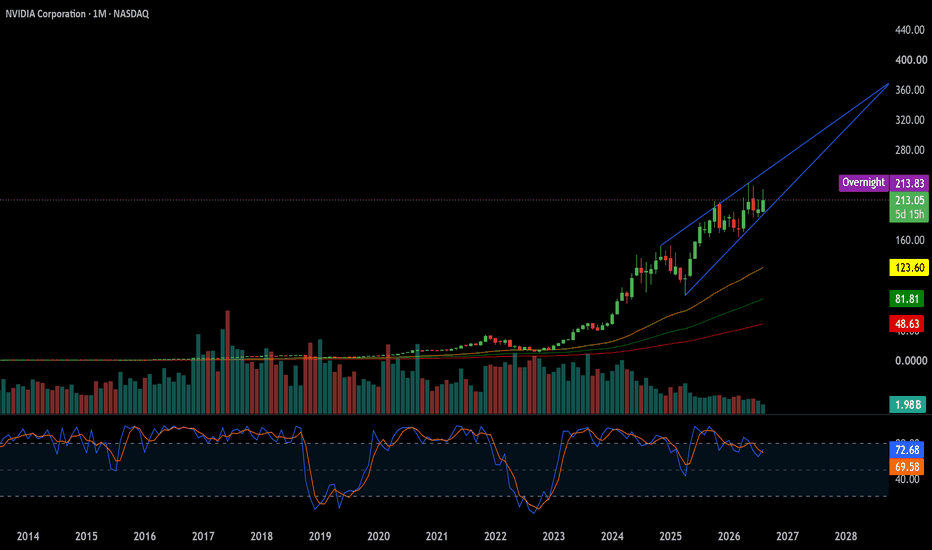
Can Nvidia Defend Its Five Trillion Dollar Crown?Wall Street awaits Nvidia’s second-quarter fiscal earnings report with intense scrutiny. Analysts project total quarterly revenue to reach $92.2 billion. Data center sales will likely generate $86.3 billion. Investor anxiety centers on reduced cash reserves at major cloud customers. Tech giants Amazon, Alphabet, Meta, and SpaceX face mounting cash pressure from massive expenditures. However, enterprise artificial intelligence cloud demand continues robust expansion. Enterprise cloud segment sales will jump 149% annually. Chief Executive Officer Jensen Huang forecasts $1 trillion in cumulative sales through 2027. Ramping shipments of the Vera Rubin architecture power this growth trajectory.
Technological Breakthroughs and Patent Strategy
Nvidia builds market dominance through architectural breakthroughs and patent filings. The new Vera Rubin architecture delivers unmatched compute density and speed. Software patent developments center on CUDA Python 1.0. This layer provides unified APIs across high-performance computing ecosystems. Strict semantic versioning protects long-term developer investments. Programmers access low-level CUDA drivers alongside parallel algorithms seamlessly. In graphics rendering, DLSS 4.5 introduces second-generation transformer models. DLSS 4.5 merges image denoising and spatial upscaling into one pass. This process boosts compute capability by 35% without hardware upgrades.
Geopolitical Sovereignty and Global Infrastructure
Accelerated computing hardware serves as a foundation for national power. World leaders classify microchip supplies as a critical geostrategic imperative. Foreign governments build domestic artificial intelligence factories for technological independence. Sovereign cloud initiatives demand localized data control and complete architectural isolation. Neocloud providers rely on standardized cloud compliance to satisfy strict local laws. Nvidia navigates international trade restrictions while constructing global data infrastructure. These geopolitical shifts establish compute infrastructure as vital strategic capital worldwide.
Macroeconomic Shifts and Financial Engineering
Hyperscalers historically generated over half of Nvidia’s data center revenues. Rising interest rates increase capital costs for massive computing projects. Macroeconomic headwinds force Nvidia to diversify its customer base. Nvidia launched a $500 billion initiative with major financial institutions. This financial structure transforms graphics processing units into investable collateral. Smaller enterprises borrow funds at lower interest rates secured by chip returns. This innovation expands hardware access across commercial enterprise buyers.
Novel Business Models and Strategic Investments
Nvidia constructs novel circular financing models to sustain market growth. A $21 billion stake in SpaceX highlights strategic capital alignment. SpaceX explicitly selected the Vera Rubin architecture for specialized computing infrastructure. Nvidia also guarantees up to $105 billion in lease liabilities for OpenAI. This guarantee backs the massive eight-gigawatt PORTS-Pike data center campus in Ohio. The site exclusively hosts full-stack Nvidia hardware and advanced networking platforms. These financial bridges supply essential capital to high-growth artificial intelligence developers.
Cybersecurity Architecture and Enterprise Networks
Enterprise artificial intelligence deployments demand robust security across every hardware layer. Nvidia partners with Cisco to construct the Secure AI Factory rack-scale architecture. The design pairs Spectrum-X backend switches with Cisco Silicon One network platforms. Cisco Nexus One unifies the management plane to prevent sensitive data leaks. Silicon-rooted resilience safeguards proprietary corporate data within sovereign environments. Integrated threat protection mitigates deployment risks for complex agentic workloads. This architecture ensures operational stability and privacy across critical corporate networks.
Physical AI, Science, and Pharmaceutical Breakthroughs
Edge computing hardware expands physical artificial intelligence capabilities into industrial robotics. The Jetson Orin Nano 2 provides 78 trillion operations per second of artificial intelligence compute. It delivers double the inference performance while consuming 40% less power. Industrial partners deploy the system across autonomous drones, home robotics, and vision platforms. Desktop platforms partner with Perplexity to run models locally on client systems. In life sciences, researchers utilize CUDA Python algorithms for complex molecular simulations. Accelerated computing speeds genomic sequencing and advances biopharmaceutical drug discovery.
Leadership Philosophy and Culture of Innovation
Co-founder Jensen Huang drives an engineering culture focused on flat organizational hierarchy and constant innovation. High gross profit margins fund aggressive research and development programs across software and hardware. Nvidia maintains a robust balance sheet while returning value to shareholders through share buybacks. The leadership team emphasizes software ecosystem stickiness to maintain high entry barriers. Deep CUDA integration prevents enterprise customer migration to alternative custom silicon competitors.
Strategic Metrics Overview
Financial & Technical Metric Specification Strategic Context
Market Capitalization $5.05 Trillion Reflects Nvidia's market leadership.
Q2 Projected Revenue $92.2 Billion Demonstrates dramatic top-line growth.
Data Center Revenue $86.3 Billion Represents 94 percent of quarterly revenue.
SpaceX Equity Stake $21.0 Billion Aligns capital with Vera Rubin platform adoption.
OpenAI Lease Guarantee $105.0 Billion Cap Secures credit for eight-gigawatt Ohio campus.
Jetson Orin Nano 2 78 TOPS Doubles entry-level edge inference performance.
DLSS 4.5 Compute Boost +35% Capability Upgrades AI rendering without hardware locks.
The Structural Foundation of a Tech Empire
Nvidia evolves from a specialized chipmaker into a global computing utility. Software ecosystem stability, circular financing, and edge expansion secure long-term market dominance. Hyperscaler cash constraints present short-term headwinds, but systemic demand remains overwhelmingly strong. Nvidia commands the indispensable foundation of modern technological civilization.  Long
 Long
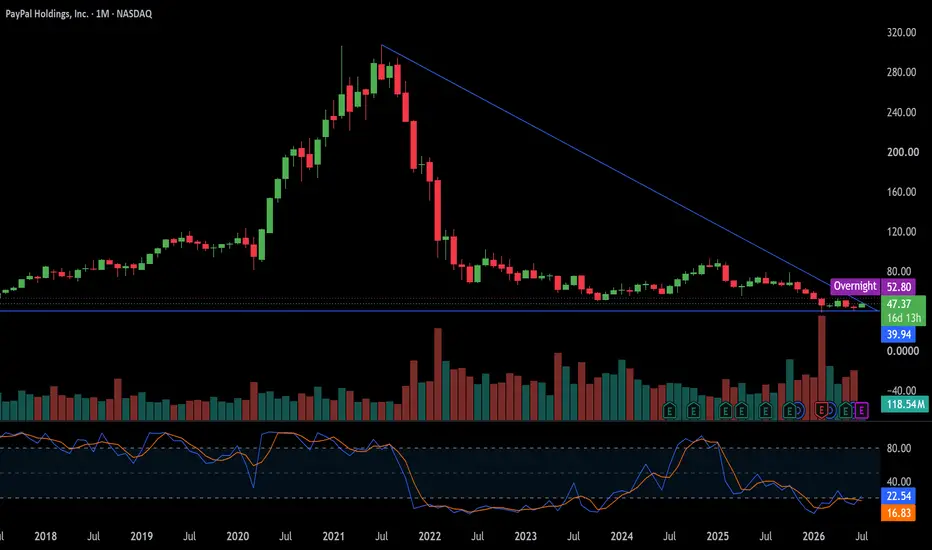
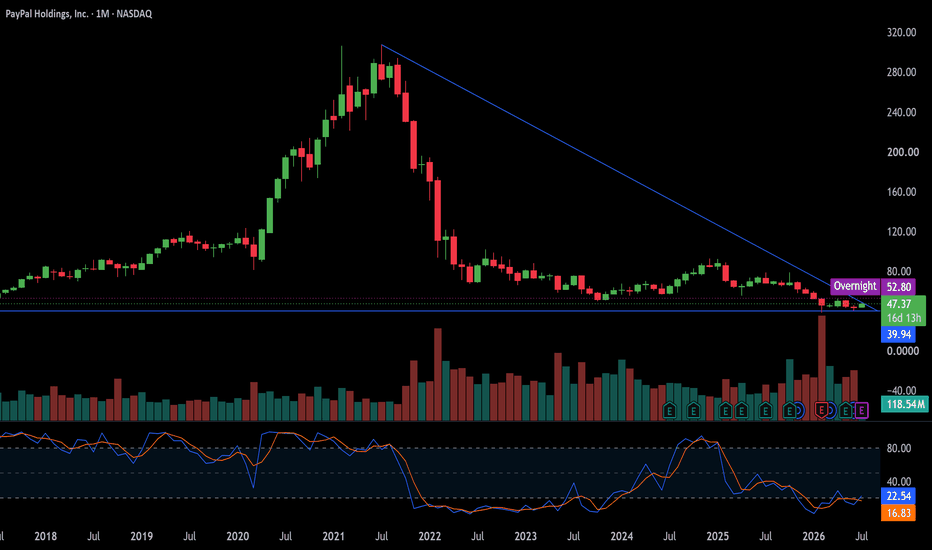
PayPal's $53B Buyout: A Global Fintech AwakeningStripe and Advent International just disrupted the financial world. They offered over $53 billion to acquire PayPal. This bold proposal values PayPal at $60.50 per share. It represents a massive 28% premium over recent market closures. Macroeconomic indicators frame this historic bid. High inflation and shifting interest rates squeeze legacy payment processors. Despite the premium, Goldman Sachs maintains a cautious outlook. They recently raised their price target for PayPal to $48. However, Goldman keeps a "Sell" rating. Markets demand profitability and resilience. This proposed mega-merger highlights rapid consolidation in global economics. Private equity and agile fintechs now dictate market momentum.
Geopolitics and Geostrategy
Global financial infrastructure is a prime geopolitical battleground. A Stripe-PayPal merger would create an undisputed Western payments titan. This geostrategic move counters the dominance of Asian networks like Alipay. Regulators across multiple continents will scrutinize this $53 billion transaction. Anti-monopoly laws will test international alliances. Cross-border capital flows determine national security parameters. Controlling this vast transaction network grants immense geopolitical leverage. Governments rely on digital payment arteries to enforce economic sanctions. Thus, this buyout carries severe strategic implications for global financial sovereignty.
Industry Trends and Business Models
The digital payments sector faces rapid evolution. Industry trends heavily favor embedded finance and unified commerce platforms. PayPal struggles against younger, more agile competitors. The proposed business model involves Stripe and Advent sharing equal ownership. This 50/50 split blends private equity capital with aggressive fintech innovation. It transforms traditional transaction fee models. The new entity would dominate both online checkout and backend merchant acquiring. Diversified revenue streams now mandate cryptocurrency integration and dynamic checkout experiences. Stagnant business models will perish in this hyper-competitive ecosystem.
Management, Leadership, and Company Culture
PayPal’s management faces a defining leadership crisis. New executives must navigate a fierce turnaround strategy. They must evaluate this $53 billion lifeline objectively. Rejecting the offer requires flawless execution of internal cost-saving plans. Accepting it demands a massive cultural shift. Company culture at PayPal must pivot toward rapid innovation. Stripe’s aggressive, builder-centric ethos contrasts sharply with PayPal’s legacy corporate structure. True leadership requires making ruthless decisions under immense Wall Street pressure. The boardroom must prioritize long-term survival over short-term pride.
Technology, High-Tech, and Cybersecurity
A combined Stripe-PayPal entity would control immense technological power. High-tech integration demands flawless execution. The companies must merge distinct cloud infrastructures and API architectures. Cybersecurity remains the paramount concern. Processing trillions of dollars attracts sophisticated state-sponsored hackers. The unified network must deploy zero-trust security frameworks. Advanced artificial intelligence will detect fraud anomalies instantly. Machine learning algorithms optimize transaction approval rates. Superior technology dictates market share in modern finance. This merger would set a new global benchmark for financial cybersecurity.
Science, Patent Analysis, and Pharmaceutical Industry
Digital finance increasingly intersects with hard science. Patent analysis reveals intense competition over cryptographic tokenization. These distinct patents build the foundation for future commerce. The pharmaceutical industry directly benefits from these payment innovations. Secure, instant cross-border transactions streamline global drug supply chains. Pharmaceutical companies manage complex intellectual property purchases utilizing encrypted payment rails. Furthermore, advanced data analytics trace sensitive medical transactions securely. This synergy between high-tech finance and life sciences accelerates global healthcare delivery.  Long
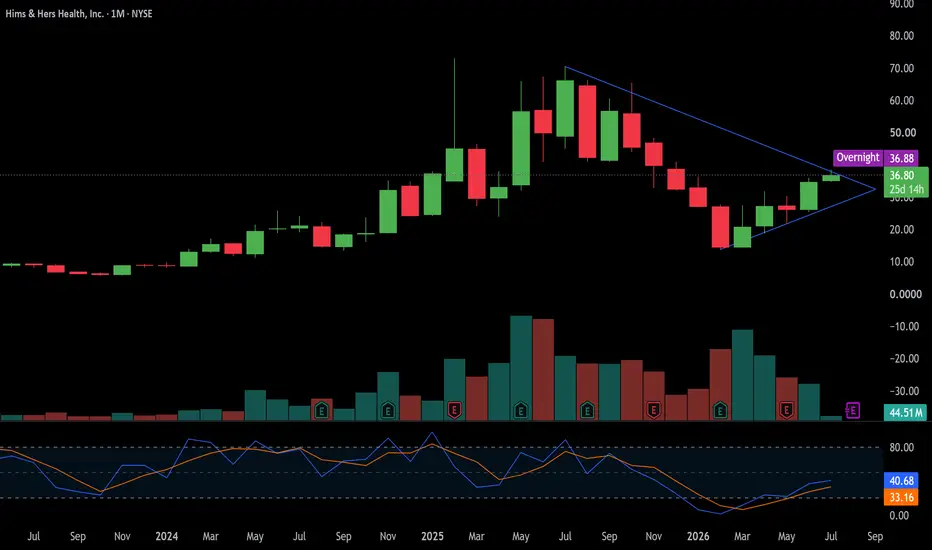
Is Hims & Hers Disrupting Medicine or Chasing a Bubble?Hims & Hers Health sits at the intersection of consumer technology and clinical care. The stock recently hit fresh 2026 highs. Canaccord Genuity boosted its price target to $40. Meanwhile, a massive $400 million JPMorgan facility unlocks unparalleled corporate liquidity. This digital platform faces both immense market enthusiasm and deep regulatory scrutiny.
Telehealth Borders and Geostrategy
Telehealth borders are expanding beyond domestic markets. The company actively diversifies its geographic footprint. For instance, international segments anchor recent top-line acceleration. This footprint balances the risk of localized regulatory gridlock. Global expansion insulates the enterprise against localized economic disruptions.
Macroeconomics and Capital Flexibility
High inflation and shifting credit landscapes test consumer retail spending power. Despite these headwinds, Hims & Hers exhibits strong consumer credit card data. The platform raised its full-year 2026 revenue guidance up to $3 billion. A resilient subscription model drives predictable cash flows during volatile periods.
Evolving Industry Trends and Business Models
Consumer behavior demands frictionless, on-demand medical access. Hims & Hers transforms the traditional patient journey into a digital experience. The platform shifts users away from physical waiting rooms. It capitalizes on high-margin, recurring software subscriptions. Partnerships with giants like Novo Nordisk expand the branded product shelf.
Corporate Vision, Culture, and Leadership
CEO Andrew Dudum embraces a bold corporate vision. He routinely shrugs off wild stock market swings. Dudum focuses the executive team on building a permanent healthcare institution. Leadership aggressively prioritizes capital flexibility to expand market share. This steady approach provides crucial confidence to institutional equity investors.
Driving Internal Innovation
The corporate culture rewards relentless operational agility and strategic pivots. Hims & Hers rapidly expanded its weight-loss catalog to capture consumer demand. Teams continuously launch novel wellness verticals. This culture of speed transforms theoretical concepts into profitable revenue lines.
High-Tech and Wearable Integration
The platform builds toward a comprehensive, full-stack AI healthcare matrix. The company plans imminent data integrations with advanced wearables like the Oura Ring. These high-tech diagnostic loops track personalized biometric signals over time. Consequently, the system creates an automated feedback loop for every subscriber.
Cybersecurity and Risk Management
Managing sensitive personal health information creates profound cyber risks. Data breaches can instantly destroy consumer trust and trigger massive penalties. Therefore, the company maintains rigorous digital defenses and secure databases. Advanced cybersecurity architecture shields vital patient data from global hackers.
Science and the Pharmaceutical Supply Chain
The legacy pharmaceutical supply chain remains rigid and expensive. Hims & Hers bypasses traditional bottlenecks by utilizing specialized compounding pharmacies. This scientific approach allows the platform to formulate customized, accessible treatments. The company successfully serves large, historically neglected consumer cohorts at scale.
Patent Analysis and Regulatory Catalysts
An upcoming July 2026 FDA advisory committee meeting could reshape the market. Regulators will evaluate easing restrictions on several prominent research peptides. FDA staff briefing documents released ahead of the meeting already recommend against several of these substances, citing insufficient human safety and efficacy evidence, though the committee’s recommendation is non-binding. Hims & Hers actively prepares for this potential commercial opportunity. The company acquired specialized peptide manufacturing facilities last year. A robust intellectual property moat protects these compounding methodologies from replication.
Strategic Outlook
Hims & Hers Health combines technological agility with financial discipline. It forces legacy healthcare providers to adapt or fail. The company skillfully balances severe regulatory risks against immense market demand. Winners in this space must innovate continuously. Hims & Hers proves it has the capital and vision to dominate.  Long

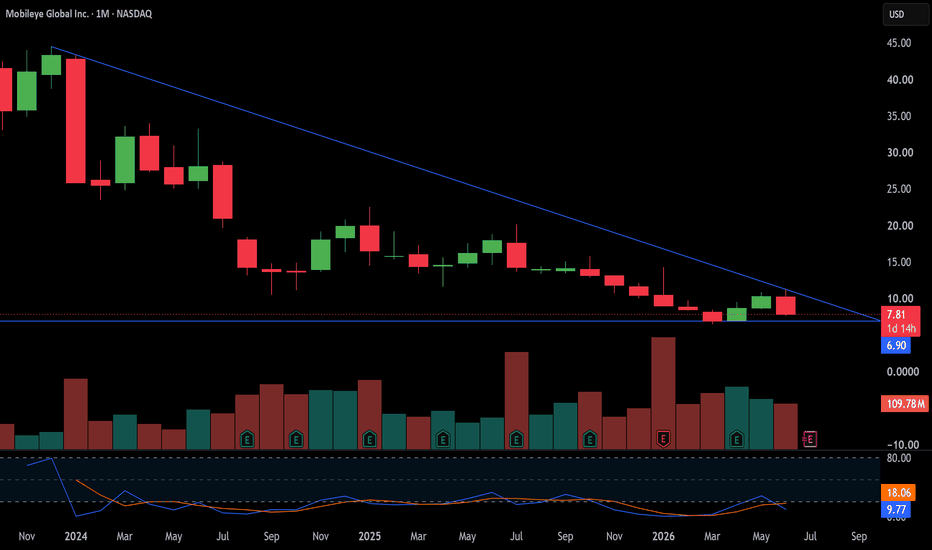
Is Mobileye's Robotaxi Pivot Worth the Risk?On June 22, 2026, Mobileye announced that it will stop being purely a supplier and start operating its own robotaxi service. After more than 25 years selling self-driving technology to automakers, the company will launch a vertically integrated, fully owned ride-hailing fleet in a major US city in 2027, beginning with roughly 100 vehicles and scaling to about 17,000 over the following five years. The service combines Mobileye's Drive self-driving system with its Moovit subsidiary, which supplies the consumer network, fleet management, and teleoperation. Each vehicle carries nine InnovizTwo LiDARs alongside Mobileye's own imaging radars and cameras.
The logic is margin capture. As a component supplier, Mobileye sells chips and software and lets ride-hailing operators keep the fare economics. As an operator, it captures the entire fare. The timing rides a supportive US regulatory shift, with the NHTSA easing rules for vehicles built without steering wheels or pedals through streamlined exemptions and proposed standard changes, which lowers the barrier to commercial deployment. Moovit's existing reach and the fact that Mobileye Drive already runs in the real world give the company a running start that most robotaxi entrants lack.
The catch, and the reason the move is controversial, is twofold. First, capital intensity. Mobileye is trading an asset-light, high-margin supplier model for the heavy cost of buying, maintaining, and insuring a physical fleet, a fundamentally different and riskier financial profile. Second, channel conflict. By running its own robotaxis, Mobileye now competes directly with the automakers that buy its components. That tension, undercutting the customers who fund the core business, is the genuine risk here, more than the technology or the regulation.
The honest read is a calculated bet to move up the value chain, not a reckless gamble, but one that puts the core supplier relationships at risk for a shot at a much larger prize. If the robotaxi economics work, Mobileye captures mobility-operator margins that dwarf component sales. If they do not, it will have spent heavily and strained its automaker base for little. For investors, the variables that matter are execution on the 2027 launch, the capital expenditure trajectory as the fleet scales, and whether automaker customers stay or defect. The pivot is unlikely to destroy the core business outright, but it deliberately wagers part of it on a bigger future.  Long
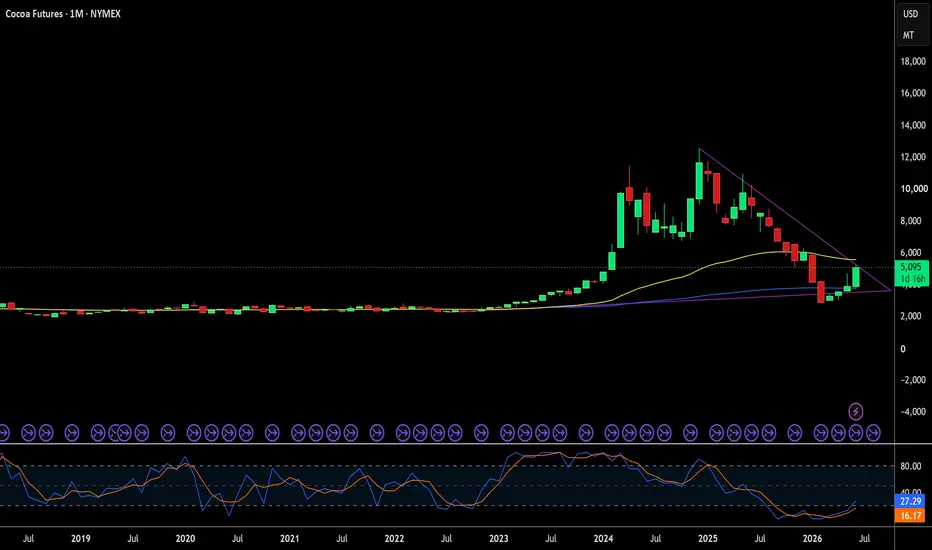
Will the Next Harvest Decide the Cocoa Market?Cocoa's story over the past two years is a violent round trip. Three consecutive West African deficits, the worst supply shortfall in more than 60 years, drove futures to a record near $12,900 a ton in December 2024. Then the market flipped. Better West African weather lifted production into back-to-back surpluses, while two years of record prices destroyed demand. Futures crashed more than 60% to near $2,850 in early 2026, before rebounding to roughly $4,300 by mid-June on weak next-crop signals and heavy speculative short-covering. Cocoa now sits far below its peak but is anything but settled, with realized volatility running near 63%.
That leaves a genuinely two-sided market. On the bearish side, supply has recovered, with StoneX projecting surpluses of about 247,000 tons in 2025/26 and 149,000 tons in 2026/27, and demand destruction has proven real and lasting, with grindings down roughly 6.7% across Europe, North America, and Asia. On the bullish side, early readings of the 2026/27 West African crop are weak, showing below-average cherelle counts, dry soils, and El Niño risk. The October main harvest is the swing factor: a normal crop points back toward $3,200, a disappointing one toward $5,800.
Two structural forces sit beneath the price. First, the EU Deforestation Regulation, with large-operator compliance due in December 2026, is bifurcating the market. Certified, traceable beans command a premium, while non-certified West African volumes risk exclusion from European buyers. Second, retail chocolate prices have stayed stubbornly high even as futures collapsed, because manufacturers hedge and buy months ahead and rarely reverse price increases once made. That asymmetry, cheaper beans but not cheaper bars, is a textbook case of sticky consumer inflation.
The honest read is a two-sided, harvest-driven market rather than a clean directional bet. Demand destruction and surplus supply cap the upside, while weak next-crop signals and El Niño risk cap the downside, leaving a wide but bounded range around the mid-$4,000s. For traders, the October West African harvest and the pace of demand recovery are the variables that matter. For chocolate makers, EUDR compliance and sticky retail pricing define the margin picture. Watch the crop and the grindings data rather than the geopolitical headlines. The contest over cocoa is really supply recovery and demand destruction fighting next-crop risk, and the next harvest casts the deciding vote.  Long

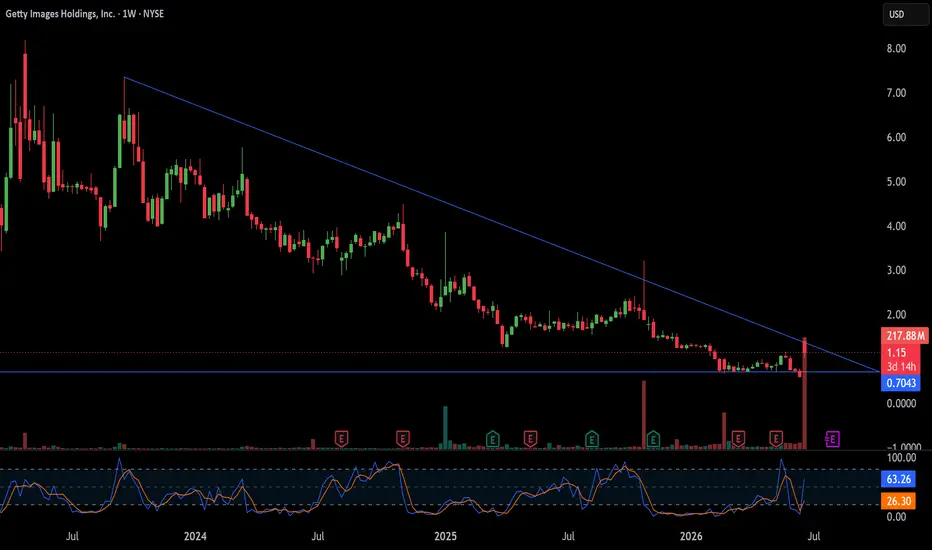
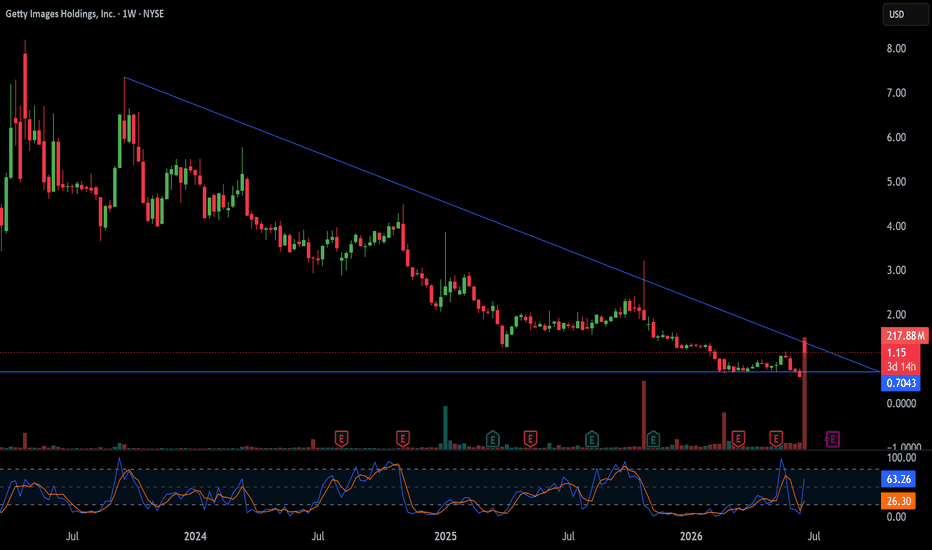
Is Getty's OpenAI Deal a Re-Rating or a Squeeze?Getty Images (NYSE: GETY) announced a multi-year display partnership with OpenAI on June 21, and the stock did the rest. Shares spiked as much as 145% intraday before closing roughly 90% higher near $1.15. The detail that matters is what the deal is: Getty's licensed images will appear in ChatGPT's search and discovery results with attribution, and the agreement explicitly excludes using those images to train OpenAI's models. Financial terms were not disclosed.
The real significance is narrative rather than near-term cash. Getty has flipped from litigation, having sued Stability AI, to positioning itself as the clean, licensed, attributed visual layer for AI-native search. That reframes the company's story from AI as an existential substitution threat to AI as a new distribution channel for rights-cleared content. For a business the market had largely written off, that shift in narrative is the genuine prize, and it is why a sleepy content name re-rated overnight.
The fundamentals demand caution, because the move came off a distressed base. GETY had been a sub-$1 stock trading near its 52-week low of $0.58, and it received an NYSE notice in March for failing the minimum-price requirement. First-quarter revenue of $226.6 million missed estimates, creative revenue fell 4.5%, and full-year guidance was left unchanged at $948 million to $988 million. The company carries negative margins, heavy leverage, and a $3.7 billion Shutterstock acquisition still awaiting approval. With no disclosed economics on the OpenAI deal, the 145% spike fading to a 90% close looks as much like a low-float squeeze as a true re-rating.
The honest read is that the deal is strategically real but financially unproven. Getty has a credible claim to be the licensed, rights-cleared content layer for AI search, and the pivot from suing AI firms to supplying them is smart. But "AI kingmaker" overstates a display agreement with undisclosed terms on a penny stock with shrinking revenue. Treat GETY as a high-risk, event-driven turnaround, not a proven AI-data winner. The swing factor is whether the OpenAI distribution, and the scale a Shutterstock deal would add, converts into disclosed, recurring revenue. Until terms and dollars appear, this is a narrative bet, not an earnings one.  Long
Is Dell’s AI Surge a Structural Monopoly?Dell Technologies posted a historic Q1 FY27 earnings blowout. The enterprise recorded blowout revenue of $43.8 billion, surging 88% year-over-year. Adjusted earnings per share reached $4.86, crushing consensus estimates of $2.96. This blowout triggered a vertical 39% stock surge in after-hours trading. Furthermore, AI server revenue soared 757% to $16.1 billion. Total backlogs for high-density artificial intelligence infrastructure hit a record $51.3 billion. Management subsequently raised its full-year revenue guidance midpoint to $167 billion.
Patent Leadership and Advanced Thermodynamics
Dell secures its high-tech dominance through aggressive patent filings and advanced thermal engineering. The firm holds 51,713 patents worldwide to shield foundational architectures. These assets protect critical infrastructure in enterprise storage and hardware integration.
Engineers actively design unique direct liquid cooling systems to manage soaring silicon heat densities. Specifically, patent US11175102B1 protects a liquid-cooled cold plate containing parallel turbulator channels. This unique design utilizes compressible seals to prevent coolant leaks inside high-density server racks.
This thermodynamic research addresses chips with heat densities exceeding the flames of gas torches. The scientific principles of microfluidics drive these specific thermal innovations. Liquid cooling absorbs heat four times more effectively than traditional forced-air systems.
Dell integrates this liquid architecture into the new Integrated Rack 7000 Series. These high-tech systems support up to 480 kilowatts of power per rack. This represents a twenty-fold thermal capacity increase over legacy datacenter infrastructure.
Fluid Dynamics and Airtight Architecture
Dell also advances high-tech air cooling using advanced computational fluid dynamics. The proprietary Smart Flow chassis creates highly efficient structural airflow channels. This design routes cold air directly around high-powered microprocessors.
Smart Flow increases active server airflow by approximately 17%. This strategic configuration enables powerful processors to run without complex liquid plumbing. Furthermore, patent US7867070B2 protects airtight server cabinets designed to maximize forced-air cooling.
Cybersecurity and Firmware Defense
Dell’s cybersecurity patents protect critical system firmware against sophisticated supply chain attacks. Patent-protected firmware authentication mechanisms secure enterprise networks and private clouds.
The company aggressively defends its proprietary power conversion designs from non-practicing entities. Co-defendants Dell and Samsung utilized Inter Partes Review petitions at the patent office. This joint litigation successfully dismantled hostile power adapter claims brought by MyPAQ Holdings.
Divergent Business Models and Storage Debate
Dell’s business model relies on high-margin proprietary storage to balance low-margin server assembly. Dell Technologies Capital originally nurtured VAST Data through early equity investments. VAST Data recently reached a historic $30 billion valuation after a massive capital raise.
However, the two companies now champion fundamentally different storage philosophies. VAST promotes a closed, flash-only architecture that requires extensive data migration via SyncEngine.
In contrast, Dell PowerScale utilizes dynamic, media-flexible tiering across flash and traditional hard drives. This approach successfully protects buyers from volatile NAND flash market pricing.
Furthermore, OneFS global compression delivers a contract-backed two-to-one data reduction guarantee. PowerScale consumes 72% less power than comparable VAST systems. The open, federated database architecture analyzes enterprise data directly where it lives.
Geopolitics, Geostrategy, and Macroeconomics
Geopolitical shifts force modern nation-states to build localized, sovereign cloud environments. Governments frequently restrict foreign access to advanced silicon to protect national security interests.
Dell’s resilient supply chain successfully bypasses international component bottlenecks to deliver critical IT hardware. For example, IREN Limited signed a $1.6 billion agreement to purchase advanced Dell Blackwell systems. These high-tech systems support a five-year, $3.4 billion artificial intelligence cloud services contract.
Geostrategy dictates that modern militaries require rapid, secure data sharing across operational domains. Dell Federal Systems recently secured a historic $9.7 billion defense contract. This five-year agreement consolidates Microsoft licensing across the entire defense establishment.
This massive deal provides the digital connective tissue for military command networks. The transition ensures secure, disconnected cloud operations for warfighters in active combat zones.
This massive federal consolidation reflects rigid macroeconomic fiscal discipline in government spending. The single-award contract shifts fragmented service budgets into one centralized buying point.
This strategic shift will save taxpayers an estimated $422 million annually. Microeconomic analysis shows that bulk procurement drives unprecedented cost efficiency. This transaction establishes a highly predictable multi-year revenue floor for Dell.
Leadership and Culture Driving Industry Trends
Dell’s corporate culture prioritizes long-term technology bets over short-term market fluctuations. CEO Michael Dell cultivates powerful political and philanthropic alliances to expand corporate reach.
Michael Dell and Susan Dell donated $6.25 billion to fund child investment accounts. Following this announcement, President Trump endorsed Dell products during a White House event. This unique alignment of political influence and corporate innovation accelerates public sector market penetration.
COO Jeff Clarke actively manages long lead times for memory and processors. The company’s global supply chain scale secures priority allocations from key semiconductor foundries. Dell balances these supply constraints by maintaining strict pricing discipline across lines.
Meanwhile, the explosive rise of autonomous AI agents drives a massive recovery in traditional server demand. Dell’s legacy server revenues nearly doubled to $8.5 billion during this blowout quarter.
Agentic systems execute real tasks, requiring heavy CPU processing for sequential decision-making. Traditional microprocessors must handle complex branching logic and state management loops. This architectural shift significantly expands the global addressable market for traditional servers.  Long

Eli Lilly & NVIDIA: A $1B AI Pharma RevolutionEli Lilly’s $1 billion partnership with NVIDIA signals a seismic shift in pharmaceutical valuation and strategy.
The convergence of biology and silicon is no longer theoretical; it is the new standard for industry leadership. By integrating NVIDIA’s AI supercomputing into its core operations, Eli Lilly (NYSE: LLY) is transitioning from a traditional drug maker to a bio-computation giant. This move secures its dominance not just in medicine, but in the high-growth data economy.
Technology & Science: The "Loop" Advantage
The core of this growth thesis is the new "loop-style" discovery system. Traditional drug discovery is linear, slow, and prone to failure. Lilly’s new model utilizes an AI supercomputer to generate molecular candidates, which physicians then test. Crucially, the biological data from these tests immediately feeds back into the AI, refining the model in real-time. This recursive learning cycle drastically reduces the time-to-market for new therapies. Science is now software-defined, and Lilly controls the source code.
Industry Trends & Economics: Capturing the $105B Market
The financial implications are staggering. The drug discovery market hit $105 billion in 2025, growing at a steady 10% annually. However, the real explosion lies in AI-enabled discovery, currently under 20% of the sector but projected to expand sixfold by 2034. Lilly is not just participating in this growth; they are engineering it. By dominating AI-driven discovery, they unlock inroads to the $550 million U.S. production market, effectively vertically integrating intelligence with manufacturing.
Geopolitics & Geostrategy: Health Security
Pharmaceutical dominance is a pillar of modern national security. Nations that control the fastest drug discovery platforms possess a distinct geostrategic advantage. By onshoring this supercomputing capacity, Eli Lilly aligns itself with U.S. interests in biological resilience. This reduces reliance on foreign research supply chains and positions the company as a strategic asset. Investors should view this as a government-aligned moat that insulates the stock from standard market volatility.
Cyber & High-Tech: The Data Fortress
Integrating NVIDIA’s Thor IGX platform transforms Lilly’s cyber profile. The company is no longer just protecting formulas; it is guarding proprietary training data. This shift demands a "Zero Trust" cyber architecture. As Lilly digitizes biological experimentation, its database becomes one of the most valuable intellectual properties on earth. Management’s foresight to secure industrial-grade AI infrastructure proactively mitigates the risks of IP theft in an era of digital espionage.
Management & Leadership: A Culture of Disruption
Corporate leadership is abandoning the "siloed" R&D model. Lilly’s executives are aggressively fostering a culture where data scientists sit equal to biologists. This cross-pollination drives innovation speed. While competitors hesitate to disrupt legacy workflows, Lilly’s management is betting the balance sheet on generative AI. This decisiveness commands a valuation premium. It signals to shareholders that leadership prioritizes long-term structural dominance over short-term quarterly safety.
Conclusion
Eli Lilly is redefining the pharmaceutical business model. Through its partnership with NVIDIA, it has effectively operationalized the future of medicine. For investors, LLY is no longer just a healthcare play; it is a high-tech growth stock backed by biological assets.  Long

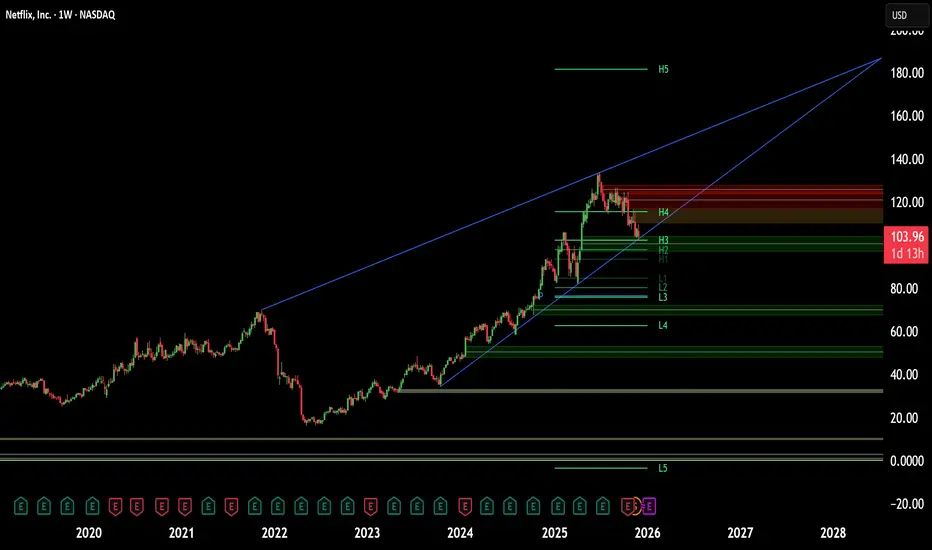
Netflix’s $70B Bid: The End of the Streaming Wars?Netflix (NASDAQ: NFLX) is rewriting the global media playbook. The streaming titan has submitted a binding, predominantly cash offer to acquire Warner Bros. Discovery (NASDAQ: WBD). This $70 billion maneuver marks a definitive pivot from disruptive builder to dominant consolidator. Management now signals that securing the next decade of dominance requires buying the industry’s most established moats.
Macroeconomics: The Power of Cash
Financial maturity drives this aggressive acquisition strategy. In a high-interest-rate environment, cash offers reign supreme. Netflix utilizes its fortress balance sheet to outmaneuver the rival Paramount Skydance consortium. While competitors propose complex stock swaps, Netflix offers WBD shareholders immediate liquidity and a defined exit price. With a projected Free Cash Flow of $9 billion for 2025, the company can service the necessary bridge loans without jeopardizing operations.
Geostrategy: The Regulatory Battlefield
The acquisition’s greatest threat lies in Washington, not Wall Street. White House officials have flagged concerns regarding media consolidation. However, Netflix utilizes a sophisticated geostrategic argument. The company contends it competes against trillion-dollar ecosystems like Apple and Amazon, not just legacy studios. By framing the merger as essential for surviving against Big Tech, Netflix aims to navigate the Department of Justice’s antitrust maze.
Industry Trends: Buying Cultural Infrastructure
Netflix is purchasing history, not just content. The deal secures the DC Universe, Harry Potter, and the historic Warner Bros. Studio lot. These assets represent "cultural infrastructure" that original production spend cannot replicate. Data from WBD’s Q3 2025 earnings confirms the value here: theatrical revenue surged 74% driven by franchise hits. This allows Netflix to diversify revenue streams into box office and merchandising at an unprecedented scale.
Technology & Cyber: The Traffic Signal
Platform stability remains a key indicator of consumer demand. The recent premiere of *Stranger Things* Season 5 crashed the platform, causing widespread outages. While technically a failure, Wall Street interprets this cyber-stress test as a bullish signal. It proves organic engagement is explosive. Integrating WBD’s library into this high-traffic ecosystem leverages Netflix’s proprietary delivery architecture to maximize viewership of dormant assets.
Management & Leadership: The Strategic Pivot
Netflix leadership is executing a calculated evolution. For 15 years, the strategy focused on building IP from scratch. Now, the C-suite recognizes that acquiring established franchises is the fastest route to a defensible moat. This assertiveness reflects confidence. With a market cap of roughly $460 billion, they are acquiring WBD because they can, not because they must to survive.
Data Science & Innovation: The Algorithmic Multiplier
The true value unlocked lies in data science. Netflix’s proprietary recommendation algorithms will likely revitalize WBD’s deep library. Merging WBD’s content with Netflix’s user data creates a powerful feedback loop. This "algorithmic multiplier" ensures that back-catalog titles achieve higher engagement on Netflix than they ever could on standalone platforms. This technological synergy justifies the premium paid for the assets.
Conclusion: A New Media Era
Netflix is positioning itself to own the entire entertainment ecosystem. The deal eliminates a key competitor and secures irrefutable IP dominance. While the $109 stock price held firm, the long-term thesis has shifted. Netflix is no longer just a tech platform; it is becoming the definitive media empire of the 21st century.
 Long

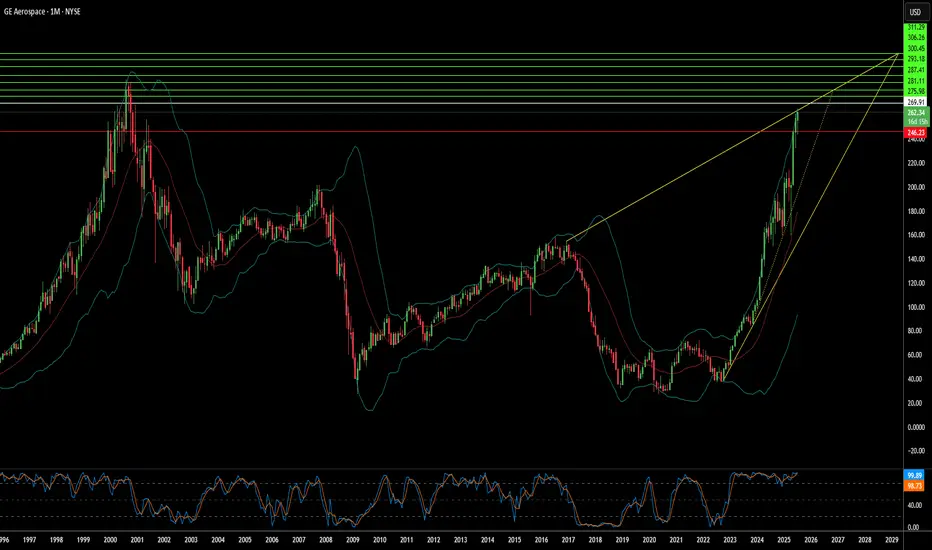
Soaring High: What Fuels GE Aerospace's Ascent?GE Aerospace's remarkable rise reflects a confluence of strategic maneuvers and favorable market dynamics. The company maintains a dominant position in the commercial and military aircraft engine markets, powering over 60% of the global narrowbody fleet through its CFM International joint venture and proprietary platforms. This market leadership, coupled with formidable barriers to entry and significant switching costs in the aircraft engine industry, secures a robust competitive advantage. Furthermore, a highly profitable aftermarket business, driven by long-term maintenance contracts and an expanding installed engine base, provides a resilient, recurring revenue stream. This lucrative segment buffers the company against cyclicality and ensures consistent earnings visibility.
Macroeconomic tailwinds also play a crucial role in GE Aerospace's sustained growth. Global air travel is steadily increasing, driving higher aircraft utilization rates. This directly translates to greater demand for new engines and, more importantly, consistent aftermarket servicing, which is a core profit driver for GE Aerospace. Management, under CEO Larry Culp, has also strategically navigated external challenges. They localized supply chains, secured alternate component sources, and optimized logistics costs. These actions proved critical in mitigating the impact of new tariff regimes and broader trade war tensions.
Geopolitical developments have significantly shaped GE Aerospace's trajectory. Notably, the U.S. government's decision to lift restrictions on exporting aircraft engines, including LEAP-1C and GE CF34 engines, to China's Commercial Aircraft Corporation of China (COMAC) reopened a vital market channel. This move, occurring amidst a complex U.S.-China trade environment, underscores the strategic importance of GE Aerospace's technology on the global stage. The company's robust financial performance further solidifies its position, with strong earnings beats, a healthy return on equity, and positive outlooks from a majority of Wall Street analysts. Institutional investors are actively increasing their stakes, signaling strong market confidence in GE Aerospace's continued growth potential.  Long

Can P&G Weather the Economic Storm?Procter & Gamble, a global leader in consumer goods, currently faces significant economic turbulence, exemplified by recent job cuts and a decline in its stock value. The primary catalyst for these challenges stems from the Trump administration's tariff policies, which have directly impacted P&G's supply chain by increasing costs for raw materials and finished goods imported from China. This financial burden, estimated to be hundreds of millions of dollars, compels P&G to reassess sourcing strategies, enhance productivity, and potentially raise product prices, risking a reduction in consumer demand.
In response to these escalating pressures and a noticeable slowdown in category growth rates within the U.S., P&G has initiated a substantial restructuring program. This includes the elimination of up to 7,000 jobs, representing approximately 15% of its non-manufacturing workforce, over the next two years. The company also plans to discontinue sales of certain products in specific markets as part of its broader strategic adjustments. These decisive measures aim to safeguard P&G's long-term financial algorithm, although executives acknowledge they do not alleviate immediate operational hurdles.
Beyond the direct impact of tariffs, a pervasive sense of economic uncertainty and declining consumer confidence in the U.S. further complicates P&G's operating environment. Recent data indicates a sustained drop in consumer sentiment, directly influencing discretionary spending and prompting households to become more cautious with their purchases. This shift, combined with broader negative economic indicators such as rising jobless claims and increased layoffs across various sectors, creates a challenging landscape for companies reliant on robust consumer spending. P&G's immediate future hinges on its strategic agility in mitigating tariff impacts, managing pricing, and adapting to a volatile economic climate.  Short