Is Gold's $5,200 Target Still Realistic in 2026?Macroeconomic Volatility and Price Consolidation
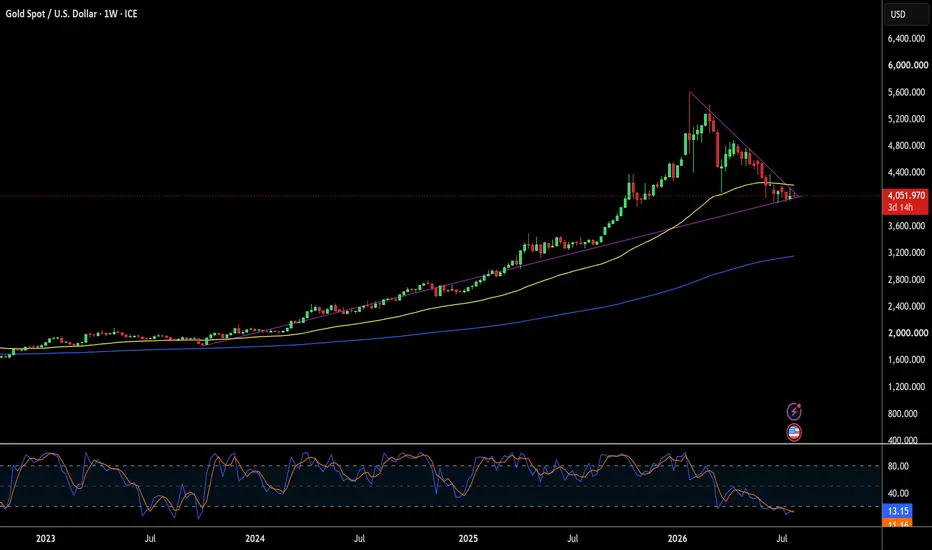
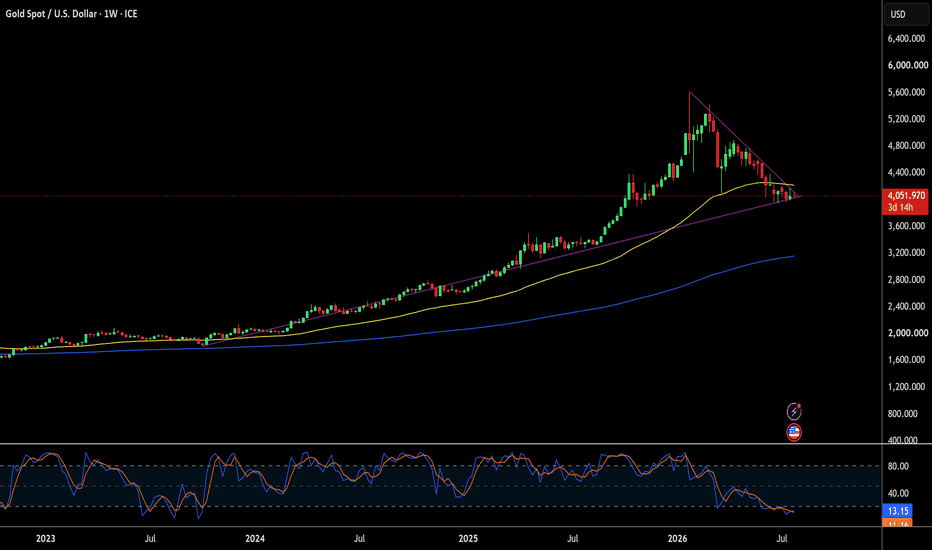
Gold spot prices consolidate near $4,080 per ounce following a sharp pullback from earlier highs. Wall Street giant UBS maintains a bullish target of $5,200 per ounce by mid-2027. Near-term risks lean downward as the Federal Reserve holds rates steady with a hawkish bias, and markets now price meaningful odds of a hike rather than a cut later this year. Rising US Treasury yields create short-term friction for non-yielding assets like precious metals. However, institutional investors view current price consolidation as a strategic buying opportunity.
Geopolitics, Geostrategy, and Central Bank Demand
Geopolitical friction drives sovereign central banks toward aggressive reserve diversification. Sovereign nations systematically replace US dollar reserves with physical bullion assets. Central banks acquired record tonnage to shield national balances from global currency devaluation. De-dollarization strategies now dictate international monetary policies across emerging market economies. These geostrategy shifts establish a firm structural floor for global gold valuation.
High-Tech Innovation, Science, and Patent Analysis
Modern mining corporations rely on proprietary patents to revolutionize extraction efficiency. Firms deploy bio-leaching algorithms and automated sensor technologies to locate deep ore deposits. Patent activity centers on eco-friendly, cyanide-free refining processes to meet strict environmental standards. Additionally, high-tech industries require specialized gold components for advanced semiconductor microchip manufacturing. These patented chemical processes ensure sustainable supply chains for critical global electronics.
Corporate Leadership, Business Models, and Industry Trends
Mining leaders prioritize strict capital allocation over reckless mega-mergers. Executive management teams focus heavily on operational cash flows and dividend payouts. Concurrently, financial technology platforms disrupt traditional bullion trading through asset tokenization. Digital gold assets allow fractional ownership and instant settlement across digital networks. This innovative business model expands institutional and retail market participation significantly.
Cybersecurity, Pharmaceuticals, and Healthcare Applications
Cybersecurity architecture increasingly secures digital gold tokens using cryptographic blockchain ledgers. Immature digital vaults face severe cyber threats, making hardened encryption mandatory for institutions. Meanwhile, the pharmaceutical industry utilizes gold science for groundbreaking medical applications. Biomedical researchers leverage patented gold nanoparticles for targeted cancer therapies and rapid diagnostic assays. These high-precision medical applications underline the growing scientific demand for refined gold.  Long
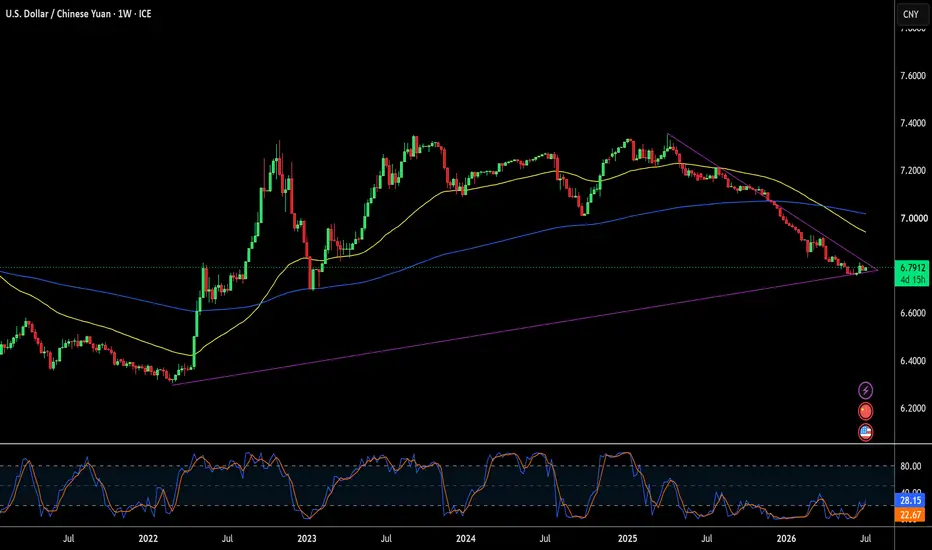
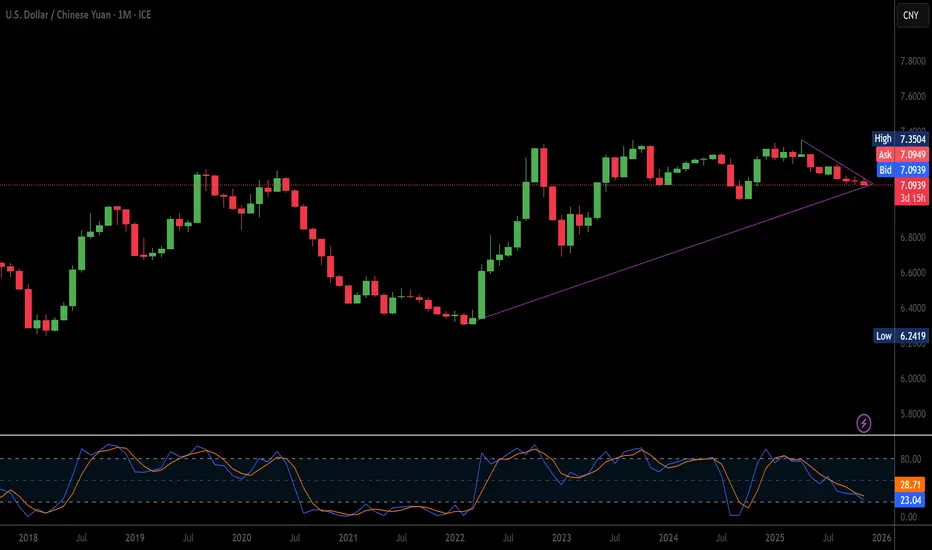
Why the Resilient Yuan Threatens Dollar DominanceThe global financial landscape is shifting rapidly. The USD/CNY exchange rate hovers stubbornly around 6.79. Despite recent US Dollar strength, the Chinese Renminbi displays remarkable resilience. HSBC reports that long-term structural forces continue to support the Chinese currency. Beijing actively drives financial self-reliance, pushing the Yuan onto the global stage. This economic tug-of-war carries profound implications across multiple global sectors.
Geopolitics and Geostrategy
Superpowers now fight their wars on digital ledger screens. Beijing utilizes the Yuan to diminish its exposure to Western financial sanctions. Washington counters by strengthening traditional fiat alliances. Consequently, neutral nations increasingly settle trade in alternative currencies. This geostrategic realignment reduces global dependence on the US banking network. De-dollarization is no longer a theoretical risk; it is an active policy.
Macroeconomics and Financial Economics
Interest rate differentials heavily influence short-term currency movements. The People's Bank of China manages the daily USD/CNY fixing with extreme precision. While the Federal Reserve battles sticky inflation, China expands its domestic credit channels. HSBC highlights new reforms from the Lujiazui Forum that accelerate capital account openings. Cross-border trading mechanisms insulate the domestic economy from external macroeconomic shocks.
Industry Trends and Business Models
Global supply chains face unprecedented fragmentation pressures. Multinationals must reconfigure their legacy business models to survive. Companies are increasingly adopting dual-currency pricing to mitigate forex risk. Dealing directly in Yuan eliminates costly intermediate conversion fees. This trend reshapes the automotive, manufacturing, and consumer electronics sectors. Ultimately, flexible currency models secure predictable corporate profit margins.
Company Culture and Innovation
Modern financial institutions must foster cultures of rapid technological adaptation. Chinese banks innovate by pioneering offshore trading within Shanghai's Free Trade Zone. Employee workflows now emphasize digital asset fluency and cross-border agility. Corporate leadership teams reward proactive risk management over static operational habits. This cultural shift transforms conservative state banks into aggressive global fintech competitors.
Management and Leadership
Corporate executives must navigate wild currency fluctuations with steady hands. Chief Financial Officers need to redefine their corporate treasury playbooks. Relying solely on US Dollar reserves invites unnecessary structural vulnerability. Savvy corporate leaders diversify assets into sovereign bonds across various jurisdictions. Effective management transforms currency volatility into a distinct competitive advantage.
Technology, High-Tech, and Cybersecurity
The digital Yuan represents a massive leap in financial technology. Distributed ledger networks automate trade settlements through secure smart contracts. This high-tech architecture bypasses legacy financial routing systems completely. However, centralized ledger tracking introduces severe cybersecurity vulnerabilities. State actors must deploy quantum-resistant encryption to shield transactional data. Robust digital security safeguards sovereign financial autonomy from malicious hackers.
Science and Patent Analysis
Fintech innovation requires a massive foundation of proprietary science. Chinese institutions dominate global patent filings for blockchain and ledger systems. Rigorous patent analysis reveals a systematic accumulation of cryptographic intellectual property. Beijing secures foundational code to dictate future cross-border payment standards. Controlling financial patents ensures long-term technological dominance in global trade markets.
The Pharmaceutical Industry Connection
The pharmaceutical industry depends heavily on Chinese raw materials. China produces a vast majority of global active pharmaceutical ingredients. Fluctuations in the USD/CNY rate directly impact global drug manufacturing costs. To stabilize supply chains, major pharma syndicates now settle contracts in Yuan. This localized currency arrangement guarantees stable pricing for lifesaving global medications.
Strategic Outlook
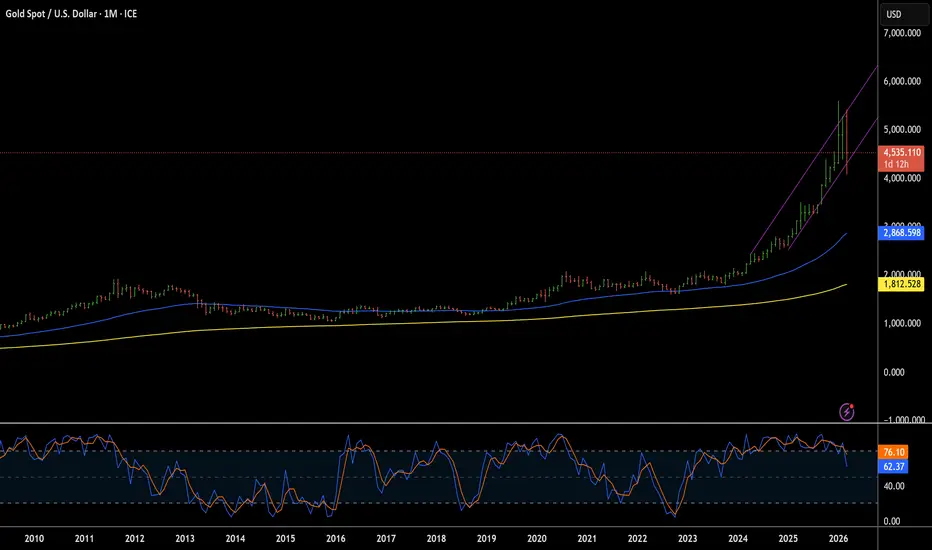
The USD/CNY dynamic reflects a larger battle for economic supremacy. Structural policies guarantee the Yuan a prominent seat at the table. Financial leaders must adapt to this multi-currency world order immediately. Complacency in a dollar-centric mindset will guarantee financial obsolescence. Is Gold's Rally Dead, or Coiled for $7,000?Gold's rally is not dead, but it has cooled sharply. After peaking near $5,589 in late January 2026, the metal corrected about 25% and now trades around $4,200 to $4,500, a slide that included its worst month since 2013. The cause is cyclical rather than structural. A hawkish Federal Reserve has signaled no rate cuts in 2026, and possibly hikes if energy-driven inflation persists, while elevated real yields raise the opportunity cost of holding a non-yielding asset. A firmer dollar and a retreat in ETF and speculative demand have added to the pressure.
Yet the floor under gold has rarely been firmer, which is why this looks like consolidation rather than collapse. Central banks have become the dominant, price-insensitive buyers, purchasing more than 1,000 tonnes a year from 2022 through 2024 and 863 tonnes in 2025, roughly double the pre-2022 norm. They buy as policy, not as a trade, and they do not sell on weak days. Combined with accelerating de-dollarization, with BRICS nations now holding 17.4% of global reserves and gold overtaking the euro as the second-largest reserve asset, plus US debt above $36 trillion, that demand has turned the $4,300 to $4,500 zone into structural support rather than a ceiling.
That tension defines the price debate. The mainstream base case for end-2026 clusters between roughly $4,900 and $6,300, with Goldman Sachs near $4,900, UBS at $5,500, and J.P. Morgan and Wells Fargo around $6,000 to $6,300. The $7,000 headline is a real forecast, but a conditional one. UBS sees $7,200 only if geopolitical risks escalate materially, and Bank of America's $8,000 is a 2027 bull case. Reaching $7,000 requires a fresh catalyst, renewed Fed easing, a geopolitical shock, or a return of ETF inflows, not merely the structural bid already in place.
The honest read is that the rally is neither dead nor charging to $7,000 today. It is consolidating, pinned between a cyclical ceiling and a structural floor, waiting for a catalyst to break the deadlock. The asymmetry is what matters for investors. The downside looks limited because price-insensitive central banks keep absorbing dips, while the upside to $7,000 depends on the Fed pivoting or geopolitics re-escalating. The signals to watch are real yields, the Fed's path, ETF flows, and the resolution of the Iran conflict. Until one of those turns, gold grinds sideways on a firm floor, a coiled spring rather than a dead rally.  Long

Is Brazil's Panda Bond a Dollar Threat, or a Test?Brazil's first Panda bond is a deliberate diversification step, not a dollar-killer. Acting Finance Minister Dario Durigan said the country will raise up to 5 billion yuan, about $735 million, in its first yuan-denominated sovereign debt, the largest such debut by any foreign nation in China, with issuance expected within two to three months. He explicitly described it as a test. The move follows Brazil's 5 billion euro bond in April, its first euro issuance since 2014, and fits a clear strategy of adding funding currencies one at a time rather than leaning on the dollar.
The logic is cost and hedging, not geopolitics. Brazil's domestic borrowing costs are high, with the central bank holding its Selic rate elevated to fight inflation, while yuan funding is comparatively cheap. That gap is why Slovenia, Pakistan, Kazakhstan, and Hungary have all tapped China's onshore market over the past year. For Brazilian firms with China exposure, including Vale and WEG, which asked the government to open this channel, a sovereign benchmark offers a hedge against the real's volatility for projects whose returns can be eroded by currency swings.
Two caveats deserve plain statement. First, borrowing in yuan does not erase currency risk; it shifts that risk onto Brazil unless the proceeds are hedged or matched against yuan income, so the savings are not automatic. Second, the de-dollarization angle is real but modest. Durigan framed the bond as multilateralism, yet he also said there was no development on a BRICS common currency, and a $735 million test is a marginal event set against the dollar's dominance. This is the yuan's slow internationalization, one sovereign benchmark at a time, rather than a structural assault on the greenback.
The honest read is that the Panda bond is symbolically meaningful and financially sensible, but it is not a threat to the dollar. As a signal, it shows Latin America's largest economy treating China as a standing source of capital alongside the euro and dollar markets. As a number, $735 million is close to a rounding error in global sovereign debt. For investors, the real story is Brazil's funding strategy and the yuan's gradual rise, not an imminent currency revolution. Watch whether Brazil returns as a repeat issuer and whether private firms follow with their own Panda bonds. That, not the dollar's demise, is the true test of this debut. Long 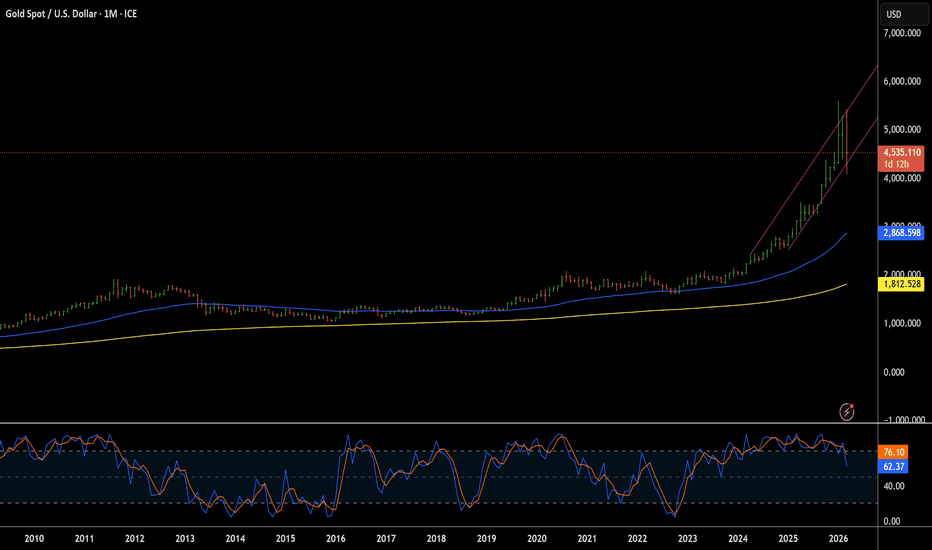
 Short

Short 
The Strategic Rise of the RenminbiAgainst a backdrop of economic headwinds, the Chinese renminbi is defying market logic. We analyze the geopolitical, strategic, and industrial drivers powering the currency’s 2025 ascent.
A Currency Defying Headwinds
In 2025, the **USD/CNY** exchange rate has shifted significantly, with the renminbi posting a nearly 3% annual gain against the dollar. This performance stands in stark contrast to the 5% depreciation seen during the 2018 trade tensions. What makes this valuation remarkable is the severe disconnect from traditional macroeconomic fundamentals. China currently faces weak domestic consumption, record-low interest rates, and a massive $281 billion capital account deficit.
Typically, such indicators would trigger a sell-off. Yet, the currency has appreciated. This divergence points to a singular, powerful causal force: tight, strategic state management by the People’s Bank of China (PBoC). Beijing is prioritizing stability over market freedom to project economic resilience.
Geostrategy: The 15th Five-Year Plan
The controlled rise of the renminbi is not accidental; it is a calculated geostrategic move. The **15th Five-Year Plan**, released in October 2025, signals a major pivot in Beijing's approach to global finance. The document omits previous cautious language like "prudently promote," replacing it with assertive directives for currency internationalization.
Market analysts interpret this as a clear signal: currency strength is now a central policy goal. By engineering a stable rise, China aims to mirror its strategy during the 1998 Asian Financial Crisis. The goal is to establish the renminbi as a regional anchor and a reliable store of value, countering the dominance of the US dollar.
Management & Leadership: The PBoC’s Aggressive Defense
Central bank leadership has deployed a sophisticated "reference rate strategy" to guide the market. Since November 2024, the PBoC has consistently set the daily midpoint rate significantly higher than market forecasts. The average spread between the PBoC’s fix and market expectations has reached 327 basis points—an historically high gap.
This is a masterclass in market signaling. By aggressively managing expectations, leadership creates a one-sided bet that deters speculative short-selling. This proactive management forces market participants to align with state objectives rather than economic fundamentals.
Business Models: State Banks as Market Makers
China’s unique financial business model allows for direct intervention through state-owned banks. These institutions have acted as proxies for the central bank, executing discreet USD sales and CNY purchases to cap volatility. This "engineered calm" has reduced the three-month volatility of the pair to near decade-lows.
The stability has altered corporate behavior. Exporters, previously hoarding dollars, are now unwinding holdings of over $1 trillion stored in domestic banks. This creates a self-reinforcing loop: state intervention stabilizes the price, and corporate flows then validate that price, generating real demand for the renminbi.
Innovation & Industry Trends: The High-Tech Backstop
While financial engineering plays a role, the renminbi’s strength is also underpinned by China’s evolving industrial base. The decline in low-margin manufacturing is being offset by a surge in high-tech exports. Trade competitiveness remains robust despite currency appreciation.
This resilience is rooted in the country's pivot to high-value sectors like electric vehicles, green energy, and advanced machinery. Patent analysis of Chinese firms reveals a massive accumulation of IP in these domains. This technological leverage allows Chinese exporters to absorb exchange rate costs better than their low-tech predecessors, sustaining the trade surplus.
Cyber Finance & Global Adoption
The strategy is yielding tangible results in global markets. Daily trading volume in the CNY–USD pair has surged 60% to $781 billion. The renminbi now accounts for over 8% of global FX turnover.
This growth is driven by institutional investors and central banks diversifying their reserves. China is leveraging this trend by integrating the renminbi into cross-border digital payment systems. This "Cyber Finance" approach bypasses traditional SWIFT rails, further insulating the currency from geopolitical sanctions and US dollar liquidity crunches.
Conclusion: A Political Asset
The 2025 rise of the renminbi is a political project as much as an economic one. It challenges the standard "Impossible Trinity" of economics by maintaining a stable exchange rate and independent monetary policy through strict capital controls. For global investors, the message is clear: the PBoC will prioritize currency strength as a tool of soft power, regardless of domestic economic pain.
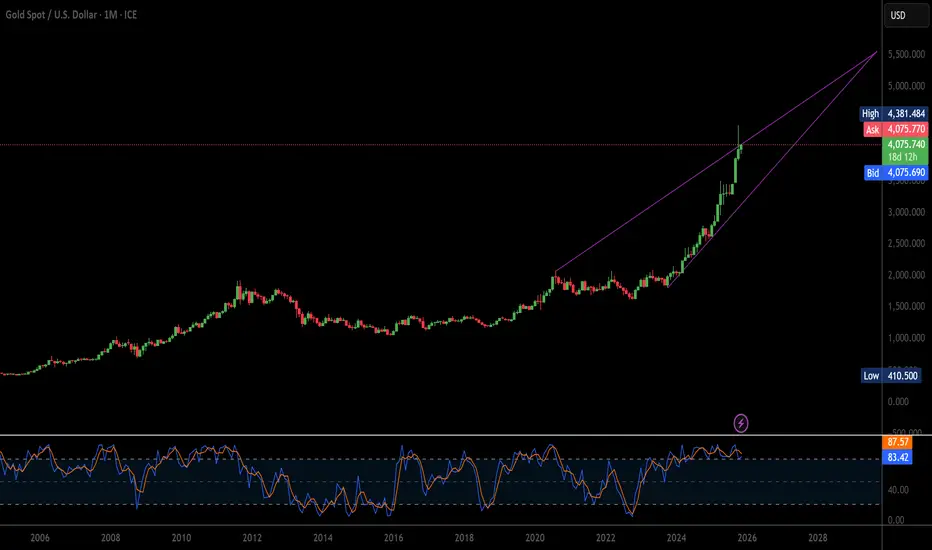
Golden Anchor: The Multi-Domain Resilience of BullionThe price of gold recently surged past $4,045 per ounce, cementing its role as a strategic global asset. This upward trend, pushing the year-to-date gain above 50%, is not merely speculative. It reflects deeply rooted structural forces across multiple global domains, from macroeconomics to high-tech demand. Investors are proactively using gold as a vital hedge against accelerating global uncertainty and fiat currency debasement.
Geopolitics & geostrategy: The De-Dollarization Hedge
Persistent geopolitical tensions drive sustained demand for gold's safe-haven status. Heightened conflict risks and unpredictable US tariff policies create global market volatility. In this fragmented landscape, gold acts as a politically neutral reserve asset, mitigating counterparty risk. Central banks globally are strategically accumulating gold to diversify away from the US dollar, accelerating the de-dollarization trend. This shift enhances national economic sovereignty, fueling gold's ascent.
Macroeconomics: Fiscal Dominance and Rate Cuts
Weakening US economic indicators directly reinforce gold’s appeal. A dip in the University of Michigan’s Consumer Sentiment Index signals broad economic unease. This fragility increases market bets on an earlier and more aggressive Federal Reserve rate-cutting cycle. Lower interest rates reduce the opportunity cost of holding non-yielding gold, boosting its price. Furthermore, the fiscal dominance prevalent in developed economies promotes gold as a critical hedge against the debasement of G7 fiat currencies.
Central Bank & Investment Demand Dynamics
Central bank purchases provide a formidable structural floor for gold prices. Despite the recent price correction, global central banks remain net buyers. They added 220 tonnes in Q3 2025 alone, representing a strategic, long-term commitment to gold. Poland, Kazakhstan, and Azerbaijan are notable accumulators. Retail and institutional investors are also turning to gold ETFs and physical bullion, viewing gold as essential financial insurance during systemic shocks.
Technology, Science, and High-Tech Demand
Technological advancements, particularly the boom in Artificial Intelligence, subtly support gold demand. While gold's main drivers remain macroeconomic, the high-tech sector consumes gold in electronic components and specialized circuits. Industrial demand remains resilient, offsetting a decline in jewelry consumption due to high prices. The massive, energy-intensive growth of AI and data centers indirectly creates a strategic need for high-value, reliable assets like gold to back infrastructure growth and hedge associated capital risks.
Technical Outlook and Consolidation Phase
Gold exhibits high long-term conviction but faces short-term consolidation after its historic rally. The price peaked at over $4,380 per ounce in mid-October before profit-taking began. Analysts expect the price to remain range-bound in the near term, with a maximum pullback risk around the strong $3,500/oz support level. Key technical resistance levels above the current peak are seen at $4,420/oz and $4,500/oz. Investors should utilize short-term dips as strategic long-term accumulation opportunities.
Long 
De-Dollarization and the Global Currency WarIntroduction: The Shifting Sands of Global Finance
For decades, the United States dollar (USD) has reigned supreme as the world’s dominant reserve currency — the central pillar of global trade, finance, and economic stability. From oil transactions to international debt settlements, the dollar became more than just a currency; it was the bloodstream of globalization. But in recent years, a strong wave of economic nationalism, geopolitical rivalry, and strategic diversification has begun to challenge this hegemony — a process known as “de-dollarization.”
Simultaneously, we’re witnessing an intensifying “currency war” — a global competition among nations to protect their economic sovereignty, control exchange rates, and reduce dependency on U.S.-led monetary influence. Together, de-dollarization and currency warfare are reshaping the financial map of the 21st century, with implications that reach from the energy markets of the Middle East to the central banks of Asia and Latin America.
This 2000-word analysis dives deep into the rise of de-dollarization, explores its causes and strategies, examines the mechanics of currency wars, and forecasts the potential shape of the next global monetary order.
1. The Roots of Dollar Dominance
After World War II, the 1944 Bretton Woods Agreement established the U.S. dollar as the world’s reserve currency, pegged to gold at $35 per ounce. Other global currencies were tied to the dollar, making it the foundation of postwar economic stability. Even after President Richard Nixon ended the gold standard in 1971, the dollar retained its dominance because of its stability, liquidity, and the economic might of the United States.
By the late 20th century, the dollar had become:
The primary reserve currency, held by central banks worldwide.
The medium of international trade, particularly in oil (the “petrodollar” system).
The currency of global finance, underpinning stock markets, bonds, and derivatives.
In short, control of the dollar meant control of the global economic bloodstream — and this financial power translated into political leverage.
2. What Is De-Dollarization?
De-dollarization refers to the deliberate process of reducing reliance on the U.S. dollar in international trade, finance, and reserves. It’s not about completely abandoning the dollar, but about diversifying away from it to limit vulnerability to U.S. monetary policy and sanctions.
Countries and blocs leading this movement include:
China, promoting the yuan (renminbi) in global trade.
Russia, moving away from dollar-based settlements after sanctions.
BRICS nations (Brazil, Russia, India, China, South Africa, now joined by others) working toward a shared currency system.
Middle Eastern countries, exploring non-dollar oil transactions.
Latin America and Africa, forming regional trade agreements in local currencies.
The motivation? A mix of economic independence, geopolitical resilience, and strategic competition.
3. The Key Drivers Behind De-Dollarization
(a) U.S. Sanctions and Weaponization of Finance
The U.S. uses its control over global payment systems (like SWIFT and dollar-clearing banks) as a geopolitical tool. Nations such as Iran, Venezuela, and Russia have faced financial exclusion through U.S. sanctions.
This has sparked fear among emerging economies that dollar dependency exposes them to political risk — accelerating efforts to create alternative payment systems (e.g., China’s CIPS, Russia’s SPFS, and India’s RuPay/UPI cross-border systems).
(b) Rise of China and the Yuan
China’s economic growth and the Belt and Road Initiative (BRI) have given the yuan increasing global exposure. Beijing aims to internationalize its currency by encouraging trade in yuan and developing offshore yuan markets (especially in Hong Kong, Singapore, and London).
(c) The BRICS Challenge
The BRICS alliance has emerged as a collective front against Western economic dominance. The bloc’s discussions around a BRICS common currency or a gold-backed trade settlement system indicate a long-term ambition to challenge dollar supremacy.
(d) U.S. Debt and Inflation
The U.S. government’s rising national debt (over $34 trillion) and the repeated use of quantitative easing have weakened confidence in the dollar’s stability. Countries fear that excessive dollar printing could erode their reserves’ value, prompting diversification into gold, the yuan, and other currencies.
(e) Digital Currencies and Blockchain
Central Bank Digital Currencies (CBDCs) offer new pathways for global payments. China’s digital yuan is leading this race, aiming to bypass the traditional dollar-based banking infrastructure entirely.
4. The Mechanics of a Global Currency War
A currency war, also known as “competitive devaluation,” occurs when countries intentionally lower the value of their own currencies to boost exports, attract foreign investment, and reduce trade deficits.
How It Works:
By devaluing their currency, a country’s goods become cheaper abroad.
This can strengthen exports but also increases import costs and inflation.
When multiple countries engage in this simultaneously, global financial instability can follow — hence the term “war.”
Historical Examples:
1930s Great Depression: Nations devalued currencies to recover from economic collapse.
1980s U.S.-Japan tension: Japan’s yen appreciation reshaped global trade.
2010s “Currency War 2.0”: After the financial crisis, countries used ultra-loose monetary policy and quantitative easing to stay competitive.
Today, the modern currency war involves not just exchange rates but geopolitical influence, payment systems, and financial infrastructure.
5. De-Dollarization and Currency Wars: The Modern Battlefield
In the 2020s, de-dollarization and currency competition have become two sides of the same coin. The following arenas illustrate this growing conflict:
(a) Energy Markets
The traditional petrodollar system — oil sold in U.S. dollars — is under strain.
China and Russia have signed major energy contracts in yuan and rubles, while Saudi Arabia has hinted at accepting non-dollar payments for oil. The India-UAE rupee-dirham trade settlement is another example of regional diversification.
(b) Central Bank Reserves
According to IMF data, the dollar’s share of global reserves has declined from 70% in 2000 to around 58% in 2024, marking a slow but steady erosion. Central banks are increasing holdings in gold, yuan, and euro, signaling a rebalancing of trust.
(c) Cross-Border Settlements
Nations are exploring bilateral trade agreements in local currencies — for instance, India-Russia rupee-ruble trade, China-Brazil yuan settlement, and ASEAN nations’ local currency framework.
(d) Digital Currency Warfare
With the U.S. lagging in CBDC development, countries like China are pioneering digital payment systems that can function independently of SWIFT and U.S. banking oversight. This could redefine how international money moves in the next decade.
6. Winners and Losers in the De-Dollarization Era
Winners:
Emerging Economies – Greater autonomy over monetary policy and trade settlements.
China and BRICS Members – Enhanced global financial influence and regional cooperation.
Commodity Exporters – Ability to price goods in multiple currencies.
Gold and Digital Asset Markets – Investors view these as alternative stores of value amid dollar uncertainty.
Losers:
U.S. Financial System – Reduced demand for U.S. Treasury bonds and the dollar may weaken the U.S. fiscal position.
Dollar-Debt Dependent Nations – Countries heavily indebted in dollars could face volatility.
Global Investors – Increased currency risk and reduced liquidity in traditional markets.
7. Is a New Global Currency Order Emerging?
While de-dollarization is gaining traction, a complete end to dollar dominance is unlikely in the short term. The U.S. still has unmatched advantages:
The deepest financial markets in the world.
Global trust in its institutions and legal system.
Military and geopolitical clout backing the currency’s credibility.
However, the trend is unmistakable — the world is slowly transitioning toward a multipolar currency system, where the dollar, euro, yuan, and possibly regional digital currencies coexist in a competitive balance.
Future trade blocs might operate on multi-currency platforms, and international reserves could become more diversified.
8. The Future: Cooperation or Confrontation?
The next decade could unfold in one of two broad scenarios:
Scenario 1: Cooperative Multipolarity
Nations collaborate through institutions like the IMF, BRICS Bank, and AIIB, building systems that support currency diversity while maintaining global liquidity. In this world, de-dollarization doesn’t mean destruction — it means balance.
Scenario 2: Financial Fragmentation
Geopolitical rivalry intensifies, creating currency blocs (USD-based, yuan-based, euro-based). Trade becomes more regionalized, and financial flows become fragmented. This could lead to volatility, capital flight, and higher transaction costs worldwide.
In either case, technological innovation — from digital currencies to blockchain trade settlements — will play a defining role in shaping monetary competition.
Conclusion: The Dawn of a New Financial Era
De-dollarization and the currency war are not isolated economic trends; they are strategic transformations redefining how power is distributed across nations. What began as a defensive move by a few sanctioned countries has evolved into a systemic global recalibration of monetary order.
The dollar will likely remain powerful, but its monopoly is fading. The 21st-century global economy may no longer be built around a single currency but around a network of competing and cooperating monetary systems.
For traders, policymakers, and investors, this means one thing: the world of finance is entering a new era — more decentralized, more digital, and more dynamic than ever before.  Education

Could One Event Propel Gold to $6,000?Gold has long been a refuge in times of crisis, but could it be on the brink of an unprecedented surge? Analysts now predict the precious metal could reach $6,000 per ounce, driven by a potent mix of geopolitical instability, macroeconomic shifts, and strategic accumulation by central banks. The prospect of a Chinese invasion of Taiwan, a major global flashpoint, could be the catalyst that reshapes the financial landscape, sending investors scrambling for safe-haven assets.
The looming threat of conflict in Taiwan presents an unparalleled risk to global supply chains, particularly in semiconductor production. A disruption in this critical sector could spark widespread economic turmoil, fueling inflationary pressures and eroding confidence in fiat currencies. As nations brace for potential upheaval, central banks and investors are increasingly turning to gold, reinforcing its role as a geopolitical hedge. Meanwhile, de-dollarization efforts by BRICS nations further elevate gold’s strategic importance, intensifying its upward trajectory.
Beyond geopolitical risks, macroeconomic forces add momentum to gold’s ascent. The U.S. Federal Reserve’s anticipated rate cuts, persistent inflation, and record national debt levels all contribute to a weakening dollar. This, in turn, makes gold more attractive to global buyers, accelerating demand. At the same time, the psychological factor—fear-driven safe-haven buying and speculative enthusiasm—creates a self-reinforcing cycle, pushing prices ever higher.
Despite counterforces such as potential Fed policy shifts or a temporary easing of geopolitical tensions, the weight of uncertainty appears overwhelming. The convergence of economic instability, shifting power dynamics, and investor sentiment suggest that gold’s march toward $6,000 is less a speculative fantasy and more an inevitable financial reality. As the world teeters on the edge of historic change, gold may well be the ultimate safeguard in an era of global upheaval. Long 
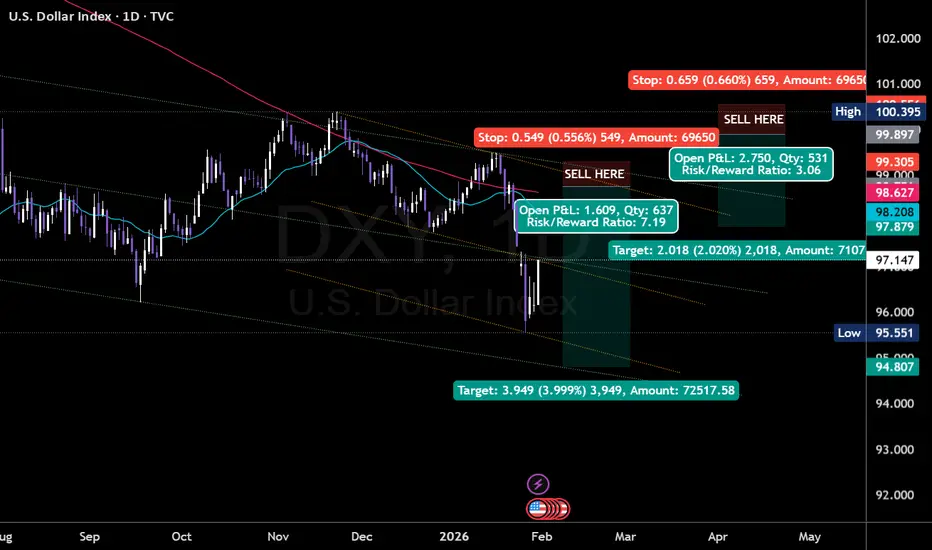
DXY Analysis & ConsiderationsOverall Trend & Context:
Long-Term Uptrend: The DXY exhibits a clear uptrend from late 2023, indicating persistent USD strength.
Key Levels:
Resistance Zone (109.50 - 110.00): This zone has proven a challenge for the DXY to break decisively. A sustained break above this level is crucial for further upside.
Support Zone (107.00 - 108.00): This zone has provided support during pullbacks.
EMAs (25, 50, 100, 200 - 4-Hour Chart): The DXY is trading above all EMAs, a bullish sign. The 25 EMA is acting as dynamic support, and a bullish crossover (25 above 50) has occurred.
Potential Scenarios & Probabilities:
Bullish Breakout (High Probability) : The bullish EMA alignment favor an upside breakout above 110.00. Increased volume would confirm this scenario.
Pullback to Support/EMAs (Medium Probability) : A pullback towards the support line or the 25 EMA (around 108.80 - 109.00) is plausible, especially given the overbought RSI. This could offer a good long entry opportunity.
Breakdown Below Support (Low - Medium Probability) : A break below the support line and the EMAs would weaken the bullish outlook and could lead to a deeper correction.
Trading Considerations:
xxxUSD pairs - If the dollar goes up we should look for short positions.
USDxxx pairs - If Dollar goes up we can look for long positions.
A pullback to the support zones or the 25 EMA could offer a lower-risk long entry, provided these levels hold and there is sufficient demand on the USDxxx pair you're trading. (technicals should always be prioritized)
Consider placing stop-loss orders below key support/demand levels to manage risk.
Look for increased volume during breakouts or bounces off support to strengthen signals.
Watch for bearish divergence on the RSI as a potential bearish warning sign on the DXY.
Geopolitical Factors:
De-dollarization Efforts: Some countries are exploring alternatives to the US dollar for trade and reserves. While this is a long-term trend, any significant announcements or actions could impact the dollar's value.
Sanctions and Trade Policies: US sanctions and trade policies can influence the dollar's strength, particularly against the currencies of targeted countries. The US imposed tariffs are creating ripples right now.
Let's quickly look at what 'tariffs' are -
By now you should all know about the US imposed tariffs on several major trading partners including China, Canada and Mexico (and that they've retaliated with their own tariffs on US goods).
What does this all mean?
In the US any goods that are imported from Canada for example, will now cost more to the general public. To put it simply, the US is now charging a "handlers fee" and that will increase the overall price.
These tariffs are intended to encourage these countries to change their trade practices.
The tariffs have disrupted global supply chains, increased costs for businesses, and created uncertainty.
Make no mistake, this is without a doubt, a trade war.
Potential Impacts on the US Dollar:
Positive Impact:
Safe-haven demand: Increased global economic uncertainty due to the trade war could drive investors towards the US dollar as a safe-haven asset, increasing demand and its value. People will flock to the take no s#it protocols implemented by the Trump administration.
Reduced imports: If tariffs lead to a significant decrease in US imports, there could be less demand for foreign currencies to purchase those imports, indirectly increasing demand for USD. This means that trade conducted by the US will increase the overall Dollar output - thus making it seem more valuable. (If we assume the Trump administration is playing petty games, we're badly misinformed, we should assume that these are well calculated risks)
Negative Impact:
Reduced US exports: Tariffs can make US goods less competitive, leading to a decrease in exports. This can reduce foreign demand for USD, as fewer foreign buyers need dollars to purchase US goods.
Economic slowdown: The trade war could negatively impact economic growth in the US and globally. A slowdown in the US economy could make the dollar less attractive to investors.
Retaliatory tariffs: If other countries retaliate with their own tariffs on US goods, it can further dampen US exports and reduce demand for the dollar.
Trade Wars and Uncertainty:
The uncertainty and potential for escalation associated with trade wars can negatively impact investor confidence and lead to a flight to safety. While the USD is often seen as a safe haven, extreme uncertainty could lead investors to seek other safe-haven assets or reduce their overall exposure to USD (Right now Gold is something you should be looking into as a trader and investor).
Final Notes:
The technical picture is strong and does favour a breakout. But the geopolitical risks reduce the probability. Be prepared for fundamentals to override technicals in the short term.
Given the heightened risks, traders should be cautious and wait for clear confirmation signals before taking positions.
Closely follow news related to the debt ceiling, economic data, and geopolitical events.
Disclaimer: This analysis is for informational purposes only and does not constitute financial advice. Trading involves substantial risk and may not be suitable for all investors. Conduct your own research and consult with a financial advisor before making any investment decisions. Long 
Short 
Short 
Long 
Euro Soars with Dollar WoesOne thing about tables, they turn. This time last year, the dollar was unrivalled. Now, it is being challenged amid a banking crisis, recessionary fears, and a debt ceiling drama.
Having stepped up on the rates faster than the rest, the US Fed’s combat against inflation fuelled a dollar rally . It now finds itself between a hard place and a rock. Many expect the Fed to pause.
In contrast, the ECB, having been slower off the block, has gradually lifted rates with ample headroom for further policy intervention to fend off a resurgent Euro area inflation.
This paper explores fundamental forces driving a rally in the Euro and the headwinds facing the dollar.
With EUR/USD making a golden cross on March 27th, this case study posits a long position in Euro using the CME Euro FX Futures delivering a 3x reward to risk ratio with entry at 1.1025 and target of 1.17 hedged by a stop at 1.08.
Crushed and Bruised Euro is Fighting Back
2022 was a crushing year for the Euro. Geopolitics plunged Europe into an energy crisis. Bleak prospects plus soaring inflation meant deep recession. The Euro was wounded.
The Euro was dealt another blow as the ECB was slow to lift rates. Key eurozone rates were well below those in the US, as the Fed was all pedal to the metal with unprecedented hikes.
Higher yields in the US attracted foreign funds, boosting the dollar at the expense of other currencies.
Tables turn and times change. Euro's rise is in part thanks to milder European winter. Warmer than normal and prudent energy consumption has kept gas prices in check. The region may well avoid a recession. In fact, it posted a surprise output growth in the final quarter of last year.
A hawkish ECB also well supports the Euro. It continues to hike rates to tackle inflation, which remains stubbornly high.
As rates in Europe rise while those in US stall, the Euro will attract capital inflows from across the Atlantic.
Dollar’s dominance is being challenged
Over the last 10 years, the Dollar Index (DXY) has gained ~25% while the EUR/USD has shed ~19%.
The rotation away from the dollar is underway. Not only Euros, but the dollar has also been losing ground against other majors, including the sterling and the yen.
Easing inflationary pressures should spell victory for the Fed allowing it to tone down its fighting monetary stance.
Premium for insuring against US government default spiked to its highest level in more than a decade amid political impasse related to debt ceiling. While this political embarrassment is likely to be inconsequential, the tiny risk of a dollar debacle cannot be ignored. Investors hedging against this risk are likely to push the dollar lower.
Is this De-dollarisation?
The de-dollarisation camp shouts loud. But ignore the noise.
Surely, the weaponisation of the dollar has alarmed nations. Not surprisingly, many are attempting to wean away from dollar dependence for trade settlement.
The dollar’s share in forex reserves used to be 71.5% at the turn of the century and has gradually declined to 58.3% as of the end of 2022.
The dollar remains at the core of global trade and finance. The dollar forms 88% of FX transactions. Distant second is Euro at 31%, according to 2022 BIS figures (aggregates equal 200% as each transaction involves two currencies).
Transactions involving the Chinese yuan having grown at 70% over last three years represents a mere 7% of the total.
About 60% of the world's forex reserves aggregating to USD 11 trillion are still denominated in dollar.
The dollar will continue to play a pre-eminent role in global trade and as a global reserve for a long time to come. Absent a credible alternative, albeit weakened, the dollar is here to stay.
Rate Expectations Point to the Fed Pausing Earlier Than ECB
CME’s FedWatch tool shows a 78% probability of another 25bps rate hike at the next meeting on May 3rd and a 67% probability of no rate hike at the June meeting. Fed pause before pivot remains market expectations.
Meanwhile, Reuters reported that the ECB is expected to raise rates by 25bps at its next meeting in May. Crucially, ECB survey of professional forecasters points to another 25bps rate hike in Q2 before pausing.
Asset Managers & Funds are positioning for Euro to rally
CFTC’s Commitment of Traders (CoT) report shows that leveraged funds and asset managers are bullish Euro. Asset managers increased net longs by 7.4% over the last 12 weeks. Leveraged funds have flipped from net short to net long, increasing long positioning by 125%.
Meanwhile, the CoT for DXY futures shows that asset managers are still net long but have reduced long positions by 20.5%.
Options Market are signalling bullish Euro and bearish Dollar
Monthly options on Euro FX futures are trading with a put-call ratio of 0.87 pointing to more calls than puts, indicating Euro bullishness. Euro buoyancy is particularly apparent for June expiry options which have a put-call ratio of 0.6.
Meanwhile, thinly traded options on DXY futures expiring in June have a put-call ratio of 1.66 signalling that market participants are bearish dollar with 1.66 puts for every call option.
Trade Setup
Each lot of CME Euro FX Futures provides exposure to 125,000 Euros. Every 0.00005 increment in the contract represents a trading P&L of USD 6.25.
● Entry: 1.1025
● Target: 1.17
● Stop: 1.08
● Profit at target: USD 8,440
● Loss at stop: USD 2,810
● Reward-to-risk: 3x
MARKET DATA
CME Real-time Market Data helps identify trading set-ups and express market views better. If you have futures in your trading portfolio, you can check out on CME Group data plans available that suit your trading needs www.tradingview.com
DISCLAIMER
This case study is for educational purposes only and does not constitute investment recommendations or advice. Nor are they used to promote any specific products, or services.
Trading or investment ideas cited here are for illustration only, as an integral part of a case study to demonstrate the fundamental concepts in risk management or trading under the market scenarios being discussed. Please read the FULL DISCLAIMER the link to which is provided in our profile description.  Long

The USD, China and the De-dollarization challengeThe US dollar has maintained its status as the world's dominant reserve currency for decades, thanks to its perceived security, resilience, and the depth and liquidity of US markets. Despite concerns surrounding the dollar's hegemony, it remains a crucial player in global transactions. Meanwhile, China's economy faces challenges, such as growing provincial government debt, an expanding real estate bubble, and potentially inflated GDP numbers. In addition, China's need for US dollars and the push for de-dollarization by countries like Russia, China, Iran, and Saudi Arabia have gained attention. This analysis will explore these issues in depth and examine why moving away from the US dollar system is complex.
China's increasing debt, falling real estate prices, and the growth of its banking assets to around 55% of Global GDP are all causes for concern. The country's M2 money supply has grown at a 9% yearly rate, reaching HKEX:40 trillion, more than double its GDP. If China's GDP numbers are indeed inflated, as suggested by the Brookings Institution, this could exacerbate the problem. Moreover, the yuan (RMB) faces significant challenges in becoming a globally accepted reserve currency, primarily due to China's capital controls, illiquid markets, and authoritarian governance.
In contrast, the US dollar remains dominant in global central bank reserves and transactions. This is partly due to the dollar's resilience and the perception of the US's security and stability. Although reserves have shifted for countries with closer trade relations with China, such as Indonesia, Malaysia, Hong Kong, Singapore, and Chile, the US dollar remains the world standard for now.
The push for de-dollarization has gained momentum recently, particularly after the Russia-Ukraine conflict and Western sanctions against Russia. Countries like Russia, China, Iran, and Saudi Arabia seek to move away from the US dollar system to reduce their dependency on the US economy and gain more control over their financial systems. However, moving away from the US dollar system is challenging for several reasons.
First, the US dollar's dominance in global markets ensures its continued importance in international trade. Even if countries like China and Russia attempt to shift away from the dollar, many other countries will likely continue to rely on it for their transactions, as it provides stability and liquidity.
Second, while the yuan is gaining prominence as a reserve currency, it still faces significant hurdles in becoming a globally accepted alternative to the US dollar. China's capital controls, illiquid markets, and authoritarian governance make it difficult for other countries to trust the yuan as a reliable reserve currency. As a result, it is unlikely to replace the US dollar on a large scale in the foreseeable future.
Third, OPEC members continue to price their oil in US dollars, despite the currency's decline relative to other world currencies. Economic, technical, and political factors prevent them from switching to other currencies or a basket of currencies. The benefits of such a switch are limited, and it would not benefit all OPEC members equally. Furthermore, the US will unlikely allow OPEC to disregard the dollar without consequences.
Finally, the BRICS nations (Brazil, Russia, India, China, and South Africa) are reportedly considering creating a new currency to facilitate trade and promote de-dollarization. However, this plan faces several obstacles, such as political disagreements among the BRICS countries and convincing other nations to adopt this new currency. Additionally, the benefits of a new BRICS currency are uncertain, and it may not be enough to destabilize the US dollar's dominance in global markets.
In conclusion, while there are signs of a shift in the balance of global reserve currencies, it is premature. Long 

 Long