Is Palantir a Software Empire or a Consulting Firm?Palantir's market capitalization has surpassed $ 400 billion, with investors pricing in growth through 2032. The article argues that this multiple rests on narrative momentum rather than defensible economics. Elevated bond yields and persistent inflation compress speculative multiples, while higher discount rates erode the present value of distant cash flows. Michael Burry called the company an AI FOMO consultant and warned the valuation could fall below 100 billion dollars. The operating data supports the structural case. Palantir reports a deferred revenue-to-revenue ratio near 32%, compared with 80% to 207% among enterprise SaaS peers, and almost exactly matching Accenture's 31%.
The intellectual property analysis exposes the sharpest gap in the AI story. GreyB catalogs more than 3,800 global filings, with over 72% covering data analysis technologies and 62% covering digital data processing. Those patents protect database structures, user interfaces, and authorization controls, not foundational model architecture. Google DeepMind, by contrast, owns core patents in deep reinforcement learning, actor-critic networks, continuous control and neural compression. Palantir connects third-party foundation models to customer databases. It does not invent the algorithmic science that powers them.
Two recent developments attack the moat directly. Technologist Bilawal Sidhu built WorldView, a browser-based spy satellite simulator, in a matter of days using Google 3D Tiles, WebGPU rendering, and open-source intelligence feeds. A single engineer replicated the geospatial interface that Palantir long treated as untouchable. On the government side, Google launched Gemini 3.8 Flash Cyber for defense cybersecurity through its restricted Fairwind Program, claiming stronger performance at materially lower cost. Palantir shares fell 7% on the news, and institutional traders bought millions of dollars in protective puts.
Balance sheet detail reinforces the consulting profile. Accounts receivable climbed to 1.49 billion dollars, and one commercial customer holds 27% of that balance while contributing under 10% of recognized revenue. That imbalance hands the customer real leverage in any contract renegotiation. Nine billion dollars in net operating loss carryforwards shield federal cash taxes only temporarily, and heavy stock-based compensation dilutes holders over time. Morgan Stanley has downgraded the stock, and Alex Karp himself conceded that roughly 95% of enterprise AI pilots fail. As AI budgets rationalize, buyers will reprice expensive bespoke engineering work.  Short

What Is Tesla Really Building for $16.8 Billion?Tesla is no longer defined by the cars it sells. The Air Force requested Cybertrucks as live-fire missile targets at White Sands, citing the angular stainless steel exoskeleton and the 48-volt electrical architecture. Chechen forces have already mounted heavy machine guns on Cybertrucks for tactical testing. Separately, Elon Musk's xAI secured Pentagon approval to deploy Grok inside classified systems covering intelligence analysis, weapons development, and battlefield software. Tesla vehicles now ship with factory-integrated Starlink antennas. The company is embedding itself into global security infrastructure, not just consumer transport.
The core automotive business tells a harder story. Deliveries fell for two consecutive years after the 2023 peak, and the Model 3 and Model Y show clear signs of aging. Management cut prices and introduced low-rate financing to defend demand. Those moves compressed vehicle gross margins across key international regions. The Cybertruck still faces demand constraints, recalls, and production scaling obstacles. Tesla discontinued the Model S and Model X to free up assembly space for humanoid robotics. Tesla holds roughly $43.5 billion in cash, but expanding capital expenditure now pressures free cash flow.
Terafab is the clearest expression of the new strategy. Tesla and SpaceX jointly committed $16.8 billion to a chip plant in Grimes County, Texas, spanning over 100 million square feet. The site integrates logic, memory, advanced packaging, and testing under one roof and draws industrial water from Gibbons Creek Reservoir to preserve local groundwater. The initial bill alone exceeds four times Tesla's trailing twelve-month net income, and Tesla's share consumes roughly two-thirds of its annual capital budget. Tax filings suggest multi-phase spending could eventually reach $119 billion. Terafab must supply custom silicon for Optimus, Cybercab, and orbital data centers, with no obvious fallback supplier.
The execution gap sits in autonomy. Tesla relies exclusively on camera-based vision and excludes LiDAR and radar to keep manufacturing costs down. Waymo has completed over 200 million autonomous miles and generates 500,000 paid rides weekly. Tesla recorded 2.4 million paid robotaxi miles across 20 to 40 active vehicles, and legacy Hardware 3 chips lack the memory bandwidth for unsupervised driving. BYD holds 1,117 battery patents against Tesla's 97, and the PTAB has invalidated challenged AI patents over prior art. Robotics and autonomous software now carry over 40% of estimated enterprise value, against roughly 34% for automotive. Regulatory approval, not engineering ambition, is the binding constraint on the entire thesis.  Long

 Long
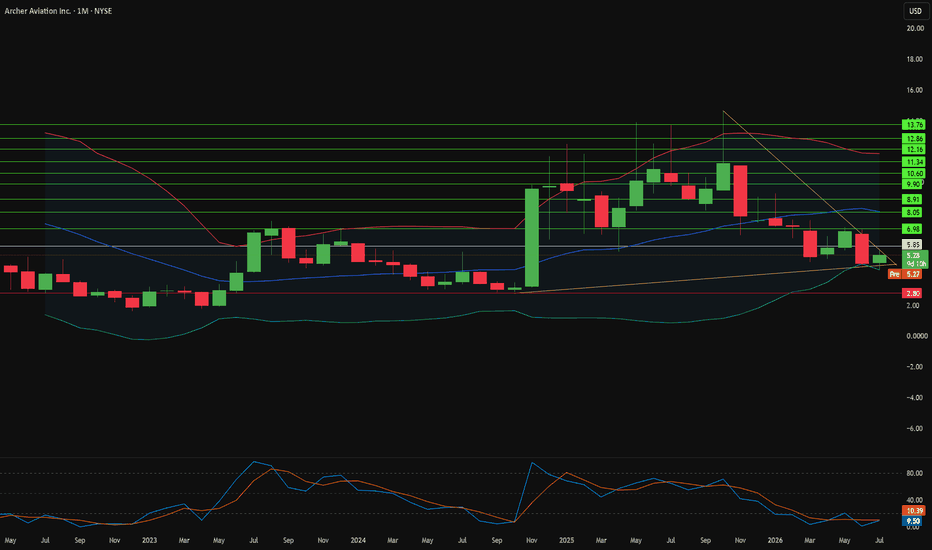
Can One Defense Deal Rewrite Archer Aviation's Future?Archer Aviation (NYSE: ACHR) is repositioning itself from a pure-play air-taxi manufacturer into a dual-use aerospace ecosystem, teaming with defense technology firm Anduril Industries to unveil "Thunder," an autonomous Group 5 attack rotorcraft built on the same hybrid-electric architecture as Archer's civilian aircraft. Investors reacted enthusiastically: shares jumped nearly 20% following the announcement at the Farnborough International Airshow, even though the stock remains down sharply for the year. The defense variant can carry heavy weapons payloads, including Hellfire missiles, and fits inside a standard shipping container for rapid field deployment; critically, it bypasses the multi-year FAA passenger-certification process weighing on Archer's commercial timeline.
The financial backdrop explains why that shortcut matters so much. In Q1 2026, Archer generated just $1.6 million in revenue, up from $0.3 million the prior quarter and ahead of the roughly $0.9 million analysts had expected, while net loss widened to $217.7 million as R&D and certification spending accelerated. Adjusted EBITDA loss came in at $172.5 million, within management's guidance range, and the company still holds about $1.8 billion in liquidity, implying a runway of roughly two and a half years at the current burn rate. The Anduril partnership offers a faster, non-FAA revenue channel that could start contributing well before Archer's flagship air taxi, Midnight, reaches full commercial service.
Beyond defense, Archer is building several other growth levers. The company unveiled its own aviation-specific AI model, "Zee," designed to run offline onboard the aircraft and eventually be licensed to airlines. It also launched a charging-infrastructure consortium, ACES, with BETA Technologies and Macquarie Capital, targeting 250 sites by 2030 a strategy management explicitly models on Tesla's early Supercharger rollout. On the regulatory front, Archer became the first eVTOL company to close FAA Phase 3 type certification and secured a streamlined path in the UAE for early commercial Midnight flights.
Taken together, Archer's pitch has shifted from "when will passenger air taxis fly" to "how many revenue streams can this platform generate before that happens." Whether Thunder, Zee, and ACES can close a $217 million quarterly loss is the bet investors are now pricing in.  Long
Is Kratos Defense the Ultimate Space Warfare Stock?Global conflict shifts toward autonomous systems and orbit-based warfare in 2026. Savvy investors are focusing on Kratos Defense & Security Solutions (NASDAQ: KTOS). High-profile backers like Cathie Wood’s Ark Invest recently purchased $9.1 million of Kratos stock. Kratos also just won a prime $100 million sole-source Space Domain Awareness contract. Kratos is rapidly becoming a premier supplier for national defense recapitalization. This article analyzes how Kratos positions itself to lead modern defense across multiple sectors.
Geopolitics and Geostrategy
Great power competition drives the current geopolitical landscape. The United States, China, and Russia fight for dominance in orbit. Space is now a contested combat domain. Consequently, geostrategy demands continuous orbital tracking and threat detection. Kratos’s ground-based space monitoring networks provide vital intelligence. These systems protect US strategic satellites from adversarial interference. By securing orbital communication lines, Kratos fundamentally shapes global power balances. The company ensures allied nations maintain operational superiority in high-stakes environments.
Macroeconomics and Economics
High defense spending remains a global macroeconomic certainty. Governments globally prioritize military readiness over other fiscal concerns. This environment shields defense contractors from broader economic recessions. Kratos reports impressive financial performance in 2026. The company forecasts full-year revenues between $1.7 billion and $1.76 billion. High capital expenditures represent a strategic investment in scaling production. Kratos converts its record-high order backlog into highly profitable revenue streams. Investors value Kratos as a high-growth asset in a volatile economy.
Industry Trends and Business Models
Legacy defense firms construct expensive, slow-to-build hardware. In contrast, Kratos embraces a disruptive commercial business model. The company prioritizes affordability as its core technology. Kratos designs systems up front for rapid, low-cost mass production. The Pentagon increasingly demands cheaper, disposable hardware. This industry trend perfectly aligns with Kratos’s portfolio. Kratos manufactures low-cost jet drones like the XQ-58 Valkyrie. The company also produces affordable Spartan turbojet engines. This model allows rapid scaling to meet surging global demand.
Management, Leadership, and Company Culture
CEO Eric DeMarco advocates a culture of bold innovation. Kratos operates like a venture-backed tech startup. Leadership focuses on internally funded research and development. This strategy bypasses sluggish government development timelines. Management executes decisions rapidly to outpace larger rivals. Employees share a mission-driven culture focused on national security. Leadership designs the workspace to attract top-tier aerospace engineers. Kratos nurtures an environment where fast execution drives strategic success.
Technology, High-Tech, and Science
Kratos operates at the absolute cutting edge of aerospace science. The company develops hypersonic vehicles and advanced propulsion systems. Kratos recently selected Indiana for its Project Helios test facility. This mid-tier coupled arc jet facility accelerates hypersonic testing. Furthermore, Kratos pioneers virtualized space networks. These software-defined networks replace legacy hardware-heavy systems. Kratos’s high-tech solutions solve complex aerothermal and digital challenges. Scientific rigor keeps Kratos ahead of potential global adversaries.
Cybersecurity and Digital Systems
Modern warfare relies heavily on digital connectivity. However, digital systems invite severe cyber threats from hostile nations. Kratos leads the defense sector in robust cybersecurity solutions. The company builds highly secure satellite ground networks. Kratos encrypts vital telemetry, tracking, and control systems. Its software prevents malicious actors from hijacking military satellites. By securing data flows, Kratos protects global military operations. Cybersecurity remains a foundational pillar of Kratos’s technology stack.
Pharmaceutical and Bio-Defense
No direct link connects Kratos to commercial drug manufacturing. However, Kratos plays an indirect role in biochemical defense. The company manufactures mobile C5ISR shelters with CBRN protection. CBRN stands for chemical, biological, radiological, and nuclear defense. These specialized shelters protect sensitive personnel and medical equipment. They shield critical assets from biological weapons and toxic agents. Kratos protects the research infrastructure that fights biological warfare. In this way, Kratos secures the biodefense and pharmaceutical frontlines.
Patent Analysis and Intellectual Property
Patent analysis highlights Kratos’s aggressive intellectual property strategy. The company holds numerous patents in jet propulsion and telemetry. Kratos systematically patents its modular, low-cost drone designs. This proprietary technology blocks competitors from copying its affordable manufacturing processes. Kratos continuously files new patents in hypersonic design and satellite software. These patents safeguard Kratos’s first-mover advantage in high-growth fields. Investors trust Kratos because its patented innovations secure market dominance.  Long

Can Palantir Really Reach a $400 Billion Valuation?Palantir Technologies is rapidly dominating the enterprise software landscape. Wall Street analysts project a staggering $400 billion market capitalization by next year. The company is shedding its old reputation as a mere government contractor. Today, Palantir serves as the foundational operating system for global industries.
Geopolitics and Geostrategy
Global conflicts weaponize information. Western defense agencies rely heavily on Palantir Gotham to process battlefield data. The company acts as a geostrategic deterrent in modern electronic warfare. Palantir aligns its corporate mission directly with Western democratic institutions. Consequently, authoritarian regimes cannot purchase its software. This firm ideological stance guarantees steady, long-term government defense revenue.
Macroeconomics and Economics
Stubborn inflation forces corporations to maximize operational efficiency. Palantir capitalizes heavily on this harsh economic climate. Its Artificial Intelligence Platform (AIP) delivers rapid, measurable cost savings. During market downturns, enterprises cut experimental tech spending. However, companies aggressively increase investments in proven data infrastructure. This macroeconomic shift fuels Palantir’s explosive financial growth.
Industry Trends and Business Models
Enterprise software is pivoting toward autonomous, agentic operations. Palantir leads this trend through its innovative Foundry platform. Its unique business model focuses on rapid deployment via targeted boot camps. These interactive sessions turn hesitant prospects into paying customers within days. Commercial revenue now matches government intake. Palantir expands globally, landing major Latin American deals like Mexico's GNP Seguros.
Management, Leadership, and Culture
CEO Alex Karp rejects conventional Silicon Valley corporate norms. He actively fosters an aggressive, mission-driven engineering culture. This unique leadership style prizes critical thinking over corporate conformity. Palantir attracts elite tech talent seeking high-impact, real-world challenges. Management empowers small engineering teams to build decentralized solutions. This lean organizational design guarantees rapid product iteration cycles.
Technology, Science, and High-Tech
Palantir builds highly advanced data integration plumbing. Its new AIP Analyst tool allows non-technical workers to query data using plain language. The platform integrates machine learning with complex physical science workflows. Aerospace and supply chain sectors use it to map molecular-level dependencies. Palantir transforms raw enterprise data into a dynamic, living digital twin. This technological leap changes how humans interact with machine intelligence.
Cybersecurity and Data Governance
Modern cyber threats bypass traditional network perimeters. Palantir enforces absolute security through granular, cell-level data permissions. The platform provides flawless data traceability and immutable compliance audits. Hackers cannot easily compromise decentralized, highly governed networks. Companies manage sensitive consumer records securely while deploying advanced AI tools. Palantir proves that rapid automation requires bulletproof data governance.
The Pharmaceutical Connection
The pharmaceutical sector relies on Palantir to accelerate drug discovery. Researchers unify disparate genomic datasets, clinical trials, and manufacturing supply chains. Palantir helps scientists identify promising chemical compounds years ahead of schedule. Healthcare titans optimize distribution networks during global supply shocks. Consequently, life-saving medications reach patients with unprecedented speed.
Patent Analysis
Intellectual property securement drives Palantir's competitive moat. Patent filings show heavy investment in ontology-based data structures. The company aggressively patents proprietary methods for multi-layer data synchronization. These patents prevent competitors from replicating Palantir’s core data integration architecture. Analysts view this robust patent portfolio as a massive barrier to market entry. Innovation ownership guarantees long-term commercial dominance.
Long 
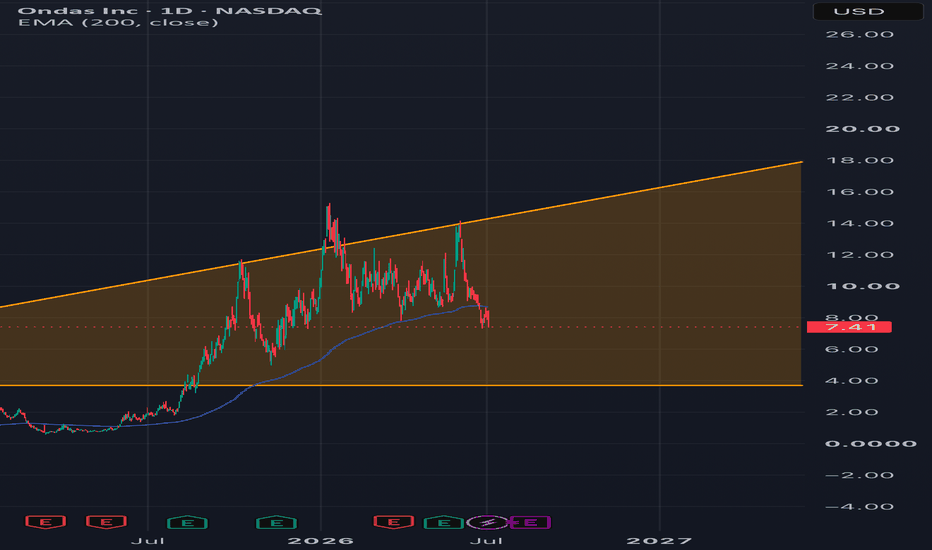
$ONDS:Violent pullback inside a much bigger structural upptrendThe chart tells the story clearly: Ondas rallied hard off its 2025 base, spiking above $15 before snapping back sharply a -46.6% drawdown in just 22 bars/34 days, now sitting in the $7.25–$8 zone. That's a brutal correction on the surface, but it's landing right at the lower boundary of the ascending structure that's been building since the initial breakout the kind of higher-timeframe trendline test that often marks "shake the weak hands" territory rather than trend failure. The rising channel projects well into the mid-teens and beyond if the structure holds, which lines up with where Wall Street's price targets already sit.
Why the pullback looks more like noise than a broken thesis:
The drawdown has a clear, mechanical explanation not deteriorating fundamentals. Insider and legacy-holder selling (CEO Eric Brock's $31.9M sale, resale registrations tied to the Omnisys and World View acquisitions) created real supply overhang and spooked short-term traders. That's dilution pressure, not a demand problem.
Meanwhile, the actual business is accelerating:
→ $40M+ in new orders for autonomous defense systems in June alone, driven by surging demand for loitering munition systems across Europe and the U.S.
→ A new collaboration between Ondas's Sentrycs and Lockheed Martin — serious validation from a top-tier defense prime.
→ The Cyberhawk acquisition pushes Ondas into critical infrastructure intelligence (software, data, AI) — a new analyst initiated coverage with a Buy rating specifically citing this synergy.
→ World View (Ondas subsidiary) was selected as the stratospheric high-altitude balloon provider for U.S. Naval Forces.
→ New "Autonomy at First Contact" defense systems launched at Eurosatory 2026, Europe's premier defense expo.
→ Last quarter's numbers were staggering: revenue +605% YoY, +66% QoQ, with EPS blowing past estimates ($0.81 actual vs. -$0.05 expected).
→ Analyst consensus sits at Strong Buy, with price targets ranging $16–$25 — 2x to 3x+ from current levels.
The setup:a name with real revenue acceleration and defense-sector tailwinds (drone/autonomous systems demand isn't slowing down globally) getting knocked down by supply-side noise rather than a broken story. That's historically the type of dip that gets bought once the selling pressure exhausts itself watch for the insider/resale overhang to clear and volume to confirm support here before the next leg.
Risk to manage: further share sales under the Form 144 filing could keep a lid on rallies short-term, and next earnings (Aug 17) will be the real test of whether the growth trajectory holds.
*Not financial advice for educational/discussion purposes.*
Stay vigilant!  Long
Can AeroVironment Monopolize Drone Warfare?Geopolitical and Geostrategic Catalysts
AeroVironment plays a pivotal role in modern global conflicts. Geopolitical tensions drive unprecedented demand for autonomous systems. The company recently signed a memorandum of understanding with Taiwan's Ubiqconn. This partnership builds a common controller ecosystem for Taiwan's indigenous drone program. Furthermore, global conflicts prove that inexpensive drones can saturate traditional air defenses. AeroVironment answers this strategic threat directly. Allies urgently require both offensive loitering munitions and robust counter-drone technology. The company perfectly positions its portfolio to secure contested international airspaces.
Macroeconomics and Industry Trends
Modern warfare shifts toward decentralized, uncrewed systems. Defense departments globally reallocate capital to counter low-cost airborne threats. This secular trend provides massive macroeconomic tailwinds for AeroVironment. Wall Street notices this structural growth. Wedbush recently initiated coverage on the stock with an Outperform rating. The company's revenue surged one hundred and seventeen percent over the past twelve months. Total trailing revenue reached one point sixty-one billion dollars. AeroVironment recently reported a blowout quarter, causing the stock to soar. The market rewards companies with clear visibility and high-margin backlogs.
Disruptive Business Models and Financial Strength
The company thrives on high-value, firm-fixed-price government contracts. The U.S. Army recently awarded AeroVironment a five hundred million dollar counter-drone contract. This firm-fixed-price agreement secures long-term revenue visibility through June 2029. Financially, the company remains exceptionally robust. It maintains an impressive current liquidity ratio of five point fifty one. This liquidity allows aggressive internal investment without taking on dangerous debt. The company scales its business model through modular, software-defined architectures. This strategy ensures high asset efficiency and rapid deployment timelines.
Visionary Leadership and Corporate Culture
CEO Wahid Nawabi guides the company through this hyper-growth phase. Management aggressively expands production capabilities to meet skyrocketing military demand. For instance, the company is expanding its Huntsville, Alabama facility by twenty-four thousand square feet. This facility accelerates production of the Freedom Eagle-1 interceptor missile. Nawabi's leadership fosters a fast-paced culture of rapid iteration. The corporate culture focuses entirely on mission readiness and warfighter survivability. This clear alignment creates high employee engagement and drives continuous operational excellence.
High Tech Innovation, Science, and Patents
AeroVironment aggressively protects its technological moat through deep scientific research. The U.S. Air Force and Space Force recently awarded the company twenty million dollars. This contract funds advanced ceramic materials research for hypersonic environments. Additionally, the company integrated the Panther phased array antenna on Skyrange platforms. This forty-three million dollar project enhances hypersonic telemetry capabilities. The company continuously files patents for these advanced aerospace designs. This robust intellectual property portfolio prevents competitors from easily replicating its hardware. AeroVironment turns complex science into practical battlefield dominance.
Cyber Security and Artificial Intelligence at the Edge
Modern drones require resilient digital architecture to survive electronic warfare. AeroVironment continuously upgrades its digital defenses against cyber threats. The company recently expanded its AV_Halo platform. They integrated new software called Instinct and Detect. These tools enable faster, resilient decision-making directly at the tactical edge. Artificial intelligence autonomously detects, classifies, and tracks threats in real time. This localized processing shields the system from communication jamming. The software-defined front end ensures maximum protection against hostile cyber intrusions.
Cross Industry Parallels: Biology and Defense
AeroVironment operates outside the traditional pharmaceutical industry. However, its strategic approach shares deep conceptual parallels with modern immunology. Drone swarms function similarly to dynamic, mutating biological pathogens. Traditional defenses fail against such rapid, multiplying airborne threats. AeroVironment designs the Freedom Eagle-1 as a precise technological antidote. The system identifies and neutralizes airborne threats like antibodies targeting a virus. This systemic approach treats airspace defense as a problem of automated inoculation.  Long
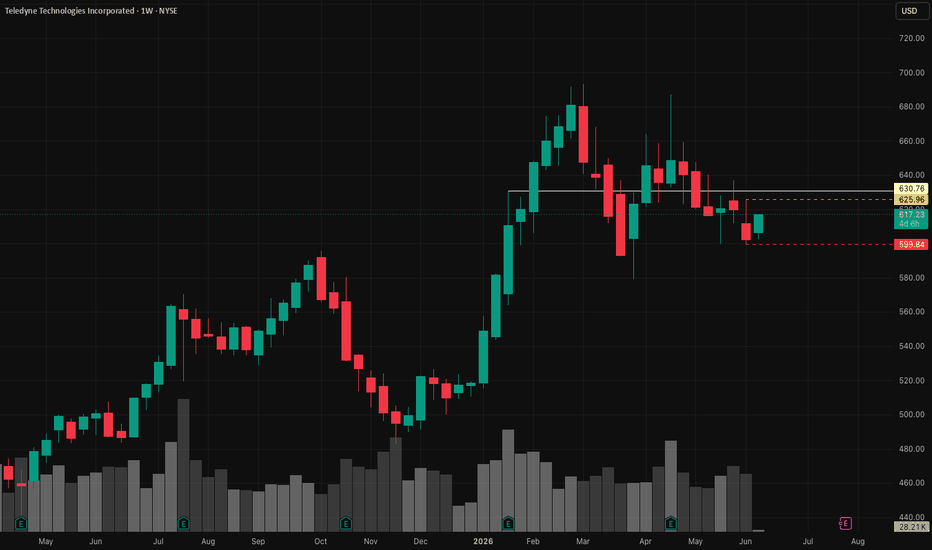
Can Lockheed Turn Defense Demand Into Deliveries?Lockheed Martin is converting a structural surge in defense demand into durable, multi-year revenue, and the clearest evidence arrived on June 24. The U.S. government awarded the company a seven-year contract worth up to $35 billion to quadruple production of THAAD missile-defense interceptors, the kind of backlog that makes defense cash flows predictable into the early 2030s. The timing is not accidental. The 2026 Iran war drew down U.S. THAAD interceptor stocks heavily, exposing munitions shortfalls and creating the precise demand signal Lockheed is now monetizing. One caveat belongs up front: the award is undefinitized and capped at "up to" $35 billion, with only $843 million obligated initially, so it is a strong demand signal rather than fully committed cash.
The more telling story is how Lockheed intends to deliver. The company is investing more than $9 billion through 2030 to build or modernize over 20 US facilities, and in June it signed a memorandum of understanding with GM Defense to graft automotive-style, high-rate manufacturing onto defense production. This is a deliberate shift away from slow, low-volume assembly toward scalable output, aimed directly at the munitions shortfalls the defense industrial base has struggled to fill. Demand is no longer the constraint; execution is.
Beyond the core franchise, Lockheed is building optionality in next-generation capabilities. It plans to flight test the extreme-range AGM-158XR cruise missile with the Air Force by year's end, it continues to develop affordable hypersonic glide bodies, and in May it joined Firefly Aerospace and Seagate Space to pursue sea-based launch using an offshore platform and Firefly's Alpha rocket. None of these is yet a material revenue line. Together, though, they position Lockheed across the capabilities that Western militaries are prioritizing: long-range strike, hypersonics, and responsive space launch.
The investment case is a defensive, backlog-anchored compounder riding a structural defense upcycle. Inelastic government demand, a multi-year order book, a 2.74% dividend yield, and more than two decades of consecutive dividend increases make Lockheed a haven for risk-averse capital. The caveats are real but manageable: the headline THAAD figure is a ceiling rather than obligated cash, and both the manufacturing pivot and the new partnerships are early-stage. That makes execution, the ability to scale production fast enough to turn backlog into deliveries, the central risk. For investors, the question is less whether the demand exists than whether Lockheed can build quickly enough to meet it.  Long

 Long
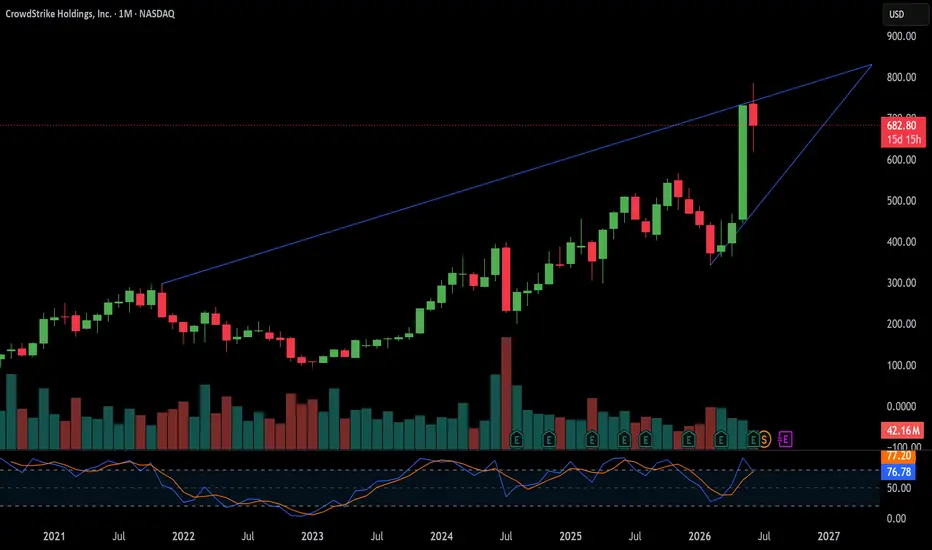
Why Will CrowdStrike Rule the AI Era?CrowdStrike continues to defy market gravity. The stock now trades above the $680 level after reaching highs near $785. Institutional investors now aggressively accumulate these cybersecurity shares. Why does this tech giant command such massive market influence? AI integration and hyperscale datacenter expansion drive this unprecedented growth. Analysts upgrade CrowdStrike stock continuously. Yet, deeper systemic forces fuel this rapid ascent. We must analyze this titan across multiple crucial domains. You will soon understand how CrowdStrike builds its unassailable defensive moat.
Geopolitics and Geostrategy
Global conflicts now erupt heavily in digital realms. Nation-state actors weaponize code to destabilize rival global economies. CrowdStrike acts as a digital shield for vital global infrastructure. The platform tracks sophisticated adversarial tactics worldwide. Geostrategy dictates that digital supremacy ensures absolute national security. CrowdStrike aligns its threat intelligence with Western defense priorities. The company effectively neutralizes borderless digital threats instantly. This strategic alignment secures massive governmental security contracts.
Macroeconomics and Economics
Cybersecurity stands immune to traditional macroeconomic headwinds. Global data centers will dramatically expand their capacity by 2027. This expansion requires massive capital expenditure from tech giants. It also mandates unbreakable digital security layers. CrowdStrike capitalizes brilliantly on this harsh economic reality. The firm extracts enormous value from shifting corporate IT budgets. High inflation rarely deters companies from protecting their core assets. Economic models show that cybersecurity spending only accelerates over time.
Business Models and Industry Trends
The software-as-a-service model provides massive financial leverage. CrowdStrike utilizes unified, cross-cloud capabilities to dominate the sector. Clients easily manage network security through a single interface. Current industry trends demand consolidated security architectures. CrowdStrike eliminates clunky legacy systems seamlessly. The company secures recurring revenue through essential subscription services. Institutional buyers recognize this efficient cash-generating machine. Buy-on-the-dip strategies clearly define current investor behavior.
Management, Leadership, and Company Culture
Visionary leadership constantly propels CrowdStrike forward. Executives execute with discipline amidst intense global market pressure. Management fosters a relentless company culture focused on winning. Teams prioritize speed, absolute accountability, and bold thinking. This competitive environment accelerates continuous company innovation. Employees eagerly solve complex security puzzles every single day. Leadership effectively balances aggressive growth with sustainable execution. This sharp operational focus deeply delights institutional shareholders.
Technology, Cybersecurity, and High-Tech
Modern high-tech infrastructure demands elite cybersecurity protocols. CrowdStrike deploys lightweight sensors across millions of digital endpoints. The underlying technology detects network anomalies in mere milliseconds. Artificial intelligence algorithms instantly quarantine highly suspicious activities. You cannot separate AI software stacks from robust digital security. Without proper protection, attackers easily corrupt crucial data models. CrowdStrike works to protect the integrity of these advanced technological ecosystems. The platform adapts dynamically to unknown threats.
Science and Patent Analysis
Deep computer science principles underpin the entire software platform. Engineers apply advanced machine learning models to predict attacks. The company fiercely protects its valuable intellectual property. Rigorous patent analysis reveals an incredibly deep defensive moat. CrowdStrike owns vital patents covering behavioral analytics and threat detection. Competitors severely struggle to bypass these legal and technical barriers. Scientific rigor ensures flawless precision during malware threat detection. The firm consistently outpaces rival algorithmic development.
What Could Break the CrowdStrike Thesis?
CrowdStrike's record is not spotless. On July 19, 2024, a faulty Falcon Sensor update crashed roughly 8.5 million Windows systems worldwide. Reporting called it the largest IT outage in history. The failure grounded flights, froze banks, and disrupted hospitals across multiple countries.
Delta Air Lines cancelled about 7,000 flights and pegged its losses near $550 million. Delta then sued CrowdStrike for gross negligence and computer trespass. In May 2025, a Georgia judge allowed those claims to proceed. The case remained open in 2026, and CrowdStrike has countersued. A separate shareholder securities class action was dismissed in early 2026.
This is the core execution risk for the stock. One untested update can erase quarters of customer trust. Investors should weigh this fragility against the bullish moat narrative. Concentration in a single sensor architecture cuts both ways.
Conclusion
CrowdStrike operates far beyond a simple software vendor. It represents a foundational pillar of the modern digital economy. The company perfectly aligns technology, strategy, and business execution. Investors should expect continued market dominance in the coming years. As the AI revolution expands, CrowdStrike will securely protect the future.  Long

 Long

What Sparked Infleqtion's 314% Quantum Rally?Infleqtion (NYSE: INFQ) recorded a staggering 314 percent stock surge to $14.70, driven by a landmark Letter of Intent with the U.S. Department of Commerce proposing a $100 million CHIPS Act investment. The funding follows a milestone-based distribution model, with the government receiving Infleqtion common stock at a 15 percent market discount, held strictly on a passive basis. The deal validates quantum technology as a critical national security asset and accelerates Infleqtion's domestic expansion across Boulder, Chicago, and Madison. The company recently transitioned to public markets via Churchill Capital Corp X, following a successful $100 million Series C round anchored by Glynn Capital and Counterpoint Global. The appointment of former Morgan Stanley executive Nicholas Johnson to the Board signals an aggressive growth and capital markets strategy.
At the technological core, Infleqtion champions neutral-atom quantum architecture that operates at room temperature, eliminating the costly cryogenic infrastructure required by superconducting competitors. The company's dual-species rubidium and cesium atom arrays achieved a record 0.975 inter-species entangling gate fidelity, with Clifford gate fidelities exceeding 0.9996 and coherence times reaching 33.5 seconds for cesium qubits. Chief Scientist Mark Saffman has outlined a path to 99.9 percent gate fidelity, strengthening the roadmap toward fault-tolerant quantum computing. The hardware portfolio targets multiple high-value verticals, including the Tiqker optical atomic clock, Quantum Spectrum (a Rydberg atom-based RF sensing platform that tunes from hertz to terahertz inside a single aperture), and Superstaq, the hardware-agnostic software stack now integrated into Morningstar's investment analytics platform serving 17,000 institutional users.
Geopolitically, Infleqtion is positioned at the convergence of escalating GPS vulnerability and allied defense modernization. The Eastern Mediterranean, Port of Haifa, and Ben Gurion Airport face recurring GPS jamming and circular spoofing, creating urgent demand for signal-independent navigation. Infleqtion holds active defense contracts across the AUKUS partnership: RIQER with the U.S. Army DEVCOM, QuDiFi funded by Innovate UK, and QOBRA in Australia. The Royal Navy successfully integrated Tiqker onto the Excalibur XLUAV autonomous underwater submarine, demonstrating the world's first quantum optical clock in GPS-denied submarine operations. A strategic partnership with Safran will roll out integrated quantum timing globally beginning in early 2026, while NASA and Northrop Grumman delivered Infleqtion's quantum hardware to the International Space Station for ultracold atom experiments.
Infleqtion's economic moat rests on vertical integration and intellectual property depth. The company holds over 235 issued and pending patents, and its 2024 acquisitions of SiNoptiq and Morton Photonics secured an internal laser supply chain, mitigating the chokepoint risk that constrains competitors dependent on three or four global vendors. Turn-key quantum systems can yield margins up to 50 percent, while Superstaq's ecosystem creates long-term software stickiness through academic adoption and institutional integration. With over 160 PhD physicists, operational installations across the U.S., U.K., Japan, and Australia, and an NVIDIA collaboration for hybrid classical-quantum computing, Infleqtion is consolidating a vertically integrated position spanning sensing, computing, software, and defense, which financial markets are now correctly pricing as a foundational national security asset.
 Long

How Did a Forgotten Giant Become AI's Quiet Architect?Nokia's 2026 resurgence is the climax of a brutal multi-year metamorphosis. The company nearly collapsed in 2019, when its networks' gross margins crashed to 29% amid a botched reliance on Intel's delayed 10nm silicon and expensive, power-hungry Xilinx FPGAs. It has since reemerged as the indispensable infrastructure layer of the AI era. CEO Pekka Lundmark engineered the turnaround by hiring 350 specialized chip engineers in Finland, launching the ReefShark System-on-a-Chip family, and diversifying silicon supply across Broadcom (RF), Marvell (Layer 1 baseband), and Intel (Layers 2-3). By late 2021, 70% of shipments carried purpose-built SoCs, restoring pricing power and ending the FPGA-driven margin crisis.
The financial validation arrived in Q1 2026: $5.26 billion in sales, a 49% surge in AI and cloud net sales, €1 billion in accumulated AI customer orders, and a 20% jump in optical networks revenue. The stock has climbed roughly 116% year-to-date and 169% over the trailing 52 weeks, with Bank of America and Argus both moving to Buy. The reinvention pivots on the NVIDIA AI-RAN partnership, validated by T-Mobile's over-the-air Seattle trial that ran AirScale Massive MIMO, video streaming, and generative AI queries on a single Grace Hopper 200 server. SoftBank's AITRAS Orchestrator points to the new monetization model: turning idle base-station GPU cycles into a sellable AI compute layer.
Geopolitics has become Nokia's strongest tailwind. A $4 billion commitment from the Trump administration, layered on $2.3 billion of private US manufacturing investment and the $2.3 billion Infinera acquisition, locks in federal contracts and Data Center Interconnect demand from hyperscalers. Selling Alcatel Submarine Networks to the French state for €350 million resolved European sovereignty concerns while sharpening Nokia's terrestrial focus. On the defense side, Nokia Federal Solutions and Lockheed Martin's 5G.MIL ecosystem, built on CMOSS open standards and the Hybrid Base Station, embeds Nokia inside JADC2 operations and the broader US military-industrial complex.
Underneath the operating businesses sits a patent fortress generating annuity revenue at scale. Nokia controls roughly 26,000 global patent families and 8,190 5G Standard Essential Patents, monetized under FRAND terms. The 2023–2024 "Lucky Seven" smartphone renewal cycle with Apple, Samsung, Huawei, Xiaomi, OPPO, Vivo, and Honor locked in over €800 million in annual recurring revenue through 2030, while UPC litigation against Geely demonstrates Nokia's willingness to weaponize Europe's centralized patent court. Combined with quantum-safe optical transport at KDDI's Sakai Data Center, a 6G video codec jointly submitted with Ericsson and Fraunhofer, and FRMCS leadership in the railway transition, Nokia has repositioned itself as the architect of global digital sovereignty for the next decade.
 Long

Is America's Quiet Foundry the West's Last Defense?GlobalFoundries has undergone a dramatic transformation in 2026, evolving from a slow-growth contract manufacturer into a strategically vital American semiconductor asset. Shares nearly doubled in the first four months of the year, fueled by a strong Q1 earnings beat, with revenue of $1.634 billion and EPS of $0.40, surpassing consensus by 18%. Its Communications Infrastructure and Data Center segment surged 32%, driven by relentless AI infrastructure spending, while automotive revenue climbed 24%. Management guided Q2 revenue to $1.76 billion, signaling that the momentum is far from accidental.
At the core of GF's re-rating is a powerful geopolitical tailwind. As the only US-headquartered pure-play foundry with global scale, it is the primary beneficiary of the CHIPS Act, having secured up to $1.575 billion in federal funding and $550 million from New York State, backing a $13 billion US investment program. Its Malta fab carries DoD Trusted Foundry credentials, and Apple has reportedly booked production there. A deepened partnership with Renesas and expanding defense and aerospace contracts are quietly weaving GF into the backbone of allied semiconductor supply chains, reducing Western exposure to Taiwanese capacity at a historically fraught geopolitical moment.
Technologically, GF is staking its future on next-generation platforms. Its newly launched SCALE co-packaged optics solution, the industry's first OCI MSA-capable platform, directly addresses the bandwidth and power bottlenecks throttling AI clusters, positioning GF as the leading non-Asian foundry for the optical-interconnect transition. Meanwhile, its GaN partnership with Navitas targets AI data center power delivery, and its AutoPro150 eMRAM platform is gaining traction in software-defined vehicles. Even quantum computing is on the roadmap, with GF manufacturing photonic chips for PsiQuantum's million-qubit ambitions.
The most aggressive move of 2026, however, is legal: GF launched patent infringement suits against Tower Semiconductor, filing in federal court and at the ITC, leveraging a portfolio of over 8,000 patents against Tower's fewer than 500. This offensive reflects a broader strategic pivot converting from a contract fab into a vertically integrated technology platform protected by deep IP moats in RF SOI, FDX, silicon photonics, and embedded memory. Risks remain, including a stretched valuation near 30x forward earnings, mobile market softness, and binary litigation outcomes. But GFS is now a company that policymakers, hyperscalers, and defense planners simply cannot afford to overlook.  Long

When Does a Drone Become a Decision-Maker?AeroVironment (AV) has undergone a profound transformation from a niche drone manufacturer into a vertically integrated, multi-domain defense technology company. The global defense landscape is shifting decisively away from expensive manned platforms toward low-cost, attritable autonomous systems, a change driven home by real-world conflicts in Ukraine and the Middle East. At the center of this shift, AV's flagship Mayhem 10 system represents the next generation of what the company calls "Launched Effects": a Group 2 UAS with modular, open-systems architecture capable of precision strike, electronic warfare, and intelligence gathering at ranges exceeding 100 kilometers. Built on a Modular Open Systems Architecture (MOSA) developed with Parry Labs, the platform supports rapid payload swaps from kinetic warheads to jamming kits and is designed to operate in GPS-denied, electronically contested environments, making it a genuinely flexible battlefield asset rather than a single-purpose munition.
AV's acquisition of BlueHalo has expanded its portfolio into directed energy, with the LOCUST X3 laser system emerging as the most combat-proven high-energy laser in the U.S. inventory. Capable of engaging drone threats for under $5 per shot at ranges of three to five kilometers, the LOCUST X3 offers a cost-asymmetric counter to the mass drone attacks increasingly seen on modern battlefields. Following FAA clearance for domestic use enabled by an automated aircraft-detection safety shutoff, the system is now being deployed along the southern U.S. border, marking a significant expansion into homeland defense. Simultaneously, AV's $97.4 million GENESIS contract with the U.S. Army advances next-generation missile defense sensor testing through Hardware-in-the-Loop environments at Redstone Arsenal, while its UES division pursues $100 million in Air Force contracts spanning biotechnology, smart materials, and human performance technologies, underscoring a diversification strategy that extends well beyond conventional drone manufacturing.
The company's software strategy is anchored by the AV_Halo platform, a hardware-agnostic command, control, and targeting ecosystem that now includes CORTEX, an AI-driven intelligence fusion tool capable of detecting emerging drone threat patterns in minutes, and MENTOR, an immersive training environment for mission rehearsal. AV's intellectual property portfolio further fortifies its competitive position: its drone-related patents are routinely cited by the U.S. Patent Office to reject competitor applications, and several have been pledged as collateral for capital financing, illustrating their tangible financial value. On the manufacturing side, a $30 million campus expansion in Albuquerque backed by $6 million in state and city incentives is adding over 450 high-wage jobs and targeting vertically integrated production of directed energy and space-grade systems, with a projected $670 million regional economic impact over a decade.
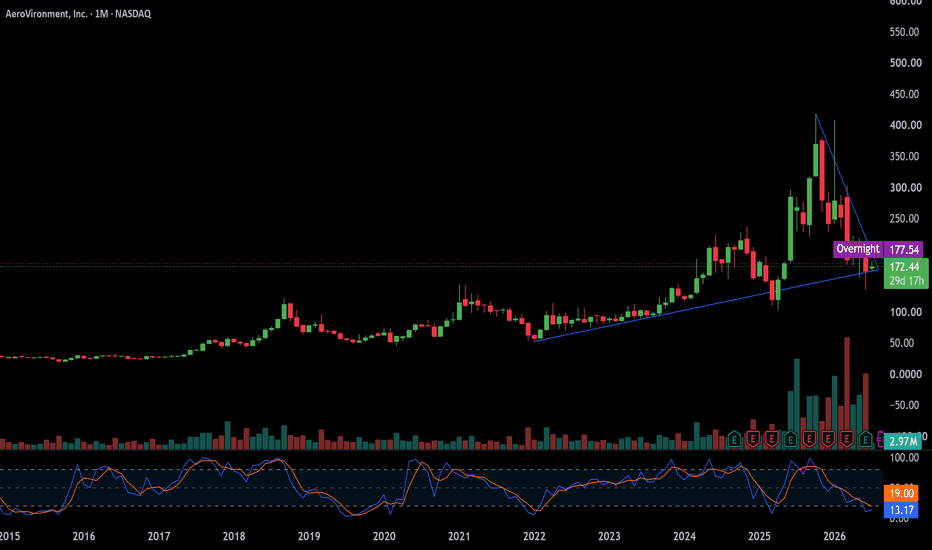
AV's financial trajectory reflects surging institutional demand: trailing twelve-month revenue grew 117%, anchored by a $186 million Switchblade delivery order, the $152 billion One Big Beautiful Bill Act (OBBBA) earmarking $1 billion for one-way attack drones, and U.S. Army FY2026 budget requests of nearly $70 million for loitering munitions. Analyst sentiment remains constructive, with a consensus "Moderate Buy" rating and price targets ranging from $235 to $450, though near-term volatility reflects valuation tension after a rapid run-up. Structurally, AeroVironment appears to occupy a rare position in the defense ecosystem: a company that is simultaneously defining the technology standards of autonomous warfare through patents, producing fielded systems at scale, and expanding into adjacent scientific domains, making it less a drone company than an architecture for the future of conflict itself. Long 
 Long

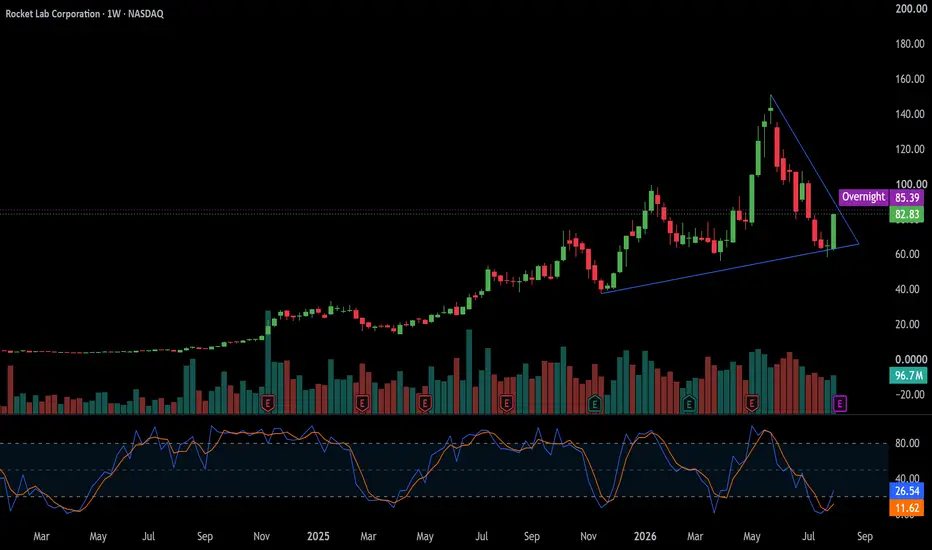
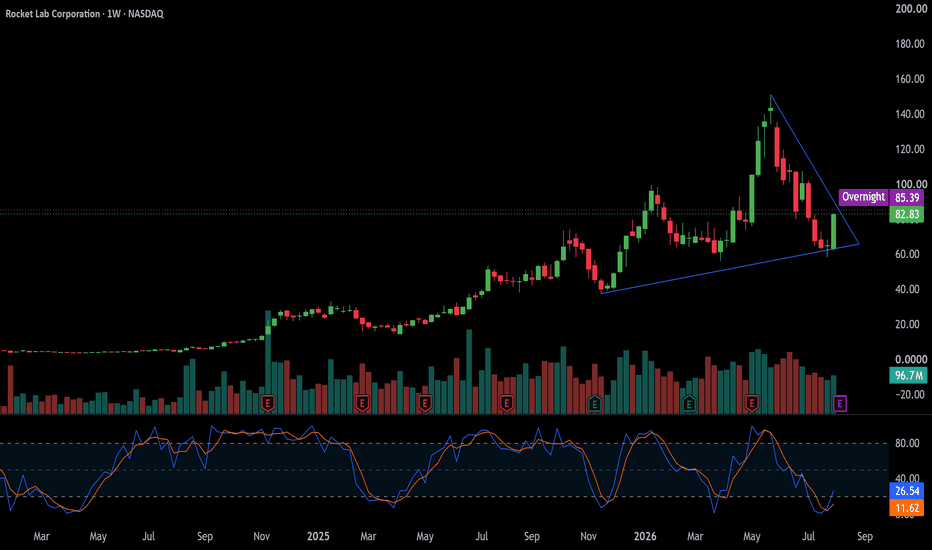
Rocket Lab: The Strategic Ascent of a Space PowerhouseRocket Lab (RKLB) has transitioned from a niche launcher to a global aerospace titan. The company currently commands significant investor attention as the "Year of Space Stocks" begins. Its stock price recently surged by 10% following renewed SpaceX IPO buzz and massive defense contract wins. This article analyzes the multi-dimensional forces driving Rocket Lab’s current market dominance.
Geostrategy and the New Defense Frontier
Space now serves as the ultimate geopolitical high ground. Rocket Lab leverages this reality by securing critical contracts with the Space Development Agency (SDA). These agreements position the company as a key player in national security.
The recent launch for the European Space Agency (ESA) further solidifies its geostrategy. By deploying navigation constellions, Rocket Lab strengthens Western orbital infrastructure. Investors recognize that government-backed contracts provide a stable revenue floor.
The End-to-End Business Model Pivot
Rocket Lab is no longer just a launch company. Its "Space Systems" division now generates the majority of its revenue. The potential role as a bus provider for the 2,800-satellite Equatys constellation proves this shift.
This vertical integration creates a massive competitive moat. Rocket Lab builds the satellites, provides the components, and launches the final product. This model reduces third-party reliance and maximizes profit margins.
Macroeconomic Catalysts and the SpaceX Halo
Macroeconomic sentiment toward space stocks has shifted from speculative to operational. Analyst upgrades reflect a growing confidence in Rocket Lab's execution. The rumored SpaceX IPO creates a "halo effect" for the entire sector.
Investors seek liquid, public alternatives to SpaceX's private dominance. Rocket Lab stands as the most viable contender for this capital. High interest rates previously dampened capital-intensive sectors, but Rocket Lab’s lean operations mitigated these risks.
Leadership, Culture, and Execution
Founder Peter Beck maintains a culture of aggressive innovation and transparency. His leadership emphasizes "doing" over "talking," a rare trait in the space industry. This execution-focused culture attracts top-tier engineering talent and institutional investors.
Management successfully avoided the "SPAC trap" that claimed many competitors. They focused on flight heritage and reliable hardware. Consequently, Rocket Lab enjoys a reputation for consistency that rivals larger, legacy aerospace firms.
Technological Moats and Patent Innovation
Rocket Lab’s high-tech advantage stems from its proprietary carbon-fiber and 3D-printing processes. These innovations allow for rapid manufacturing and lower launch weights. The development of the Neutron rocket targets the lucrative medium-lift market.
Patent analysis reveals a deep portfolio in Rutherford engine technology and satellite bus architectures. These patents prevent competitors from easily replicating Rocket Lab’s cost structure. Science and engineering remain the primary drivers of their long-term valuation.
Cybersecurity in the Orbital Domain
As satellite constellations grow, cybersecurity becomes a critical business requirement. Rocket Lab integrates robust digital defenses into its satellite buses. Protecting sensitive data for defense and commercial clients is a strategic priority.
Leadership views cybersecurity as a core component of their value proposition. A single breach could jeopardize multi-billion-dollar constellations like Equatys. Robust digital infrastructure ensures Rocket Lab remains a trusted partner for global agencies.
The 2026 Outlook
Rocket Lab represents the convergence of high-tech innovation and strategic necessity. Its diverse revenue streams and proven flight record offer a unique investment profile. The company is successfully scaling to meet the demands of a $1 trillion space economy. Rocket Lab is no longer an underdog; it is a market leader. Long 
 Long
 Long

Red Cat (RCAT): The New Architecture of Autonomous DefenseThe aerospace and defense sector is witnessing a seismic shift. Red Cat Holdings (RCAT) now stands at the center of this transformation. As of March 2026, the company’s stock has surged following unprecedented geopolitical escalation. Investors are no longer just buying a drone company. They are investing in a comprehensive, all-domain autonomous ecosystem.
Geopolitical Triggers: The Iran-Israel Conflict
The recent joint U.S.-Israel strikes on Iran have reshaped market expectations. War in the Middle East has validated the necessity of low-cost, expendable drone technology. U.S. forces reportedly spent $779 million in the first 24 hours of the offensive. This conflict emphasizes the "Drone Dominance" narrative that Red Cat leads. Demand for the Black Widow and FANG platforms is accelerating.
Macroeconomics and the 2026 Defense Budget
The 2026 U.S. defense budget includes over $20 billion for munitions and unmanned systems. Section 1709 of the FY25 NDAA further fuels Red Cat’s growth. This provision bans foreign-made drones from the U.S. market. It effectively eliminates Chinese competition for domestic contracts. Red Cat now enjoys a dominant negotiating position in a protected market.
The Allen Control Systems (ACS) Strategic Alliance
Innovation is the primary driver of Red Cat’s current valuation. On March 2, 2026, the company announced that Allen Control Systems joined the Red Cat Futures Initiative. They will integrate the "Bullfrog" autonomous counter-drone system into Red Cat’s maritime division, Blue Ops. This partnership creates a multi-domain defense shield. It allows uncrewed surface vessels (USVs) to neutralize aerial threats autonomously.
Technological Sovereignty and Patent Analysis
Red Cat is aggressively securing its intellectual property. Recent patent analysis shows a pivot toward "technological sovereignty." The company is filing patents for resilient command-and-control (C2) architectures. These systems prioritize cybersecurity in contested electronic warfare environments. Their focus on open-architecture interoperability ensures they remain the preferred partner for the Department of Defense.
Management and Corporate Culture of Agility
Leadership at Red Cat has successfully pivoted from consumer data to high-stakes defense. Management, led by VP of Tech & Innovation Jason Gunter, emphasizes a "Family of Systems" approach. This culture of rapid iteration allowed the company to scale revenue by 1,800% in a single year. They have transitioned from concept development to mass-scale production.
Industry Trends and Business Model Evolution
The industry is moving toward "uncrewed" everything. Red Cat’s business model now includes recurring revenue from software and maintenance. Their Blue Ops facility in Georgia signals a move into large-scale manufacturing. By providing "American-made" hardware, they satisfy both political and tactical requirements. This vertical integration protects margins while meeting urgent military needs.
The Financial Outlook for RCAT
Wall Street remains bullish on Red Cat’s trajectory. Needham & Company recently reaffirmed a "Buy" rating with a target reaching toward $19.50. While the company still faces operational losses, its $200 million liquidity provides a significant runway. Investors are betting on the long-term dominance of autonomous warfare. Red Cat is no longer a speculative play; it is a defense staple.  Long

Can America Break China's Rare Earth Monopoly?USA Rare Earth (Nasdaq: USAR) stands at the center of America's most ambitious industrial gamble in decades. The company pursues a vertically integrated "mine-to-magnet" strategy designed to break China's stranglehold on rare earth elements, critical materials that power everything from electric vehicles to F-35 fighter jets. With China controlling 70% of global mining and over 90% of refining capacity, the United States faces a strategic vulnerability that threatens both its defense capabilities and its energy transition. Recent Chinese export restrictions on gallium and germanium have accelerated USA Rare Earth's timeline, with commercial production now targeted for late 2028, two years ahead of previous guidance.
The company's success hinges on extraordinary government backing and massive capital infusions. A $1.6 billion letter of intent from the Department of Commerce, combined with a $1.5 billion private investment, provides $3.1 billion in potential funding. The government will take a 10% equity stake, signaling an unprecedented public-private partnership in critical infrastructure. This funding supports the entire value chain: extraction at the Round Top deposit in Texas, chemical separation in Colorado, and advanced magnet manufacturing in Oklahoma. The Round Top deposit itself is geologically unique, a 1-billion-metric-ton laccolith containing 15 of 17 rare earth elements, processable through cost-effective heap leaching rather than traditional roasting.
Beyond minerals, the project represents a test of American industrial resilience. The Trump administration's "Project Vault" initiative establishes a $12 billion strategic mineral reserve modeled after the Strategic Petroleum Reserve. International alliances with Australia, Japan, and the United Kingdom create a network of "friend-shored" supply chains designed to counter Beijing's leverage. USA Rare Earth's acquisition of UK-based Less Common Metals provides critical refining expertise currently unavailable outside China. The company achieved a milestone in January 2026 by producing its first batch of sintered neodymium magnets at its Oklahoma facility, proving its technical capabilities.
The path forward remains treacherous. Critics point to timeline delays, insider selling, and the volatility inherent in pre-revenue mining ventures. Short sellers have claimed a potential 75% downside, questioning equipment age and promotional tactics. Yet the strategic imperative is undeniable: without domestic rare earth capacity, the United States cannot maintain technological superiority in defense or achieve energy independence. USA Rare Earth's 2030 goal of processing 8,000 tons of heavy rare earths and producing 10,000 tons of magnets annually would fundamentally reshape global supply chains. The billion-dollar race for magnet supremacy will determine whether America can reclaim industrial sovereignty or remain dependent on geopolitical rivals for the minerals of the future.  Long

Is Salesforce Now a Defense Contractor?Salesforce has reached a defining inflection point that fundamentally transforms its corporate identity. The company, historically known as a commercial software provider, has secured a massive $5.64 billion contract with the U.S. Army extending through 2035. For the first time, the tech giant is positioning itself as a "defense prime contractor" and embracing the Trump administration's provocative rebranding of the Department of Defense as the "Department of War." This move not only stabilizes the company's revenue stream with a long-term, firm-fixed-price agreement but also places it at the center of U.S.-China geopolitical competition and brings it closer to the traditional defense industrial base.
The market has responded with enthusiasm - analysts have raised price targets above $320 per share, and investors view the contract as a bond-like guarantee of stable cash flow. The company's stock surged to the $257 range in early 2026, reflecting Wall Street's revaluation of Salesforce as critical national infrastructure rather than as a volatile SaaS business. However, the pivot carries significant risks. It jeopardizes Salesforce's operations in China, where it has operated for years through local partnerships, and raises serious questions about data sovereignty in Europe, particularly given the U.S. CLOUD Act. With 20% of revenues coming from Europe, Salesforce is entering direct conflict with the digital sovereignty demands of leaders like Macron and Scholz.
The technological dimension is equally compelling: Salesforce is aggressively investing in Agentforce, its autonomous AI agent platform, competing directly with Palantir for dominance in the government software market. The technology promises radical automation of military logistics and personnel management, leveraging Salesforce's enormous advantage in commercial customer data across millions of users. CEO Marc Benioff has emphasized their pricing advantage, undercutting competitors by amortizing R&D costs across their massive commercial base. Yet questions remain: can this pivot deliver long-term returns, or will the company find itself caught in trade wars, sanctions, and regulatory restrictions that undermine future profitability? The transformation from SaaS giant to defense contractor represents either a brilliant strategic repositioning or a dangerous entanglement with geopolitical risk.  Long