Long

 Short
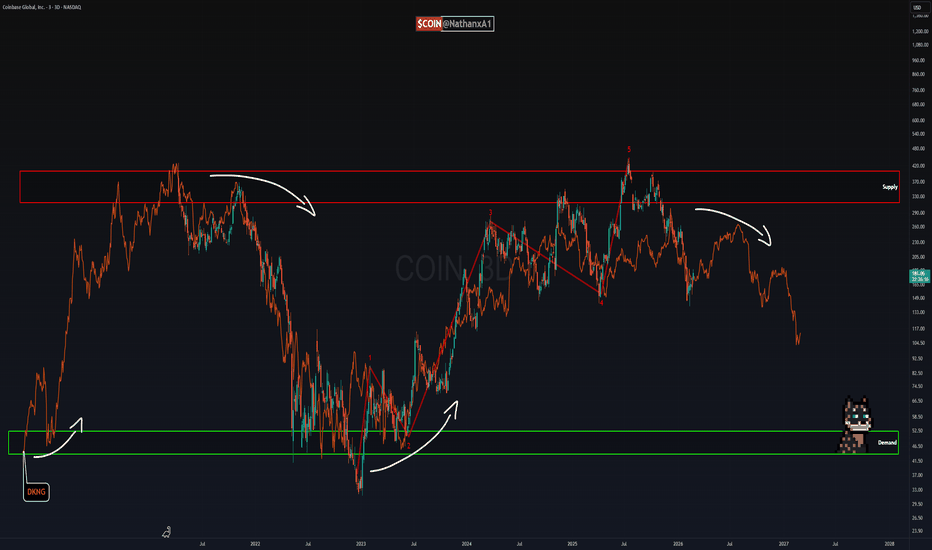
DraftKings Stumbles: Earnings MissDraftKings Stumbles: Earnings Miss, Tepid Guidance, and Cathie Wood Exits as Prediction Markets Beckon
DraftKings Inc. delivered a disappointing conclusion to its 2025 fiscal year, sending shares into a tailspin on Friday as investors digested a fourth-quarter earnings miss and a 2026 revenue outlook that fell substantially short of consensus expectations. The selloff was not confined to DraftKings alone; the negative sentiment bled over to Flutter Entertainment, parent company of rival FanDuel, underscoring the interconnected nature of investor sentiment in the online sports betting sector.
Adding a layer of narrative intrigue, Cathie Wood's ARK Invest, a high-profile thematic investment manager, was observed unloading additional DraftKings shares on Thursday, just ahead of the earnings release. The proceeds were redeployed into crypto-related equities, signaling a potential shift in ARK's conviction regarding the relative near-term prospects of sports betting versus digital asset exposure.
1. Q4 Performance: A Mixed Bag Masked by a Headline Miss
DraftKings reported fourth-quarter adjusted earnings per share of 36 cents , a substantial improvement from the 14 cents reported in the prior-year period but still short of the 39-cent consensus forecast. Revenue increased 43% year-over-year to $1.989 billion , narrowly missing the $1.99 billion analyst target.
The headline miss, while modest in absolute terms, triggered an outsized market reaction, reflecting the high expectations embedded in DraftKings' valuation and the market's sensitivity to any indication of decelerating momentum.
Beneath the surface, the quarterly results revealed a more nuanced picture. Monthly unique players (MUPs) , a critical metric for assessing user base expansion, remained flat at 4.8 million compared to the prior year. This static performance contrasted sharply with FactSet expectations of 5.26 million, suggesting that customer acquisition costs may be rising or that market saturation is approaching in certain jurisdictions.
However, the company demonstrated impressive monetization of its existing user base. Average revenue per monthly unique player (ARPUP) surged 43% to $139 , comfortably exceeding the $124 consensus. This divergence—flat users but surging revenue per user—indicates that DraftKings is successfully extracting greater value from its existing customers through cross-selling, higher-margin products, and improved engagement. For a mature growth company, this dynamic is not inherently negative, but it does shift the narrative from "land grab" to "monetization," a transition that often introduces multiple compression.
2. The 2026 Outlook: Investment Mode Weighs on Guidance
DraftKings' 2026 revenue guidance proved to be the primary catalyst for the post-earnings selloff. Management projected full-year revenue in the range of $6.5 billion to $6.9 billion , a forecast that incorporates significant investment in the company's newly emphasized Predictions business. The midpoint of this range implies year-over-year growth of approximately 15%, a deceleration from the 43% growth achieved in Q4 2025.
Analysts, by contrast, had been modeling a more robust trajectory, with consensus expectations calling for 2026 revenue of $7.2 billion , representing approximately 19% growth. The approximately $300 million gap between the guidance midpoint and the consensus forecast suggests that either management is being deliberately conservative or that internal projections have identified headwinds not yet reflected in sell-side models.
CEO Jason Robins, in the earnings release, sought to frame the investment thesis constructively. "We also see a massive, incremental opportunity in DraftKings Predictions," Robins stated. "We plan to deploy growth capital to build the best customer experience in Predictions, and acquire millions of customers." This language signals that DraftKings views the 2026 guidance not as a reflection of diminished long-term potential, but as a temporary period of elevated investment designed to capture a new addressable market.
3. Prediction Markets: The Next Frontier
The reference to "DraftKings Predictions" represents a strategic pivot that warrants close attention. Prediction markets—platforms allowing users to wager on the outcomes of political events, financial metrics, cultural phenomena, and other non-sporting occurrences—have emerged as a high-growth adjacency to traditional sports betting.
Earlier in February, DraftKings announced a partnership with Crypto.com to expand its prediction markets offerings. This collaboration marries DraftKings' user acquisition expertise and regulatory relationships with Crypto.com's blockchain infrastructure and cryptocurrency payment rails. The timing is opportune, as prediction markets gained mainstream visibility during the 2024 and 2025 U.S. election cycles, with platforms like Kalshi and Polymarket attracting significant user volume and media attention.
For DraftKings, prediction markets offer several strategic advantages. They expand the total addressable market beyond sports fans to include news followers, political enthusiasts, and financial speculators. They operate with different margin profiles and regulatory frameworks than traditional sports betting. And they provide a natural entry point for cryptocurrency integration, potentially attracting a younger, digitally native demographic.
However, the investment required to build a competitive prediction markets platform—including technology development, regulatory navigation, and customer acquisition—will weigh on near-term margins. The 2026 guidance embeds this reality, and investors must now assess whether the long-term opportunity justifies the short-term earnings drag.
4. Cathie Wood's Exit: Tactical or Thematic?
The timing of ARK Invest's DraftKings sales added an additional layer of complexity to the post-earnings narrative. On Thursday, ahead of the earnings release, ARK funds were observed unloading additional DraftKings shares while simultaneously accumulating crypto-related equities.
Cathie Wood's investment style is characterized by high-conviction thematic bets and active portfolio management. Her decision to reduce DraftKings exposure—even before the disappointing earnings and guidance—suggests either a tactical de-risking ahead of a known catalyst or a more fundamental reassessment of the sports betting investment thesis.
The concurrent accumulation of crypto stocks is instructive. ARK has long been a prominent advocate for digital assets, viewing blockchain technology as a transformative force across multiple sectors. The rotation from DraftKings into crypto names may reflect a view that the risk-reward profile of digital asset exposure has become more attractive than sports betting at current valuations, or that the prediction markets opportunity—while strategically sound—will take longer to materialize than previously anticipated.
For DraftKings shareholders, ARK's exit is not necessarily a directional signal. Wood's funds represent a single investor with a specific mandate and time horizon. However, given ARK's influence among retail and thematic investors, the sales may exert psychological pressure on sentiment until new institutional buyers emerge to absorb the supply.
5. Analyst Reaction and Valuation Context
Following the earnings release and guidance, analysts are likely to revise their 2026 estimates downward to align with management's more conservative framework. The extent of multiple compression will depend on whether the investment thesis shifts from "accelerating growth" to "transitional investment phase."
DraftKings' valuation has historically commanded a premium due to its position in the dual-growth markets of online sports betting and iGaming. That premium is now under pressure as growth rates moderate and investment intensity persists. The company's ability to articulate a clear path to operating leverage and free cash flow generation will be critical in determining whether the current selloff represents a buying opportunity or a structural re-rating.
6. Broader Sector Implications
Flutter Entertainment's correlated decline underscores the sector's sensitivity to DraftKings-specific news. As the parent company of FanDuel, Flutter is exposed to many of the same dynamics—market maturation, regulatory uncertainty, and the need for continued investment to maintain competitive positioning. While Flutter's geographic diversification provides some insulation from U.S.-specific trends, the DraftKings guidance raises questions about the entire U.S. online sports betting market's near-term growth trajectory.
Investors in the sector will now scrutinize Flutter's upcoming earnings for confirmation or contradiction of the trends signaled by DraftKings. If Flutter reports sustained momentum and offers more constructive guidance, DraftKings' miss may be viewed as company-specific. If Flutter echoes the cautious tone, the selloff could broaden.
Conclusion: A Pause in the Narrative, Not an Ending
DraftKings' post-earnings selloff reflects genuine near-term concerns: user growth stagnation, guidance below consensus, and elevated investment spending. The company's strategic pivot toward prediction markets, while promising, introduces execution risk and delays the path to margin expansion.
However, the fundamental thesis—that online sports betting and digital wagering represent multi-decade secular growth opportunities—remains intact. DraftKings' brand strength, regulatory relationships, and technology platform provide durable competitive advantages. The partnership with Crypto.com positions the company at the intersection of two powerful trends: the normalization of sports betting and the mainstreaming of cryptocurrency.
For long-term investors, the question is whether the current pullback represents a temporary dislocation or the beginning of a sustained de-rating. The answer will depend on DraftKings' ability to execute its prediction markets strategy, stabilize user growth, and eventually translate revenue into sustainable free cash flow. The 2026 guidance suggests a year of investment and transition. Whether the market has the patience to wait for the payoff remains to be seen. Long 
Long 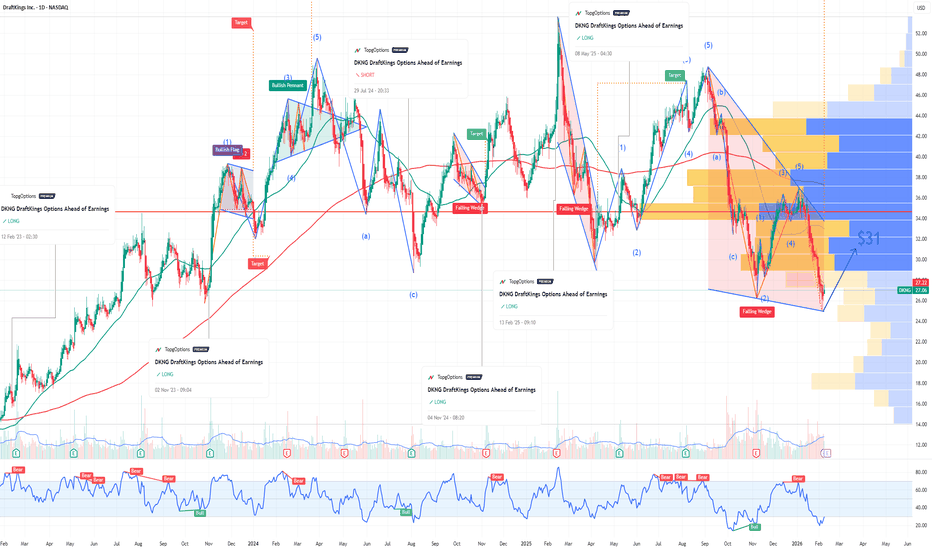
DraftKings Super Bowl ReboundThe Super Bowl is typically the largest customer acquisition event of the year for sportsbooks, and DraftKings is currently positioning itself to capture massive volume for Super Bowl LX
Customer Acquisition Spike: DraftKings is currently running aggressive "Bet $5, Get $300" promos to lock in new users ahead of the playoffs. This surge in downloads and active users often translates into bullish sentiment in the weeks leading up to the big game.
Handle Growth: Management recently reported that sportsbook wagering was up 17% year-over-year as of late 2025, providing a strong baseline of momentum heading into the peak betting season of Q1 2026.
Revenue Projection: For the current quarter, analysts are projecting massive revenue of $1.94 billion, a 38.95% increase from the previous year, driven largely by the heavy NFL postseason and Super Bowl slate.
2. The New 2026 Catalyst: "DraftKings Predictions"
A unique factor for this year's "Super Bowl madness" is the launch of DraftKings Predictions.
This new platform allows DraftKings to enter states that do not yet have legal online sports betting, significantly expanding their addressable market for the Super Bowl.
Analysts expect this "event contract" model to have higher margins and lower promotional costs than traditional betting, which could be the "X-factor" that drives a breakout.
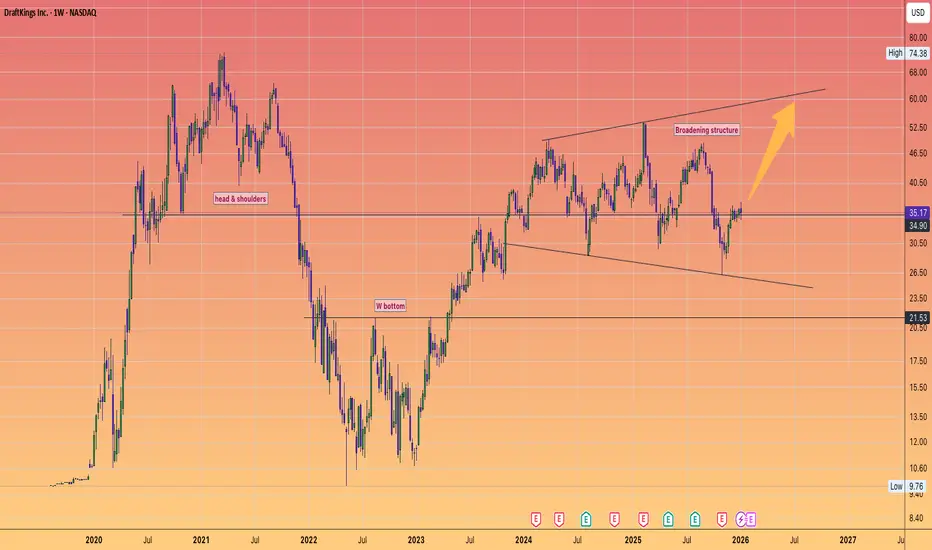
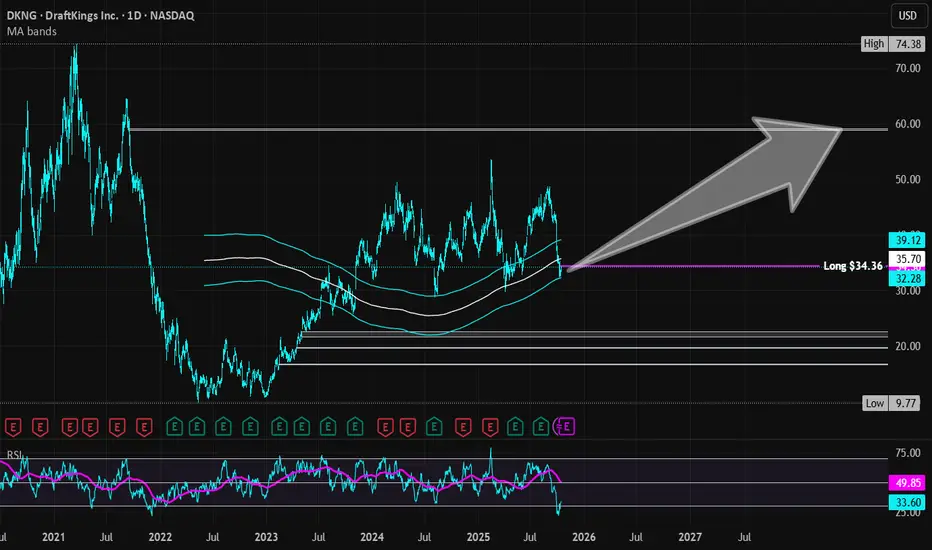
3. Technical Analysis ($35.17 as of Jan 9)
Your TradingView chart likely shows NASDAQ:DKNG testing a key structural pivot:
Resistance: The stock is currently fighting the $36.00 level. A high-volume break above this would be a "Strong Buy" signal, potentially targeting the $50.00 range seen in early 2025.
Broadening Structure: As of January 9, 2026, the stock is trading in a horizontal trend channel. The "Super Bowl run" usually provides the volume needed to break out of such a range. Long 
Short

Long 
Long 
Long 
Short 
Long 
 Long

Long 
Long 
Long 
Short 
Long 
Long 
Draftkings Earnings Preview and Analysis DraftKings ( NASDAQ:DKNG ), a daily fantasy sports contest and sports betting company, reported a 53% year-over-year revenue growth in Q1 2024. The company's performance was attributed to healthy revenue growth and a scaled fixed cost structure, which allowed for the rapid improvement of Adjusted EBITDA. The company successfully launched its online sportsbook in Vermont and North Carolina with efficient customer acquisition, and its platform and overall customer experience are improving, leading to excellent customer retention and participation across sports and games.
DraftKings increased its fiscal year 2024 revenue guidance to $4.9 billion from $4.775 billion and the midpoint of its Adjusted EBITDA guidance to $500 million from $460. The company's structural sportsbook hold percentage also exceeded expectations, reaching 9.8%, a significant increase from the previous year. However, DraftKings reported a loss of 30 cents per share, an improvement from 87 cents per share the previous year.
Executives stressed the company's "unbelievably efficient" first quarter and noted a 40% year-over-year decrease in customer acquisition costs (CAC) in April. CEO Jason D. Robins highlighted the company's focus on proprietary technology solutions, including significant advancements in sportsbook offerings and the expansion of its iGaming portfolio with new, unique titles.
Robins also highlighted the use of artificial intelligence (AI) to improve product efficiency and customer experience. AI initiatives include modeling and detecting signs of problem gaming, allowing the player intervention team to properly flag issues for investigation. However, there was little mention of payments and payouts during the call, as less than half of gamers now have access to instant payouts.
In summary, DraftKings' Q1 2024 revenue growth was driven by efficient customer acquisition, product innovation, and a focus on customer-centricity. The company's stock price remains relatively unchanged, but it has seen a significant increase in monthly unique players and a focus on responsible gaming initiatives.
Technical Analysis
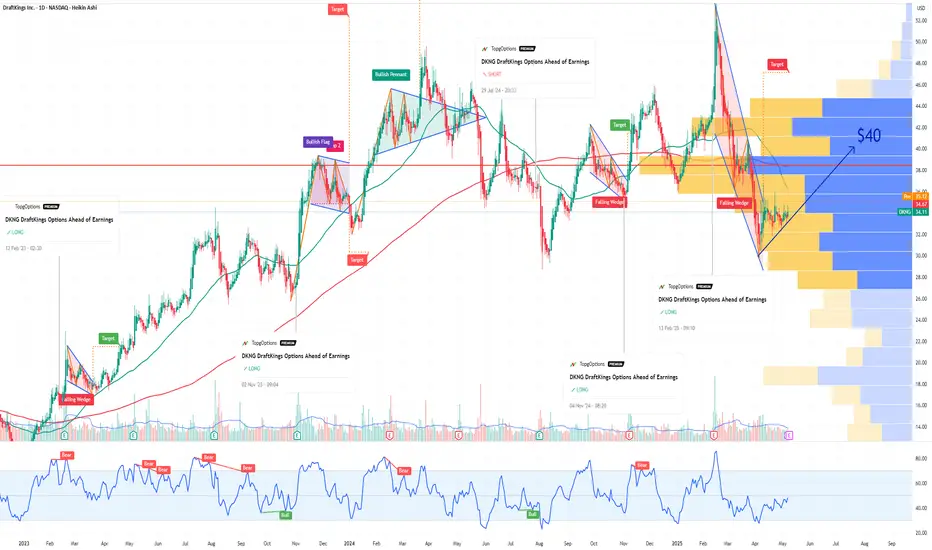
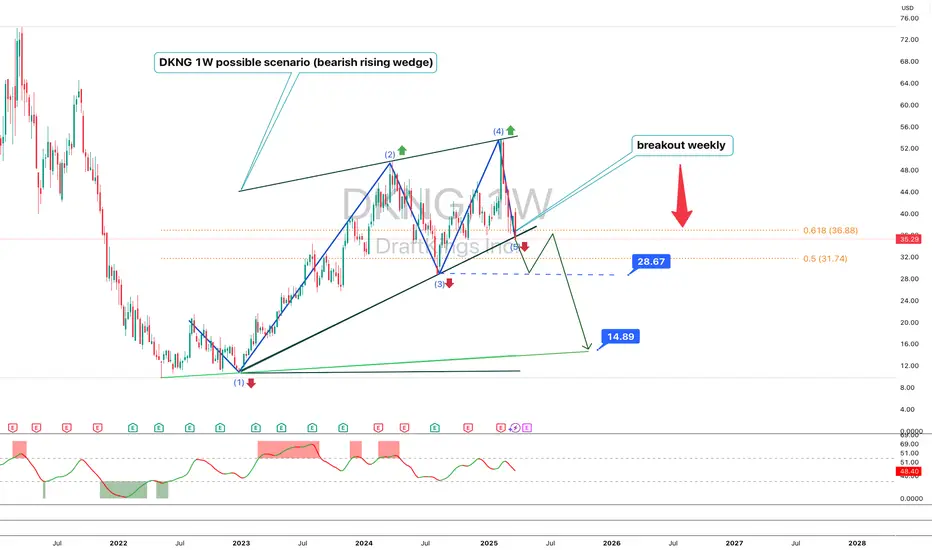
Despite a positive earnings beat, using Elliott Wave Theory, DraftKings stock ( NASDAQ:DKNG ) appears to have completed its fifth bullish wave within a bullish divergence pattern. This suggests a potential shift in momentum, with indications of a forthcoming bearish divergence. It's essential to monitor closely for confirmation of this divergence and its implications for future price movement.
However, the technical indicators remain constant without any clear-cut. The stock has a Relative Strength Index (RSI) of 50.83. Short 
Long 
Long 
DraftKings (DKNG) Stock Shows Resilience Despite Mixed Q4 ResultDraftKings ( NASDAQ:DKNG ), the Boston-based sports betting and iGaming company, is making waves in the market once again, showing remarkable resilience in the face of mixed fourth-quarter results and a groundbreaking $750 million acquisition of Jackpocket, a leading lottery app in the U.S.
Despite the initial market reaction, which saw NASDAQ:DKNG stock fluctuate after its Q4 earnings report, analysts are bullish on the company's long-term prospects. Here's why investors should pay attention to DraftKings' strategic moves and robust growth projections:
Record Revenue and Growing User Base: Despite a slight miss on earnings estimates, DraftKings ( NASDAQ:DKNG ) reported record revenue of $1.23 billion for Q4, marking a 43% increase year-over-year. The company also saw a significant uptick in its Monthly Unique Players (MUPs), reaching an average of 3.5 million paying customers. This growth reflects DraftKings' successful expansion efforts and strong customer acquisition strategies.
Expansion into New Markets: DraftKings ( NASDAQ:DKNG ) continues to expand its footprint across the United States, offering live mobile sports betting in 24 states and iGaming products in five states. With ongoing partnerships and agreements, including the recent launch in Vermont and a forthcoming operation in North Carolina in partnership with NASCAR, DraftKings ( NASDAQ:DKNG ) is well-positioned to capitalize on the growing legal sports betting market.
Strategic Acquisition of Jackpocket: The announcement of DraftKings' acquisition of Jackpocket underscores the company's commitment to diversifying its offerings and tapping into new revenue streams. With the potential to drive significant incremental revenue in the coming years, this acquisition aligns with DraftKings' ( NASDAQ:DKNG ) growth strategy and strengthens its position in the competitive gaming industry.
Partnerships for Continued Growth: DraftKings' ( NASDAQ:DKNG ) partnership with Barstool Sports, a prominent sports and pop culture media company, further solidifies its presence in the sports betting landscape. While financial terms were not disclosed, the collaboration is expected to enhance DraftKings' marketing efforts and customer engagement, providing additional avenues for revenue generation.
Positive Price Momentum: Despite trading near the top of its 52-week range, DKNG stock continues to exhibit upward momentum, indicating investor confidence in the company's future prospects. With strong support levels and a favorable technical outlook, DraftKings ( NASDAQ:DKNG ) remains an attractive investment opportunity for those bullish on the gaming and sports betting sector.
In conclusion, DraftKings' ( NASDAQ:DKNG ) recent performance and strategic initiatives demonstrate its resilience and potential for long-term growth. As the legal sports betting market continues to evolve and expand, DraftKings ( NASDAQ:DKNG ) is well-positioned to capitalize on emerging opportunities and deliver value to its shareholders.