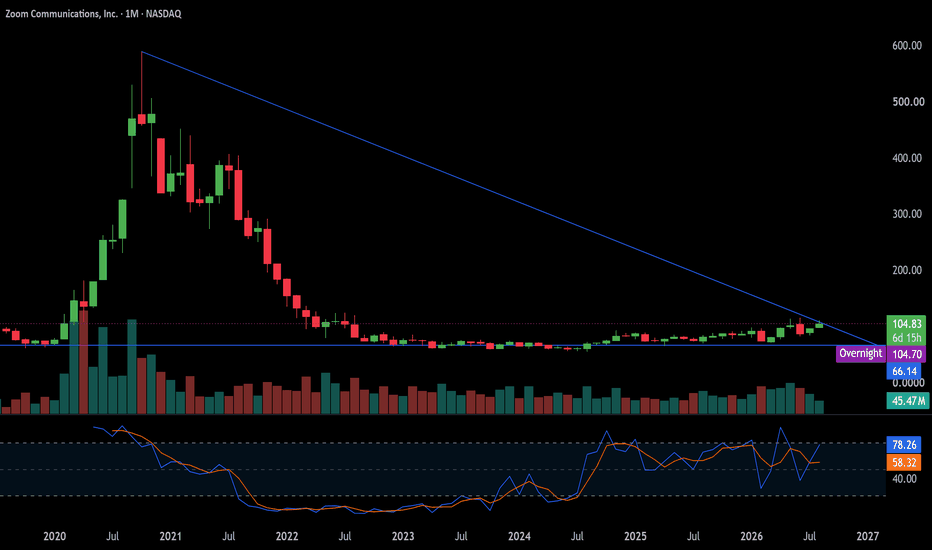
Can Zoom Become an Agentic AI Powerhouse?Q2 Earnings Anticipation and Financial Performance
Wall Street anticipates Zoom Communications second quarter earnings call with growing optimism. Analysts cite expanding artificial intelligence workflows and strong enterprise growth as key drivers. However, financial observers caution against persistent customer churn in self-serve SMB accounts.
Zoom reported first-quarter revenue of $1.24 billion, reflecting 5.5% year-over-year growth. Enterprise segment revenue expanded by 7.2% during the same operational period. Enterprise net dollar expansion reached 99%, signaling improving customer retention across major corporate clients. Broadening adoption of Zoom Phone and Contact Center continues driving mid-single-digit top-line expansion.
Technology Infrastructure and Patent Portfolio Analysis
Zoom executed a corporate rebrand to emphasize its open artificial intelligence work platform. The company holds a robust patent portfolio covering real-time analytics and intelligent media compression.
Patent US20150195406A1 describes a real-time conversational analytics facility for communication monitoring. The system processes acoustic and linguistic features to deliver instantaneous performance feedback. Patent US12288570B1 introduces behavior-based video content compression. The technology encodes facial expressions and bodily poses into timestamped sequence codes. Receiving systems reconstruct frames from reference images, drastically cutting bandwidth consumption.
Patent US12125487B2 establishes advanced speaker diarization and automated transcript creation. The platform calculates spatial audio angles using x-vectors and spatial beamforming. Patent WO2020152657A1 details speech-driven 3D facial animation using visemes and motion lookup tables. Zoom combines these capabilities within Zoom AI Companion 3.0 and ZoomMate. The AI Expert Assist 3.0 system provides live agentic guidance during contact center interactions.
US20150195406A1 (Conversational Analytics): Delivers real-time voice feature analysis and live agent feedback.
US12288570B1 (Video Compression): Implements pose and expression encoding using timestamped behavioral codes.
US12125487B2 (Automated Transcription): Executes speaker diarization using x-vectors and spatial beamforming.
WO2020152657A1 (Avatar Visualization): Generates speech-driven 3D animation utilizing visemes and motion tables.
Macroeconomic Valuation and the Anthropic Catalyst
Zoom maintains substantial financial liquidity, finishing the quarter with $7.7 billion in cash and marketable securities. The business generated $521.6 million in operating cash flow during the first quarter. Zoom Phone crossed 10 million paid seats, while Contact Center annual recurring revenue surpassed $100 million.
A major financial catalyst lies in Zoom’s strategic investment portfolio. Zoom holds an essential preferred equity stake in artificial intelligence researcher Anthropic.
Zoom reports a carrying book value of $1.27 billion for its Anthropic equity position. Following Anthropic’s Series H funding round at a $965 billion valuation, the actual stake value approaches $3 billion. Stripping out this $3 billion stake lowers Zoom’s core valuation to 11 times enterprise value to free cash flow. Consequently, investors gain access to a highly discounted enterprise communications engine backed by substantial AI assets.
Q1 Total Revenue: $1.24 billion, marking 5.5% year-over-year revenue expansion.
Operating Cash Flow: $521.6 million, generating strong cash flow supporting share buybacks.
Cash & Securities: $7.7 billion, offering a strong balance sheet that ensures liquidity.
Anthropic Stake Value: ~$3.0 billion, following significant valuation adjustments in Series H financing.
Implied Core Valuation: 11x EV/FCF, calculated by excluding the strategic Anthropic investment.
Geopolitics Infrastructure and UK Telephony Migration
Global communications providers must adapt to evolving digital sovereignty mandates and geopolitical tensions. Governments increasingly mandate localized data processing to protect national security. Zoom responded by establishing localized infrastructure, including dedicated UK data centers and isolated regional meeting zones.
The United Kingdom faces an impending telecommunications transition as copper phone lines face mandatory retirement. The legacy Public Switched Telephone Network shuts down permanently on January 31, 2027. Over 350,000 UK business sites must migrate active legacy copper voice lines before the hard deadline. Industry analysts estimate four million UK business users need modern cloud communications replacements.
Zoom partnered with voice distributor NUSO to deliver carrier-grade voice infrastructure and regulatory compliance. This collaboration provides direct peering, emergency services routing, and seamless number porting for migrating enterprises.
Leadership Dynamics and Corporate Culture Case Study
Enterprise communication platforms shape modern corporate culture and executive visibility. Remote collaboration tools offer efficiency but require empathetic leadership practices.
The platform highlighted severe leadership failures during the infamous Better.com mass firing incident. Founder Vishal Garg abruptly terminated 900 employees during a single Zoom call in December 2021. The callous execution sparked public outcry, senior executive resignations, and severe cultural damage.
Better.com accumulated over $1.5 billion in losses before its board ousted Garg in August 2026. Interim CEO Daniel Lewis assumed control while Garg initiated a proxy fight in New York court. This case illustrates how virtual communication amplifies leadership actions, demanding heightened empathy and governance standards.
Cybersecurity Vulnerabilities and the Zoomsday Protocol
Securing corporate video communication requires continuous vulnerability management across client software. Security researchers recently identified critical flaws in Zoom collaboration features, designated as Zoomsday.
The vulnerabilities involve CVE-2026-53413, CVE-2026-53414, and CVE-2026-53415 located within the meeting annotation parser. Attackers send malformed collaboration data to manipulate vulnerable client memory. Exploitation causes client crashes, sensitive memory disclosure, or arbitrary remote code execution on target devices.
Zoom classified these flaws as high severity, whereas discovering researchers rated them as critical. The rating difference reflects CVSS calculations regarding user interaction and meeting access requirements. Zoom issued security patches across Zoom Workplace, VDI clients, and Zoom Rooms to neutralize the threat.
CVE-2026-53413 (Annotation Parser): Causes memory corruption leading to application crashes.
CVE-2026-53414 (Annotation Parser): Enables information disclosure directly from client memory.
CVE-2026-53415 (Annotation Parser): Allows arbitrary remote code execution on target host devices.
Pharmaceutical Clinical Trials and Scientific Collaboration
Zoom expands beyond general business video conferencing into specialized life sciences and clinical research environments. Zoom for Healthcare provides HIPAA-compliant infrastructure tailored for pharmaceutical companies and research institutions. The platform powers AI-first connected care across modern healthcare organizations.
Biotechnology firms utilize secure virtual channels to coordinate global clinical trials across diverse geographic sites. Automated transcription and speaker diarization simplify trial documentation and compliance recording. Natural language models analyze interaction transcripts to extract structured clinical metrics and operational data.
High-tech research teams combine real-time speech synthesis and 3D viseme models for interactive scientific visualization. These tools enable global research teams to analyze complex scientific data within secure virtual environments.
Industry Trends and Strategic Outlook
Zoom’s transition toward an AI-first open work platform positions the firm for long-term enterprise relevance. Robust cash reserves and high cash flow generation provide balance sheet resilience.
While competition from Microsoft Teams and churn in SMB accounts remain concerns, product diversification continues. Zoom Phone momentum, Contact Center expansion, and the Anthropic investment present significant upside catalysts. Enterprise leaders adopting modern collaboration tools must balance platform capability with rigorous security governance.  Long
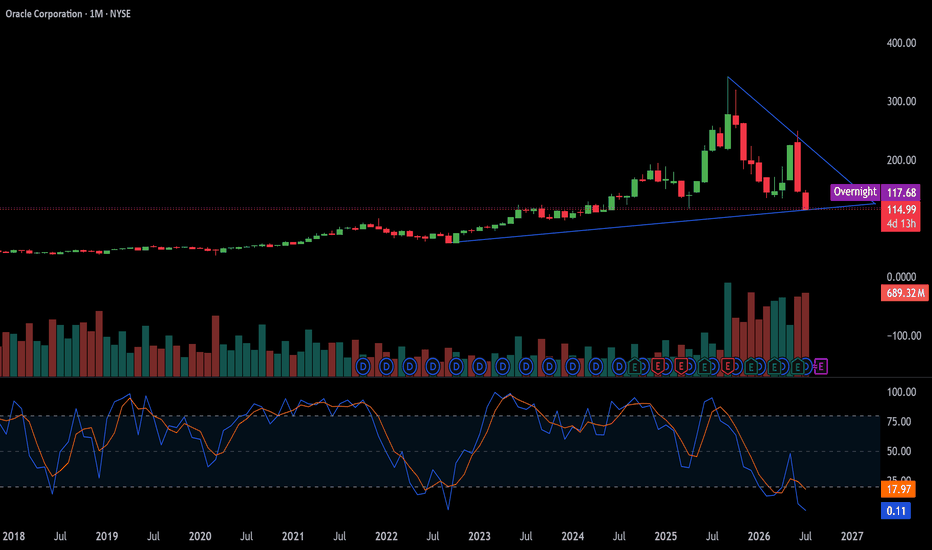
Can Oracle Survive Its $638B AI Gamble?Macroeconomics and the AI Capex Balancing Act
Oracle stands at a pivotal crossroads in financial history. The enterprise technology titan is aggressively scaling its artificial intelligence infrastructure globally. Capital expenditures eclipsed $55 billion recently, squeezing short-term cash flows significantly. Consequently, equity markets experienced intense volatility surrounding infrastructure debt.
Yet, Oracle commands a monumental $638 billion remaining performance obligation backlog. Major tech leaders like OpenAI and Meta drive this unprecedented contract pipeline. Macroeconomic high-interest environments demand strict capital discipline from hyper-scalers. However, Oracle’s long-term backlog guarantees predictable revenue for nearly a decade. Investors now weigh heavy infrastructure debt against guaranteed future cash flows.
Geopolitics and the $7 Billion Defense Lifeline
Geopolitical instability elevates the demand for resilient military software systems. The U.S. Department of War recently awarded Oracle a historic $7 billion contract. This decade-long enterprise agreement consolidates software procurement across military branches and intelligence agencies. DoD leadership estimates this contract structure will save taxpayers over $441 million.
The deal reinforces Oracle’s enduring partnership with critical national defense infrastructure. Intelligence agencies have relied on Oracle database architectures since the 1970s. This massive federal contract provides a stable financial cushion during volatile market cycles. It confirms Oracle as a fundamental cornerstone of Western national security infrastructure.
Geostrategy and Global Sovereign Cloud Infrastructure
Nations increasingly demand sovereign control over digital infrastructure and localized data processing. Oracle addresses this geostrategic mandate by deploying isolated sovereign cloud regions across multiple continents. From North America to Asia, domestic enterprises rely on localized Oracle Cloud Infrastructure.
For instance, South Korean AI startups deploy local Oracle cloud regions to expand globally. This localized infrastructure satisfies strict data residency laws without sacrificing compute performance. By respecting regional jurisdiction, Oracle bypasses complex international regulatory friction. Their strategic cloud footprint builds deep, irreplaceable bonds with foreign enterprise markets.
Business Models: Multicloud and Chip Neutrality
Oracle disrupted traditional cloud dynamics through a radical multicloud business model. The company embeds its database software directly inside Amazon AWS, Microsoft Azure, and Google Cloud. Customers deploy Oracle databases seamlessly across any preferred cloud environment.
Furthermore, Oracle divested its stake in chipmakers to adopt total “chip neutrality.” Oracle Cloud Infrastructure supports NVIDIA GPUs alongside alternative silicon architectures flexibly. This open strategy transforms historical rivals into collaborative infrastructure partners. Revenue streams now originate from multi-tenant cloud consumption rather than static enterprise software licenses. This structural evolution significantly expands Oracle’s addressable enterprise market.
Industry Trends and High-Tech AI Supercomputing
Generative AI model training requires unprecedented GPU compute cluster configurations. Oracle engineered ultra-fast cloud networking architectures specifically for massive AI supercomputing workloads. Consequently, frontier AI labs select Oracle to train next-generation large language models.
Industrial sector trends show a rapid transition from basic cloud hosting to specialized AI acceleration. Oracle satisfies this shift through high-density liquid-cooled data centers. Their infrastructure handles intense computational throughput with minimal latency. This technical superiority secures strategic deals with industry leaders like OpenAI and NVIDIA.
Management Strategy and Relentless Vision
Chairman and Chief Technology Officer Larry Ellison continues to direct corporate strategy decisively. Management maintains a relentless focus on high-margin enterprise cloud execution. Executive leadership boldly shifted corporate resources toward AI infrastructure construction despite Wall Street skepticism.
CEO Safra Catz executes strict financial operations to protect core margins during aggressive expansions. Management periodically reshapes operational divisions to align with enterprise demand. This assertive leadership maintains institutional agility despite Oracle’s massive global size. Ellison’s bold strategic bet positions Oracle as a premier AI infrastructure provider.
Technology, High-Tech, and Agentic AI Workflows
Oracle is pioneering the enterprise transition toward autonomous agentic applications. The company launched its Fusion AI Agent Studio alongside developer command-line interfaces. Developers build specialized AI agents that execute complex business workflows automatically.
These autonomous agents integrate directly into enterprise resource planning and human capital systems. They analyze operational data, automate approvals, and execute decisions independently. This technological leap transforms passive enterprise software into proactive digital workforces. Oracle leads the high-tech evolution from simple data retrieval to autonomous operational execution.
Patent Analysis and Intellectual Property Moats
A thorough patent analysis highlights Oracle’s overwhelming technical defensibility. The enterprise retains thousands of patents spanning autonomous database management, dynamic memory allocation, and cryptographic security. Their intellectual property covers automatic index tuning and automated transaction processing algorithms.
These patented innovations allow databases to patch, tune, and optimize themselves continuously without human intervention. Competitors struggle to match Oracle’s proprietary transaction processing performance. This robust patent portfolio protects core enterprise database revenues from market disruption.
Cybersecurity Infrastructure and Mission-Critical Trust
Modern cyber threats require automated, continuous enterprise defense mechanisms. Oracle embeds zero-trust architecture into the core layer of its cloud infrastructure. Autonomous Database systems apply security patches automatically without interrupting live business operations.
This eliminates human error, which remains the leading cause of enterprise data breaches. Military branches and financial institutions trust Oracle to isolate multi-tenant customer workloads completely. Cryptographic data isolation ensures complete privacy across cloud environments. This ironclad cybersecurity posture makes Oracle indispensable for mission-critical enterprise applications.
Pharmaceutical and Healthcare Data Synergies
Oracle deeply integrates specialized cloud infrastructure into the global healthcare and pharmaceutical sectors. Following its Cerner acquisition, Oracle modernized electronic health record systems nationwide. Pharmaceutical giants leverage Oracle Cloud Infrastructure to accelerate complex clinical trial processing.
Advanced analytics platforms process vast genomic sequences to shorten drug discovery timelines dramatically. Secure cloud databases manage global pharmaceutical supply chains to prevent counterfeit distribution. By combining healthcare data with secure cloud compute, Oracle accelerates life-saving medical science.
Scientific Computing and Next-Gen Enterprise Data
Modern scientific research requires high-performance computational clusters and precise data modeling. Researchers utilize Oracle Cloud Infrastructure to process complex mathematical simulations and climate models. Data scientists execute advanced neural network training on massive multi-terabyte datasets.
Oracle’s relational-database architecture structures complex scientific research data with absolute mathematical fidelity. The platform delivers high throughput and reliable transaction consistency for critical research institutions. Consequently, Oracle accelerates scientific breakthroughs across physics, genetics, and material sciences globally.
Conclusion
Oracle’s massive $638 billion backlog justifies its bold infrastructure investment strategy. While heavy capex spending created short-term stock volatility, the long-term fundamentals remain solid. Securing the $7 billion Pentagon contract proves irreplaceable strategic value to national security. Innovations like AI Agent Studio and multicloud partnerships drive sustainable enterprise relevance. Oracle successfully transformed from a traditional database vendor into a dominant AI cloud pillar. As enterprise AI adoption accelerates worldwide, Oracle’s high-performance infrastructure will power the future.  Long
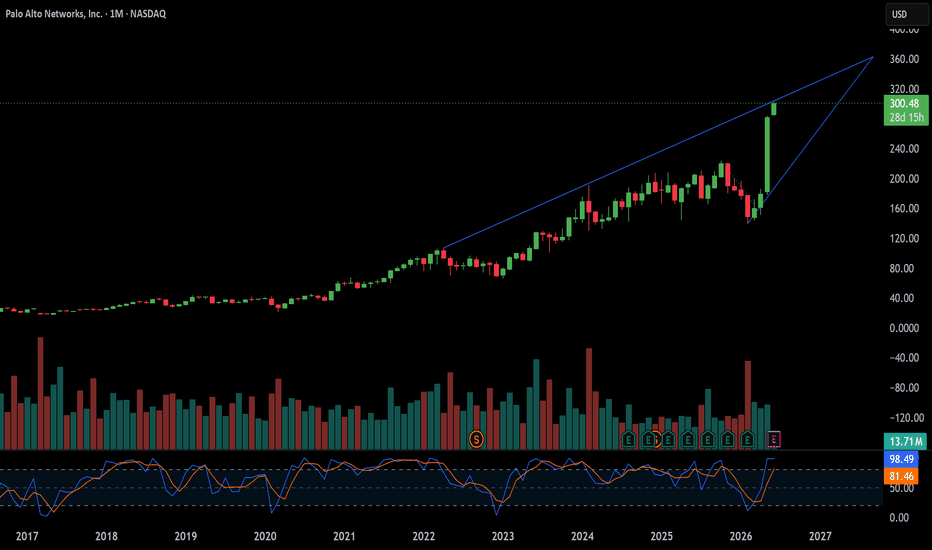
Can Palo Alto Networks Monopolize Global Cyber Defense?Cyber warfare is fundamentally re-engineering global capital markets. Palo Alto Networks (PANW) sits at the absolute epicenter of this tectonic shift. The company reports fiscal third-quarter 2026 earnings today, June 2, 2026, after the market close.
Options markets anticipate an aggressive 8% stock swing following the announcement. The stock has rallied more than 100% from its year-to-date low and trades near all-time highs around $281 to $303. Investors actively debate if the recent rally overextends the valuation.
However, traditional financial metrics fail to capture the massive strategic moats surrounding this tech giant. Wall Street consensus expects Q3 revenue of $2.94 billion (+28-29% YoY) and non-GAAP EPS of $0.79-0.80. Next-Gen Security ARR guidance sits at $7.94-7.96 billion (+56% YoY). Remaining Performance Obligations should clear the $17.85-17.95 billion range. To understand the future of Palo Alto Networks, we must analyze its structural advantages across several vital domains.
Geopolitics and Geostrategy
National defense no longer relies solely on physical weaponry. In late May 2026, NATO formally selected Palo Alto Networks for a strategic cybersecurity partnership alongside Microsoft and ESET. The alliance provides NATO's 32 member states with structured access to threat intelligence and defensive expertise.
The deal operates as a policy channel rather than a traditional vendor relationship. The structure bypasses standard procurement cycles while embedding Palo Alto Networks at the heart of Western cyber defense.
Palo Alto Networks now operates as a core defensive pillar for Western democracies. The geostrategic alignment creates deep government dependencies that compound over time.
Furthermore, sovereignty demands resilient networks against state-sponsored actors.
Consequently, Palo Alto Networks secures long-term, high-assurance federal budgets that economic downturns cannot easily disrupt. The Trump administration recently issued a White House directive ordering federal agencies to adopt AI-enhanced cyber threat detection.
Macroeconomics and Economics
Stubborn inflation forces enterprises to trim discretionary software spending. Yet, systemic cyber threats prevent companies from cutting security budgets. The economic reality benefits Palo Alto Networks tremendously.
The company commands incredible pricing power in a fragmented market. Its platformization strategy drives consolidation across corporate IT infrastructures.
Customers eagerly replace multiple niche vendors with a single comprehensive architecture. The economic consolidation protects revenue margins.
Moreover, Wall Street analysts boosted price targets aggressively heading into Q3 earnings. Jefferies and Wedbush both raised their Palo Alto Networks price targets to $300. The platformization strategy ensures steady cash flows despite unpredictable global macroeconomic conditions.
Industry Trends and Business Models
The cybersecurity landscape is transitioning away from disjointed point solutions. Industry trends heavily favor unified, cloud-native environments. Palo Alto Networks pioneered this platform shift with its aggressive "platformization" business model.
The company bundles network, cloud, and operational security into a single subscription. The model drives high customer retention rates.
The strategy also creates lucrative upselling opportunities. Enterprises willingly expand contract values to secure expanding digital footprints.
Furthermore, the CyberArk acquisition (~$25 billion deal) dramatically expands platform breadth across identity security. The Protect AI acquisition enhances AI workload security capabilities. The Portkey AI gateway acquisition extends LLM monitoring and governance into the core platform. The strategic shift maximizes annual recurring revenue and locks in enterprise long-term commitments.
Management, Leadership, and Culture
CEO Nikesh Arora executes a bold corporate vision with unmatched discipline. His leadership team prioritizes aggressive consolidation over conservative, incremental growth. Palo Alto Networks fosters a high-performance corporate culture centered on rapid, disruptive innovation.
Management frequently acquires bleeding-edge startups to stay ahead of market demands. Recent acquisitions include Portkey, Protect AI, and the announced CyberArk deal.
The executive team aligns the ambitious culture with clear financial targets. The operational alignment wins immense trust from institutional investors.
Furthermore, CEO Nikesh Arora purchased thousands of Palo Alto Networks shares in late March 2026. The insider buying reinforces management confidence in the long-term thesis. Insider conviction at all-time-high valuations sends a powerful signal to institutional buyers.
Technology, Cybersecurity, and High-Tech
Modern attackers deploy highly sophisticated, machine-speed tactics. In response, Palo Alto Networks built an advanced high-tech defense ecosystem. The company deploys Cortex XSIAM as its AI-driven security operations platform.
Prisma AIRS protects enterprise AI workloads against emerging adversarial threats. Strata AI agents extend autonomous defense across network security infrastructure.
However, immense scale also brings technological risks. Attackers recently exploited a critical PAN-OS firewall zero-day vulnerability tracked as CVE-2026-0300. The vulnerability allows unauthenticated root access to affected firewall systems.
Furthermore, CISA issued a mandatory mitigation deadline ahead of full patch availability. Palo Alto Networks responded with rapid hotfixes and Prisma Access upgrades. The swift technological response underscores superior engineering capabilities. The CyberArk acquisition further strengthens identity-layer defenses against credential-based attacks.
Science and Patent Analysis
Scientific innovation serves as the bedrock of Palo Alto Networks' technological advantage. The company invests heavily in data science, predictive analytics, and automated machine learning. A comprehensive patent analysis highlights an expanding intellectual property moat.
Palo Alto Networks holds essential patents in zero-trust architecture, advanced telemetry, and cloud-workload isolation. The proprietary technologies prevent rivals from replicating its security platforms.
The company translates theoretical computer science into concrete, commercial security protocols. The deep scientific approach safeguards its market-leading position.
Moreover, Prisma AIRS represents the next frontier in AI workload protection. Protect AI integration extends model-level threat detection across enterprise deployments. Patent portfolios increasingly focus on LLM security, agentic workload defense, and identity-based zero-trust frameworks.
The Financial Verdict
Is Palo Alto Networks overvalued? The market clearly pays a premium for absolute platform dominance.
Catalysts and risks to monitor through Q3 earnings include:
Q3 FY26 revenue beat above $2.94B consensus
NGS ARR exceeding $7.96B (true platformization gauge)
RPO clearing $17.95B (long-term commitment visibility)
CyberArk integration timeline and synergy commentary
CVE-2026-0300 patch deployment progress
White House federal AI cyber directive procurement opportunities
Competitor pressure from CrowdStrike, Zscaler, Fortinet
Memory and processor cost inflation (Zscaler signal)
Stock currently overbought on technical indicators
The company transforms necessary enterprise spending into an unassailable tech monopoly. Tonight's earnings print on June 2, 2026, represents the next major catalyst for PANW shareholders. Investors should watch the NGS ARR and platformization metrics closely for confirmation of the structural thesis through 2027.  Long
What Drives SoundHound AI's Relentless Market Volatility?
SoundHound AI (NASDAQ: SOUN) trades with sharp swings around earnings and product announcements. The stock dropped roughly 13% to around $8.41 the day after Q1 2026 results on May 7, even as the company reported record quarterly revenue of $44.2 million (up 52% year-over-year) and beat consensus EPS expectations. Mean analyst price target sits at $14.63. Several distinct forces drive SOUN's volatility.
Macroeconomics and Economics
Broader macroeconomic conditions matter to SOUN's valuation. High interest rates compress multiples for unprofitable growth companies, and SoundHound continues to post GAAP net losses (Q1 2026: $25.0 million net loss, GAAP EPS of -$0.06) despite record revenue. The company targets a $140 billion-plus total addressable market across automotive, restaurants, enterprise AI, smart devices, and voice commerce. Shifting enterprise spending budgets and a still-elevated rate environment force investors to keep weighing growth trajectory against persistent operating losses. The company is guiding 2026 revenue of $225 to $260 million and is targeting adjusted EBITDA profitability over time. The path there is the central debate that drives intraday volatility around every earnings print.
Geopolitics and Global Exposure
International tariffs and supply chain disruptions affect global automotive manufacturing, which directly touches SoundHound's royalty-bearing automotive deployments. Q1 2026 saw a new seven-figure global vehicle deployment with a major Japanese automaker, doubled committed units with another Japanese manufacturer, and expansion into South America with a multinational automotive OEM. Hostile regulatory environments abroad can complicate AI deployments, and trade tensions can derail hardware shipments. Stripping out acquisitions, SoundHound's automotive and IoT AI business grew 88% year-over-year in Q1 2026, so the OEM pipeline is a meaningful chunk of organic growth and a real sensitivity to global trade headlines.
Technology, Science, and High-Tech
SoundHound's Polaris speech foundation model anchors its technology stack. Management states that Polaris consistently beats third-party large language models in accuracy and performance for enterprise use cases. The company recently launched OASYS (Orchestrated Agent System), a platform designed to let businesses build AI agents in minutes and deploy them across phone, text, web chat, kiosks, social media, televisions, and vehicles. OASYS will be powered by Polaris and specialized in-house language and synthesis models, with the explicit goal of reducing dependence on third-party frontier models. Management says the foundation-model investment will stay below 1% of market capitalization this year. The technology positions SoundHound against larger competitors like Cerence and the voice efforts of Amazon and other big tech players. Breakthrough technical announcements have historically triggered material moves in the stock.
Patent Position and Operational Risk
SoundHound holds a portfolio of conversational AI and speech recognition patents that support its differentiation against competitors. Like any enterprise software company handling large volumes of customer data, cybersecurity is a real operational expense and an ongoing risk to manage. However, cyber incidents have not historically been a meaningful driver of SOUN's price volatility. The more impactful idiosyncratic risks for the stock are quarterly revenue misses against a premium multiple, integration friction from frequent acquisitions, persistent GAAP losses, share dilution from stock-based compensation, and any slowdown in the auto OEM pipeline.
Business Models and Industry Trends
SoundHound has pivoted decisively from its consumer roots toward enterprise conversational AI. The company is in the middle of integrating its fifth strategic acquisition. SoundHound announced a definitive agreement to acquire LivePerson (NASDAQ: LPSN) for an equity value of $43 million (about a 22% premium over the 30-day VWAP), with the deal expected to close in the second half of 2026. The combined business would serve customers in more than 30 countries, including 25 of the Fortune 100, 12 of the top 15 global banks, four of the top five global airlines, and four of the top five global automakers. Management has guided that the combined company can reach $500 million in revenue based on the existing customer base alone, with a 2027 achievable revenue range of $350 to $400 million (including at least $100 million from LivePerson). Voice commerce is positioned as a long-term growth engine. The market punishes revenue misses heavily, given the premium multiple.
Management, Leadership, and Company Culture
CEO and co-founder Keyvan Mohajer drives SoundHound's product and acquisition strategy alongside CFO Nitesh Sharan and the broader executive team. Management has been explicit that customer migration to OASYS is the company's biggest near-term priority and that the LivePerson integration is "transformational." Investors are watching closely for whether the ambitious 2027 revenue targets are realistic, whether acquisition synergies emerge over the next two quarters as guided, and whether GAAP losses narrow toward sustainable profitability. SoundHound ended Q1 2026 with $216 million in cash and no debt, which gives management runway to execute. Strong execution is the path back to a higher multiple. Any miss on those fronts will keep the stock volatile.  Long

C3.ai Strategic Analysis: Enterprise AI and Market ShiftsC3.ai remains a lightning rod for market volatility and investor debate. Recent data highlights an "options anomaly," suggesting a potential short squeeze. Traders are monitoring high short interest against a backdrop of surging enterprise demand. This analysis explores the thirteen domains driving C3.ai’s current market fluctuations.
The Options Anomaly and Market Volatility
Technical indicators currently signal a significant shift in sentiment. C3.ai faces high short interest, yet call option volume is spiking. This friction often precedes a rapid price breakout or "squeeze." Investors must distinguish between speculative noise and fundamental growth drivers.
Strategic Business Model Transformation
Thomas Siebel leads C3.ai with an assertive, veteran vision. The company recently transitioned to a consumption-based pricing model. This shift accelerates customer acquisition by lowering initial entry barriers. While it complicates short-term revenue recognition, it builds a massive long-term pipeline.
Management prioritizes market share over immediate GAAP profitability. This aggressive strategy mirrors early-stage cloud giants. Success depends on the company's ability to scale these new accounts rapidly.
Geostrategy and Federal Growth
Geostrategy plays a pivotal role in C3.ai’s revenue diversification. The company secures major contracts within the U.S. Department of Defense. Governments now demand "Sovereign AI" to protect national interests and data integrity.
C3.ai positions itself as a secure, domestic alternative to unregulated models. These federal partnerships provide a stable moat against global geopolitical instability. National security requirements ensure a consistent demand for enterprise-grade intelligence.
Technological Innovation and IP Strength
Technology remains the core of C3.ai’s competitive advantage. Unlike consumer-facing bots, C3.ai focuses on industrial-scale "Enterprise AI." Their software integrates seamlessly with cloud leaders like AWS, Google Cloud, and Azure.
Patent analysis reveals a deep focus on predictive maintenance and supply chain optimization. These tools apply complex data science to solve trillion-dollar industrial inefficiencies. The company’s IP portfolio protects unique algorithms that process massive datasets in real-time.
Cybersecurity and Secure Science
Cybersecurity is no longer an optional feature for AI providers. C3.ai builds its applications with a "security-first" architecture. This approach protects sensitive corporate data from leaks and external breaches.
The scientific application of their AI extends to energy and manufacturing. By predicting equipment failure, C3.ai reduces environmental waste and operational risks. This intersection of science and software creates tangible value for heavy industry.
Macroeconomic Resilience in Tech
Macroeconomic factors continue to influence tech valuations globally. High interest rates typically pressure growth stocks like C3.ai. However, AI remains a non-discretionary spend for corporations seeking efficiency.
Economics dictate that companies must automate to survive rising labor costs. C3.ai benefits from this structural shift in the global economy. As long as AI delivers a clear ROI, enterprise spending will likely persist.
Conclusion: Navigating the Breakout
C3.ai stands at a critical crossroads between speculation and fundamental utility. The potential for a short squeeze adds immediate excitement for technical traders. However, long-term success relies on Siebel’s leadership and the consumption-based model.
Investors should watch federal contract wins and quarterly consumption metrics. If C3.ai maintains its technological edge, it may dominate the enterprise landscape. Prepare for continued volatility as the market digests these complex domain shifts.  Long

Palantir (PLTR) — AIP Flywheel + Profitability at ScalePalantir NASDAQ:PLTR builds AI-powered data platforms—Gotham, Foundry, and AIP—used by governments and enterprises to integrate complex data, run workflows, and execute decisions at scale.
Key Catalysts
AIP-Driven Commercial Breakout: U.S. commercial revenue surged +137% YoY to $507M, alongside $1.34B in U.S. commercial contract value, signaling a step-change in enterprise AI adoption.
Hypergrowth + Profitability: Reported $1.41B revenue (+70% YoY) with 57% operating margins—a rare combination that drives a standout Rule of 40 score ~127%.
AI Infrastructure Positioning: Palantir is increasingly viewed as “operating system” infrastructure for AI deployment—especially in regulated, mission-critical environments (defense, healthcare, industrials).
Strong Forward Outlook: Guidance implies ~61% growth in 2026, reinforcing momentum as AIP expands from pilots into large-scale rollouts.
Investment Outlook
Bullish above: $128–$130
Upside target: $190–$200, supported by accelerating commercial penetration, expanding margins, and long-duration AI platform demand.  Long

Zoom Communications (ZM) AnalysisCompany Overview:
Zoom NASDAQ:ZM is an AI-first collaboration platform across Meetings, Chat, Phone, Contact Center, and Events, giving investors exposure to unified communications, hybrid work, and enterprise AI adoption.
Hidden Value Driver — Anthropic Stake:
Zoom’s stake in Anthropic is an underappreciated asset, with analysts estimating it at $2B–$4B—a substantial gain versus the original $51M investment. Beyond valuation, it supports Zoom’s strategy by accelerating AI-native features that improve retention and platform stickiness.
AI Product Momentum:
Zoom AI Companion now powers meeting summaries, task extraction, content generation, and workflow automation across the suite.
Partnerships like InteractifAI and CaptivAIte strengthen webinars, events, and enterprise communications, opening higher-value engagement and new monetization paths.
Financial Strength:
Zoom continues to deliver revenue/EPS beats, raise guidance, and expand margins—backed by a debt-free balance sheet and strong cash flow to fund AI, strategic growth, and shareholder returns.
Investment Outlook:
✅ Bullish above: $81–$82
🎯 Upside target: $125–$130 Long 
ZM (Zoom Communications) — Earnings in 6 Days: AI Platform Pivot**💡 ZM (Zoom Communications) — Earnings in 6 Days: AI Platform Pivot Delivers Stable Growth at Bargain Valuation | Buy**
**SECTION 1 — Executive Summary** 💼
Zoom has matured from pandemic video darling into a profitable, cash-rich AI-first collaboration platform with accelerating enterprise traction and massive untapped TAM. With Q4/FY26 earnings on Feb 25, 2026 and AI monetization ramping, the stock offers asymmetric upside at just 15.3x forward EPS while sporting a fortress balance sheet.
**Overall rating: Buy**
**12-month price target: $120** (methodology: 50% DCF + 50% peer comps at 20x FY27 EPS)
**Biggest reason to own:** Dominant 56% video-conferencing share + AI Companion/ Contact Center expansion into a $262B UCaaS TAM by 2030.
**Biggest risk:** Intensifying competition from Microsoft Teams in the enterprise segment.
**SECTION 2 — Business Overview** 🏢
Zoom Communications delivers a unified, AI-powered work platform for video meetings, phone, chat, webinars, and contact-center solutions — all cloud-native with 99.9% uptime.
**Revenue breakdown (FY25, latest detailed):** Americas 71.8%, EMEA 16%, APAC 12.2%; enterprise customers now ~60% of revenue.
**Business model:** Subscription-based (Pro/Business/Enterprise plans) + usage add-ons; 80%+ gross margins and 90%+ net dollar retention in enterprise drive highly predictable, recurring revenue.
**Competitive moat:** Unmatched brand (“Zoom” is a verb), massive network effects (300M+ users), seamless third-party integrations, and first-mover AI features (Zoom AI Companion now free, with paid upsell path).
**SECTION 3 — Financial Deep Dive** 📈
**Key metrics (TTM as of 10/31/2025, Yahoo Finance):**
Revenue: $4.81B
Net income: $1.59B
EPS: $5.14
Gross margin: ~77%
Operating margin: 25.24%
FCF: $2.02B
Total debt: $48M (virtually net-cash position with $7.94B cash)
**Last 4 quarters (Yahoo Finance / company filings):**
• Q3 FY26 (10/31/25): Rev $1.23B (+4.4% YoY), EPS $1.52 (beat)
• Q2 FY26 (7/31/25): Rev $1.22B, EPS $0.99
• Q1 FY26 (4/30/25): Rev $1.17B, EPS $1.43
• Q4 FY25 (1/31/25): Rev ~$1.18B (implied)
**YoY growth:** Revenue +4.4% (Q3), earnings +196% (one-time gain impact noted).
**Balance sheet health:** Current ratio 4.45, debt/equity 0.52% — pristine.
**Cash flow quality:** Operating cash flow TTM $2.06B vs net income $1.59B (strong, even after adjusting for one-off gain).
**Capital allocation:** Aggressive buybacks ($1.65B TTM), zero dividend, selective M&A in AI/contact-center space.
**SECTION 4 — Growth Analysis** 🚀
**Total addressable market (TAM):** UCaaS $87.4B (2024) → $262.6B (2030) at ~20% CAGR (Grand View Research, 2025); video conferencing subset ~$8B → $13.3B at 10.8% CAGR (Business Research Company, 2026).
**Current market share:** 55.9–56% global video conferencing (Demandsage/Statista, 2025–2026 data).
**Key growth drivers next 3–5 years:** AI Companion monetization, Zoom Phone/Contact Center expansion, international enterprise penetration.
**Management guidance vs consensus:** FY26 revenue ~$4.85–4.86B (+4% YoY), EPS $5.95–5.97; analysts aligned but see AI as upside catalyst.
**Growth organic:** Yes, with AI features driving higher ARPU without heavy acquisition reliance.
**SECTION 5 — Valuation** 📊
**DCF analysis :** 6% revenue CAGR 2026–2030 to ~$6.5B, operating margin expanding to 28%, WACC 9%, terminal growth 3.5% → implied fair value ~$118 (Yahoo Finance data as of 2/19/2026).
**Comparable company analysis (forward P/E, selected peers as of 2/19/2026):**
MSFT 35x | CRM 26x | NOW 48x | ADBE 32x | Average ~35x
Zoom trades at 15.3x FY26 EPS — 56% discount.
**Historical valuation range (5-year P/E):** 15x–120x; current at low end.
**Bull $140** (15%+ growth, AI hyper-monetization)
**Base $120** (6–8% growth, steady margins)
**Bear $75** (growth <3%, share loss)
**Current price ~$91.50 vs targets:** Base +31% upside.
**SECTION 6 — Risk Analysis** ⚠️
1. **Competition from Microsoft Teams** (high prob/impact) — trigger: continued enterprise displacement; watch: enterprise NDR <90%.
2. **Slower AI monetization** (medium) — trigger: weak Q4 guidance; watch: AI Companion paid conversion rate.
3. **Macro enterprise IT spend slowdown** (medium) — trigger: recession; watch: new customer adds.
4. **Data privacy/regulatory scrutiny** (low-medium) — trigger: new GDPR-style rules.
5. **Execution risk on new products** (low) — trigger: Contact Center delays.
**Short interest:** 2.41% of float (Yahoo, 1/30/2026) — low.
**Insider ownership:** 0.26%, no major selling flagged.
**Accounting flags:** None; clean, conservative.
**SECTION 7 — Catalyst Calendar** 📅
**Next earnings:** February 25, 2026 (after close) — Q4/FY26 results + guidance.
**Upcoming:** Morgan Stanley Technology Conference (March 2, 2026).
**Product/regulatory:** Ongoing AI Companion rollouts, potential Contact Center wins.
**Macro:** Fed rate path impacts enterprise budgets.
**12-month timeline:** Q1 earnings May 2026, AI feature monetization updates throughout 2026.
**SECTION 8 — Relevant Data & Charts** 📊
**Quarterly Revenue Trend (StockStory):** Steady climb to $1.23B in Q3 FY26 despite post-pandemic normalization — proves durable business model.
**UCaaS TAM Projection (Grand View Research):** $87B → $262B by 2030 validates Zoom’s platform expansion thesis.
**Video Conferencing Market Forecast (Business Research Co.):** $7.95B (2025) → $13.32B (2030) at 10.8% CAGR — Zoom’s core engine still growing solidly.
**SECTION 9 — Technical Analysis** 📈
**Primary Chart:** Daily, 1-year view (TradingView data as of 2/19/2026).
**Key observations:**
- Price ~$91–92, trading above 50-day and 200-day MAs (uptrend intact).
- RSI(14) neutral-positive (~55–60 range implied by momentum).
- MACD bullish crossover forming.
- Major support: $80–83 zone; resistance: $95–100.
- Pattern: Higher lows since 2024, potential breakout on earnings beat.
**Technical implication:** Constructive setup for near-term catalyst-driven move higher.
**SECTION 10 — The Verdict** 🏆
**Bull case (40% prob):** $140 — AI monetization exceeds expectations, 10%+ growth returns.
**Base case (50% prob):** $120 — steady 5–7% growth, margin expansion.
**Bear case (10% prob):** $75 — material share loss or macro hit.
**Expected value:** $118 (probability-weighted).
**Final recommendation:** Buy — High conviction.
**30-second elevator pitch:** At 15x forward earnings with $8B net cash, 56% market share, and AI tailwinds, Zoom is the cheapest high-quality compounder in software ahead of its Feb 25 earnings — load up.
**Sources**
Yahoo Finance (key stats, quote, analysis — accessed 2/19/2026)
Zoom Investor Relations (earnings announcements, 1/29/2026 & 2/19/2026)
Grand View Research UCaaS Report (2025)
Business Research Company Video Conferencing Report (2026)
Demandsage/Statista market share data (2025–2026)
StockStory, MarketBeat, TradingView (charts & technicals, Feb 2026)
All forward-looking statements labeled are analyst-derived.
What are your thoughts on ZM? Drop them below 👇 Long 
 Long