Palo Alto Earnings | The AI Security Boom Is HerePalo Alto Networks wrapped up Q4 FY26, ending in July, with revenue up 34% year over year to $3.4 billion, beating estimates by $60 million. NonGAAP EPS came in at $1.02, $0.04 above expectations
The headline growth numbers are still somewhat distorted by acquisitions, but the underlying demand was strong.. Palo Alto added a record $970 million in net new Next Gen Security ARR and completed roughly 220 net new platformizations, up 44% year over year and roughly double Q3. In simple terms, more customers are choosing to buy multiple Palo Alto products instead of individual security tools
The company ended FY26 with a 38% adjusted free cash flow margin, maintaining its high 30% profitability even after absorbing two major acquisitions, CyberArk and Chronosphere
GAAP results looked much worse, with Palo Alto reporting a $282 million net loss. However, much of that was driven by accounting items rather than the underlying business. The quarter included a $524 million mark to market loss tied to CyberArk convertible notes, $281 million in acquired intangible amortization, and $487 million in stock based compensation
For FY27, Palo Alto expects revenue of $14.1 billion to $14.2 billion, implying roughly 23% to 24% growth and coming in above consensus. Management expects NGS ARR to grow 22% to 23% to around $11.1 billion, while maintaining its 38% adjusted FCF margin target
Management also reaffirmed its goal of reaching a 40%+ adjusted free cash flow margin in FY28 and $20 billion in NGS ARR by FY30
For investors, the biggest question is whether Palo Alto's aggressive M&A strategy can create meaningful synergies rather than simply adding revenue. So far, the early cross-selling data is encouraging.
Platformization Is Accelerating
Next Gen Security ARR reached $9.1 billion, up 63% year over year, while remaining performance obligations climbed 34% to a record $21.2 billion
Those figures still benefit significantly from the CyberArk and Chronosphere acquisitions, so they shouldn't be treated as purely organic growth. But Palo Alto also provided a clearer look at how its individual platforms are performing:
Network & AI Security revenue: +17% Y/Y
Cortex revenue: +25%
Idira, the rebranded CyberArk business: +21% on a pro forma basis
Each major platform is therefore still growing at a healthy double digit rate
More importantly, customers are consolidating more of their security spending with Palo Alto. Net retention among platformized customers remained above 120%, and more than 65% of NGS ARR now comes from platformized customers
The company's largest customers are also spending more. Customers generating more than $5 million in NGS ARR increased 45% year over year to 223, while those spending more than $10 million rose 50% to 78
One Q4 telecom deal alone was worth $126 million and included firewalls, SASE, Idira, and Cortex XSIAM. That's exactly the type of multi-product adoption Palo Alto is trying to build its platform around.
The AI Security Stack Is Coming Together
AI agents are creating a completely new security challenge. They generate machine-to-machine traffic, use credentials, access internal data, and increasingly perform tasks without direct human involvement
Palo Alto says agentic traffic across SASE has increased more than 9x in just nine months. That makes AI a growing attack surface, but it also creates a strong reason for companies to upgrade older security infrastructure
Palo Alto is positioning its platform around three major layers
Prisma AIRS: Secure the AI. ARR reached roughly $120 million just one year after launch, making AIRS the company's fastest-scaling product. Customers increased from more than 300 in Q3 to over 800 in Q4. The platform now covers runtime security, agent identities, red teaming, observability, and agent gateways
Cortex: Detect and respond. XSIAM ARR passed $700 million, up roughly 70% year over year, with nearly 1,000 customers. Chronosphere's observability ARR also exceeded $500 million, more than 2.5x its level just two quarters earlier. Even more interesting, half of Chronosphere's Q4 new logos included an XSIAM cross-sell, suggesting Palo Alto is already integrating the acquisition into its wider platform
Idira: Control identity and access. The $25 billion CyberArk acquisition gives Palo Alto control over the credentials and permissions used by humans, machines, and AI agents. Early results are promising. CyberArk ACV grew 27% year over year, Palo Alto won more than 200 new CyberArk customers from its existing installed base, and shared leads between the two sales teams have increased roughly 50% since May.
Put together, the strategy is relatively straightforward: AIRS secures AI applications and agents, Cortex detects and responds to threats, and Idira controls what those users and agents are allowed to access
And there's another piece to the puzzle: autonomous action
Alongside its earnings report, Palo Alto announced the acquisition of Console, an AI-native platform that allows users to create agentic workflows using natural language. The broader goal is to push Cortex beyond simply identifying security problems and toward AI agents that can investigate and remediate those problems automatically.
CEO Nikesh Arora described this evolution as the move toward "software as an agent."
Palo Alto is beginning to show that its acquisition strategy could create something more valuable than the individual businesses it has bought
Platformization is accelerating, AIRS is scaling quickly, and both CyberArk and Chronosphere are already showing signs of cross-selling into Palo Alto's existing customer base. At the same time, AI isn't just creating a new security threat. It's becoming a meaningful source of demand and revenue.
PANW Earnings SetupPANW reports Tuesday after the close, and this is another one where I’m leaning Green / Yellow over Red.
The options market is pricing roughly a ±8.5% move, which gives us an implied range around:
$340 downside / $403 upside
from Friday’s $371.59 close.
The interesting part is how much nearby structure is stacked around current price.
We have:
373 Projected AOA
376 Projected AOA
PDH around 379
382 Projected AOA
That gives us a very clean upside ladder before we even get to the implied-move boundary.
Green Scenario — Breakout + Continuation
If PANW beats, guidance stays strong, and price can reclaim and hold 376–382, then the bullish case gets interesting quickly.
That would open the path toward:
390s → 403 implied-move area
If PANW gets through that implied-move zone and actually builds support above it instead of immediately fading, then I would start thinking about a multi-day continuation into the low 410s+.
That’s the kind of move where I would rather wait for:
earnings impulse → pullback → support → continuation
than try to catch the first after-hours candle.
Yellow Scenario — Slower Recovery / Negotiation
This may be the most realistic middle path.
PANW could report good numbers without producing an explosive repricing.
In that case I’d expect price to spend time negotiating roughly between:
370–382
with repeated tests of 373 / 376 / PDH / 382.
If buyers keep defending the lower part of that range and PANW gradually starts producing higher lows, I’d keep the bullish thesis alive even without an immediate move to 403.
That slower recovery can still create a very clean trade.
Red Scenario — Lower Probability, Still Valid
If PANW loses current support and starts accepting below 370, then I’m watching:
358 → 354 → 353 → 351
That is a meaningful lower structure cluster.
If earnings create a violent flush through that entire area, the lower implied-move zone around 340 becomes much more realistic.
And just like the other earnings names, a fast overshoot into or through the implied-move boundary followed by a strong reclaim could also create an overreaction setup.
My Read
Right now I grade it:
Green / Yellow > Red
The upside structure is clean.
The downside structure is also well-defined.
So I don’t need to predict the earnings number.
I just need to know what price has to prove afterward.
Green: reclaim 376–382 and build above it.
Yellow: hold 370ish and recover more slowly.
Red: lose the lower structure and start accepting toward 358–351.
The earnings number is information.
The reaction + structure is the trade. A Valid Setup, Now Let the Market Decide in PANW
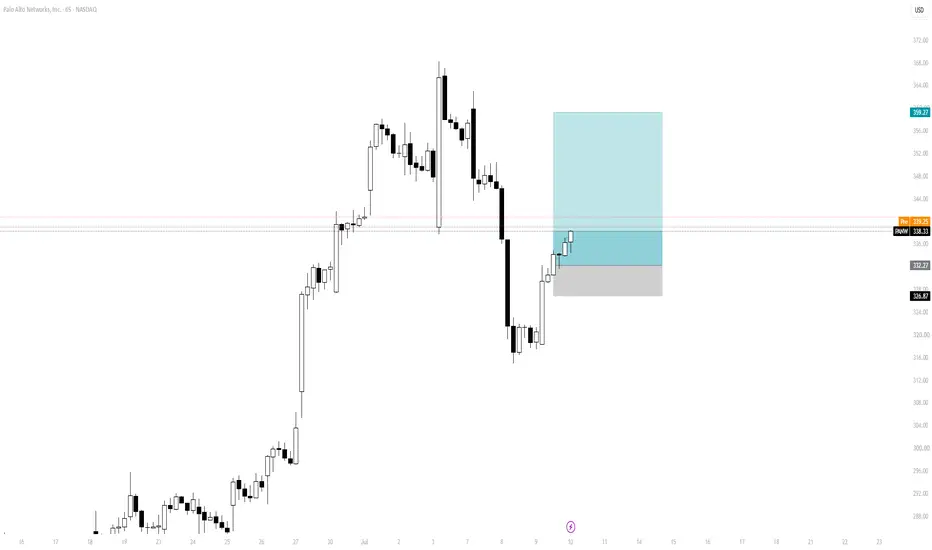
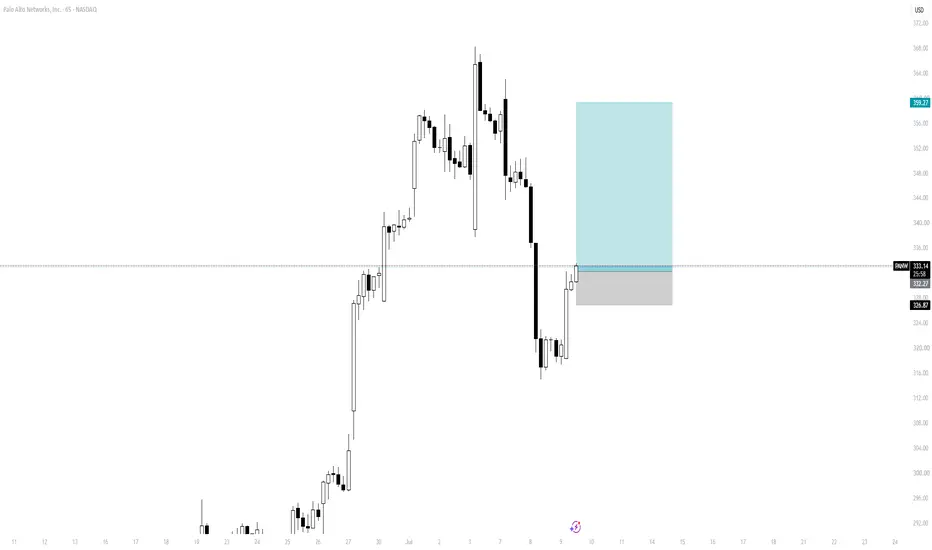
Yesterday I initiated a **long position in PANW** after the asset satisfied the conditions defined in my trading plan. The overall structure, order flow, and relative strength all aligned with the framework I use before committing capital.
Several other assets were also on my watchlist, but PANW was the first to present a valid entry. Once the position became active, I cancelled my remaining pending orders and shifted my full attention to managing this trade.
Shortly after entry, the market provided enough strength for me to move my stop-loss to **break-even**, leaving the position risk-free.
As I write this before today's market open, there are no significant overnight gaps. Price is expected to open close to yesterday's closing level, so the market will now determine the next step.
From here, only a few outcomes matter:
* The position reaches break-even.
* The trade develops further and allows partial profit-taking.
* Or the market provides new information that requires me to reassess the position.
The journal continues.
 Long

Pelosi & Trump Buy $UBER & $INTC, How We Get a Better DealWhen politicians and mega-investors make big stock moves, their required disclosures leave a direct footprint on the charts. But you don't have to blindly copy their exact trades. Sometimes you can get a way better price if you wait for the market to give you a discount. Perfect examples were NASDAQ:PANW , Pelosi (no longer own, but we're long term holding NASDAQ:BUG as we sold half recently), and NASDAQ:ICHR , forgot the politicians name.
Uber: Getting a Discounted Seat
The Big Money Trade: On May 29th, a massive single trade hit the options market. 200 contracts for the March 2027 $50 Calls. Congressional filings later confirmed this was Nancy Pelosi buying in at around $26.30 per share.
Our Entry: Instead of chasing her entry, we waited for a pullback and locked in the NYSE:UBER June 2027 $50 Calls at $22.88 & outright equity.
Why this is better: We paid $3.42 per share LESS than Pelosi, lowered our breakeven price from $76.30 down to $72.88, and bought 90 extra days of time for the stock to run up.
Intel: Already Sitting on Cheap Shares
The Play: Both Trump and Pelosi have been active here, but we aren't chasing new options on $INTC.
Our Position: We are already holding a core block of actual stock bought way lower in the $20 to $40 range, averaging up. When you already own cheap equity, there's no reason to force new trades. We sold half and we’ll just hold and let the position ride.
The Bottom Line: You don't need to copy political trades dollar for dollar. Use their filings as a high conviction watch list, wait for the market to cool off, and step in when the pricing and timeline give you the edge.
Long 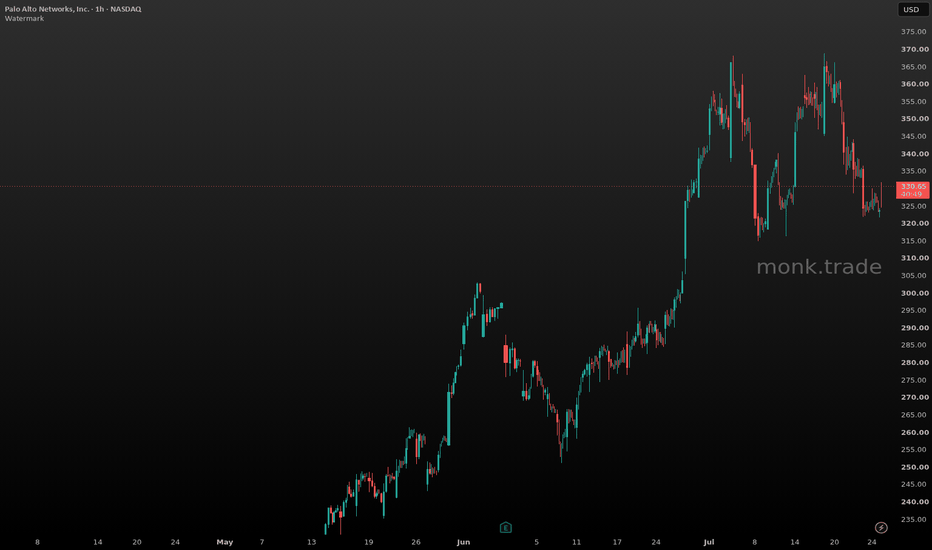
Long 
Long 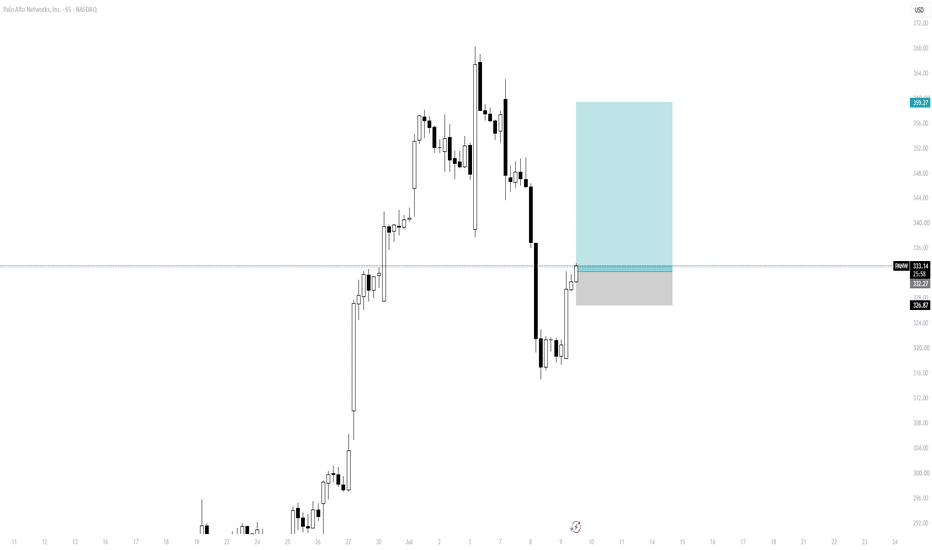
Can Palo Alto Networks Monopolize Global Cyber Defense?Cyber warfare is fundamentally re-engineering global capital markets. Palo Alto Networks (PANW) sits at the absolute epicenter of this tectonic shift. The company reports fiscal third-quarter 2026 earnings today, June 2, 2026, after the market close.
Options markets anticipate an aggressive 8% stock swing following the announcement. The stock has rallied more than 100% from its year-to-date low and trades near all-time highs around $281 to $303. Investors actively debate if the recent rally overextends the valuation.
However, traditional financial metrics fail to capture the massive strategic moats surrounding this tech giant. Wall Street consensus expects Q3 revenue of $2.94 billion (+28-29% YoY) and non-GAAP EPS of $0.79-0.80. Next-Gen Security ARR guidance sits at $7.94-7.96 billion (+56% YoY). Remaining Performance Obligations should clear the $17.85-17.95 billion range. To understand the future of Palo Alto Networks, we must analyze its structural advantages across several vital domains.
Geopolitics and Geostrategy
National defense no longer relies solely on physical weaponry. In late May 2026, NATO formally selected Palo Alto Networks for a strategic cybersecurity partnership alongside Microsoft and ESET. The alliance provides NATO's 32 member states with structured access to threat intelligence and defensive expertise.
The deal operates as a policy channel rather than a traditional vendor relationship. The structure bypasses standard procurement cycles while embedding Palo Alto Networks at the heart of Western cyber defense.
Palo Alto Networks now operates as a core defensive pillar for Western democracies. The geostrategic alignment creates deep government dependencies that compound over time.
Furthermore, sovereignty demands resilient networks against state-sponsored actors.
Consequently, Palo Alto Networks secures long-term, high-assurance federal budgets that economic downturns cannot easily disrupt. The Trump administration recently issued a White House directive ordering federal agencies to adopt AI-enhanced cyber threat detection.
Macroeconomics and Economics
Stubborn inflation forces enterprises to trim discretionary software spending. Yet, systemic cyber threats prevent companies from cutting security budgets. The economic reality benefits Palo Alto Networks tremendously.
The company commands incredible pricing power in a fragmented market. Its platformization strategy drives consolidation across corporate IT infrastructures.
Customers eagerly replace multiple niche vendors with a single comprehensive architecture. The economic consolidation protects revenue margins.
Moreover, Wall Street analysts boosted price targets aggressively heading into Q3 earnings. Jefferies and Wedbush both raised their Palo Alto Networks price targets to $300. The platformization strategy ensures steady cash flows despite unpredictable global macroeconomic conditions.
Industry Trends and Business Models
The cybersecurity landscape is transitioning away from disjointed point solutions. Industry trends heavily favor unified, cloud-native environments. Palo Alto Networks pioneered this platform shift with its aggressive "platformization" business model.
The company bundles network, cloud, and operational security into a single subscription. The model drives high customer retention rates.
The strategy also creates lucrative upselling opportunities. Enterprises willingly expand contract values to secure expanding digital footprints.
Furthermore, the CyberArk acquisition (~$25 billion deal) dramatically expands platform breadth across identity security. The Protect AI acquisition enhances AI workload security capabilities. The Portkey AI gateway acquisition extends LLM monitoring and governance into the core platform. The strategic shift maximizes annual recurring revenue and locks in enterprise long-term commitments.
Management, Leadership, and Culture
CEO Nikesh Arora executes a bold corporate vision with unmatched discipline. His leadership team prioritizes aggressive consolidation over conservative, incremental growth. Palo Alto Networks fosters a high-performance corporate culture centered on rapid, disruptive innovation.
Management frequently acquires bleeding-edge startups to stay ahead of market demands. Recent acquisitions include Portkey, Protect AI, and the announced CyberArk deal.
The executive team aligns the ambitious culture with clear financial targets. The operational alignment wins immense trust from institutional investors.
Furthermore, CEO Nikesh Arora purchased thousands of Palo Alto Networks shares in late March 2026. The insider buying reinforces management confidence in the long-term thesis. Insider conviction at all-time-high valuations sends a powerful signal to institutional buyers.
Technology, Cybersecurity, and High-Tech
Modern attackers deploy highly sophisticated, machine-speed tactics. In response, Palo Alto Networks built an advanced high-tech defense ecosystem. The company deploys Cortex XSIAM as its AI-driven security operations platform.
Prisma AIRS protects enterprise AI workloads against emerging adversarial threats. Strata AI agents extend autonomous defense across network security infrastructure.
However, immense scale also brings technological risks. Attackers recently exploited a critical PAN-OS firewall zero-day vulnerability tracked as CVE-2026-0300. The vulnerability allows unauthenticated root access to affected firewall systems.
Furthermore, CISA issued a mandatory mitigation deadline ahead of full patch availability. Palo Alto Networks responded with rapid hotfixes and Prisma Access upgrades. The swift technological response underscores superior engineering capabilities. The CyberArk acquisition further strengthens identity-layer defenses against credential-based attacks.
Science and Patent Analysis
Scientific innovation serves as the bedrock of Palo Alto Networks' technological advantage. The company invests heavily in data science, predictive analytics, and automated machine learning. A comprehensive patent analysis highlights an expanding intellectual property moat.
Palo Alto Networks holds essential patents in zero-trust architecture, advanced telemetry, and cloud-workload isolation. The proprietary technologies prevent rivals from replicating its security platforms.
The company translates theoretical computer science into concrete, commercial security protocols. The deep scientific approach safeguards its market-leading position.
Moreover, Prisma AIRS represents the next frontier in AI workload protection. Protect AI integration extends model-level threat detection across enterprise deployments. Patent portfolios increasingly focus on LLM security, agentic workload defense, and identity-based zero-trust frameworks.
The Financial Verdict
Is Palo Alto Networks overvalued? The market clearly pays a premium for absolute platform dominance.
Catalysts and risks to monitor through Q3 earnings include:
Q3 FY26 revenue beat above $2.94B consensus
NGS ARR exceeding $7.96B (true platformization gauge)
RPO clearing $17.95B (long-term commitment visibility)
CyberArk integration timeline and synergy commentary
CVE-2026-0300 patch deployment progress
White House federal AI cyber directive procurement opportunities
Competitor pressure from CrowdStrike, Zscaler, Fortinet
Memory and processor cost inflation (Zscaler signal)
Stock currently overbought on technical indicators
The company transforms necessary enterprise spending into an unassailable tech monopoly. Tonight's earnings print on June 2, 2026, represents the next major catalyst for PANW shareholders. Investors should watch the NGS ARR and platformization metrics closely for confirmation of the structural thesis through 2027. Long 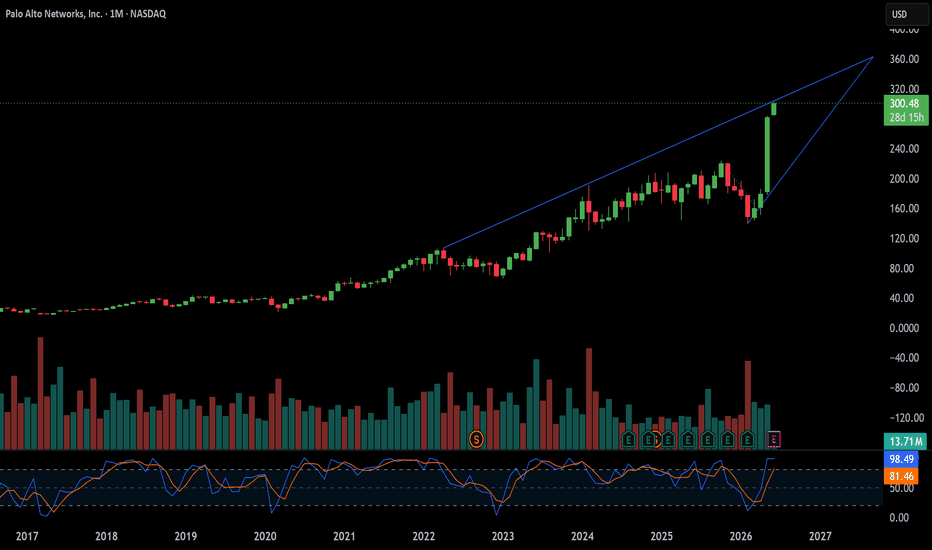
Short 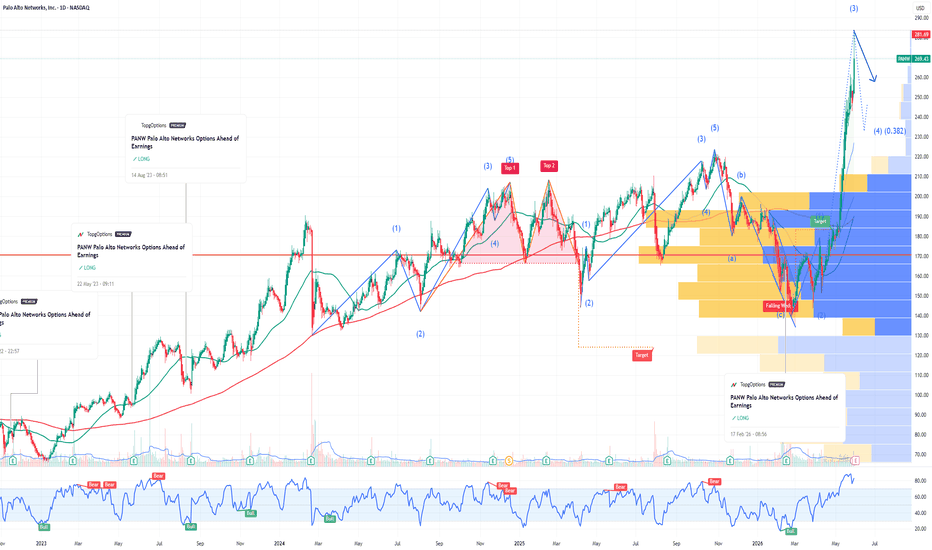
Long 
Breaking: Palo Alto Networks, Inc. (PANW) Is Tanking Hard Shares of Palo Alto Networks, Inc. (NASDAQ: NASDAQ:PANW ) is taking a nosedive after closing down 2% in Tuesdays extended market trading, the company extended dip to Wednesday's premarket market session- tanking over 6%.
A break below the 61.8% Fibonacci retracement level could resort to a selling spree for NASDAQ:PANW shares.
In recent news, Palo Alto Networks (NASDAQ: NASDAQ:PANW ) reported a significant earnings surprise on February 17, 2026 – revenue increased 15.7% compared to the previous year, reaching $2.5 billion, cash flow stayed strong, and the company updated its full-year revenue forecast upwards. So, why is the stock down 8% in after-hours trading?
The reason lies in the guidance. Management reduced its fiscal 2026 adjusted EPS estimate to $3.65–$3.70, down from the earlier forecast of $3.80–$3.90. The cause: costs associated with deals that more than doubled year-over-year to $24 million in the quarter, a direct result of PANW’s $30 billion acquisition spree – especially the $25 billion CyberArk acquisition and the $3.35 billion Chronosphere buyout.
Analyst Summary
According to 36 analysts, the average rating for PANW stock is "Buy." The 12-month stock price target is $222.64, which is an increase of 36.17% from the latest price.
About PANW
Palo Alto Networks, Inc. provides cybersecurity solutions in the Americas, Europe, the Middle East, Africa, the Asia Pacific, and Japan. It offers Prisma Access, a secure access service edge solution; Strata Cloud Manager, a network security management solution; and Prisma AIRS to protect customers’ entire AI ecosystem. Long 
Palo Alto Networks Earnings PreviewPalo Alto Networks Earnings Preview: Options Market Suggests Potential 8% Swing
Palo Alto Networks (PANW) is scheduled to report its fiscal second-quarter earnings after the closing bell on Tuesday, and options market data suggests traders are bracing for significant share price movement in the aftermath of the release. Heading into the report, analysts are projecting continued growth in both revenue and profits for the cybersecurity giant.
Options Pricing Points to Potential Double-Digit Swing
According to options pricing models, traders are anticipating that Palo Alto Networks' stock could move up to 8% in either direction by the end of the trading week following the earnings announcement. To put this in perspective, with the stock closing near $167 on Friday, an 8% upward move would bring shares back above the $180 level. Such a rally would help reverse some of the ground lost since the stock peaked in October of the previous year. Conversely, an 8% decline on the downside could see the stock sink to approximately $153 per share.
This anticipated volatility comes at a critical juncture for the company's stock performance. Although Palo Alto Networks shares have managed to log some gains over the past week, the broader picture for 2026 has been challenging. The company has had a rough start to the year, with shares down approximately 9% year-to-date. This decline is part of a broader trend affecting cybersecurity stocks, which have taken a hit amid a wider rout in the software sector. Currently, the stock sits nearly 25% below its record high reached in October 2025.
Why the Earnings Report Matters to Investors
The upcoming earnings release holds significant weight for investors for several reasons. In recent quarters, Palo Alto Networks has benefited from a tailwind in demand driven by the rapid advancement of artificial intelligence. As AI capabilities grow more sophisticated, they also introduce new and complex security threats, prompting organizations to bolster their cybersecurity defenses. This dynamic has boosted demand for Palo Alto's comprehensive security offerings, and investors will be keen to see if this trend continued into the fiscal second quarter.
Beyond the core financial results, analysts and investors will likely be scrutinizing the report for updates on the company's strategic initiatives, particularly its recent acquisition activity. William Blair analysts noted ahead of the report that investors will be looking for commentary regarding Palo Alto Networks' integration plans and the potential impact of its recent purchases.
Just this past Wednesday, the company announced that it had successfully completed its massive $25 billion acquisition of CyberArk, a deal that significantly expands its identity security and access management capabilities. Additionally, last month, Palo Alto Networks finalized its acquisition of Chronosphere, an AI cybersecurity firm. That deal was originally announced in November alongside the previous quarter's earnings report, and investors will be eager to hear about early progress and synergies.
Key Technical Levels to Watch
From a technical analysis perspective, market participants have identified key levels to monitor following the earnings report and the subsequent price movement. A major support level is seen at $150, representing a potential floor where buying interest could emerge if the stock declines. On the upside, a take-profit target or resistance level is identified near $180. A decisive break above this level could signal a reversal of the stock's recent downward trend and potentially pave the way for a return to its previous highs.
Long 
Long 
Long 
Long 
PANW Earnings Surge Incoming: 180C Call Targeting 300%
# 🛡️ PANW Earnings Options Play – 8/22 AMC
📊 **Market Context**
* Revenue Growth: +15.3% YoY 📈
* Gross Margin: 73.6%, Operating Margin: 9.8%
* Forward EPS: \$7.20 → historically beats 8/8 quarters
* Sector Tailwinds: Cybersecurity demand surging, favorable macro trends
📈 **Options Flow**
* Call volume strong at \$200 strike → institutional bullish
* Put/Call Skew: Slight bearish hedge → anticipating large move
* IV Rank: 70% → favorable premium pricing
📉 **Technical Momentum**
* Trading below 50 & 200 DMA → oversold sentiment
* RSI: 32.78 → oversold, potential sharp reversal
* Support: \$175 | Resistance: \$180 / \$185
---
## 🎯 Trade Setup (Pre-Earnings Call)
* **Instrument**: PANW
* **Direction**: CALL (LONG)
* **Strike**: \$180.00
* **Expiry**: 2025-08-22
* **Entry Price**: \$5.20
* **Profit Target**: \$15.60 (\~300% potential)
* **Stop Loss**: \$2.60 (50% of premium)
* **Size**: 1 contract
* **Confidence**: 75%
* **Entry Timing**: Pre-earnings close
* **Earnings Date/Time**: 8/22 AMC
* **Expected Move**: \$6.50
---
## 🧠 Key Notes & Risk Management
* **Position Sizing**: Limit 2–3% of portfolio
* **Exit Scenarios**:
* Target hit → exit at \$15.60
* Stop triggered → exit at \$2.60
* Time exit → close by 11 AM ET post-earnings if neither condition met
* **Gamma & Volatility Risk**: High around earnings, monitor closely
---
# ⚡ PANW 180C EARNINGS PLAY ⚡
🎯 Entry: \$5.20 → Target: \$15.60
🛑 Stop: \$2.60
📅 Exp: 8/22 AMC
📈 Bias: Moderate Bullish (75%) 🐂
---
📊 **TRADE DETAILS JSON**
```json
{
"instrument": "PANW",
"direction": "call",
"strike": 180.0,
"expiry": "2025-08-22",
"confidence": 75,
"profit_target": 15.60,
"stop_loss": 2.60,
"size": 1,
"entry_price": 5.20,
"entry_timing": "pre_earnings_close",
"earnings_date": "2025-08-22",
"earnings_time": "AMC",
"expected_move": 6.5,
"iv_rank": 0.70,
"signal_publish_time": "2025-08-18 14:05:22 UTC-04:00"
}
```
Long 
Palo Alto Formed Bullish Pattern with 80% Return PotentialPalo Alto Networks (PANW) has technically formed a pattern similar to its 2019–2021 flat period. Back then, after two tops (points 1 and 2) and a sharp bear trap breakdown below the current range (point 3), PANW retested the upper side of the range once more (point 4), which was followed by a massive breakout. From point 3 to the top, PANW rallied 361.8% of the range width, delivering more than a 130% return in about a year and a half.
Currently, PANW appears to be forming a smaller version of that same pattern. Points 1, 2, and 3 seem to be in place, and we are now at point 4. Excluding fundamentals, if the same pattern completes, the technical target could be around $367, an over 80% potential return from current levels. However, it may be wise to wait for a confirmed breakout for validation.
On the fundamental side, PANW appears to be trading at a high valuation compared to both its historical averages and sector peers. The 2-year forward P/E average is 51.2x, while the current forward P/E sits at 55.5x not drastically higher, but still elevated. That said, Palo Alto is expected to post 14.29% year-over-year revenue growth with a strong operating margin in the upcoming earnings report. Long