GBPUSD H8 Institutional Liquidity Levels Bulls/Bears▪️ My read: Coiled just under a 33-retest lid (7.2/10 STRONG at 1.35549–1.35669) with only moderate supply overhead but VERY-STRONG demand stacked below — a classic grab-and-reverse. The up-push into 1.35549–1.35669 / toward the 1.36000 weak-resistance liquidity is bait to run buy-side stops before the real move rotates down into the 1.34438–1.34710 demand, where a POWER 7/10 liquidity cluster and 42 retests make it the highest-value long in the near range. Reclaim and hold above 1.36000 flips bias bullish toward fresh highs. Edges pay, the middle chops.
▪️ GBPUSD is trading near 1.3540, coiled just beneath a ★★★ 7.2/10 STRONG RESISTANCE (33 retests) at 1.35549–1.35669 that caps price here, with resting liquidity toward 1.35669. Above that, a ★ 4.6/10 WEAK RESISTANCE (25 retests) at 1.35800–1.36000 is the upper cap. Below, the floor is heavy: a ★★★★ 8.4/10 VERY STRONG SUPPORT (42 retests) at 1.34438–1.34710 — overlapping a Bull Liquidity Cluster — anchors the nearest demand, with deeper POWER 9/10 clusters and a second ★★★★ 8.4/10 pool below it. Supply above is thin; demand below is loaded.
▪️ Primary outlook: up-sweep first, then rotation down into demand. The yellow paths run price up through the 7.2/10 lid → toward 1.35669 / the 1.35800–1.36000 weak resistance to tag overhead buy-side liquidity. The red paths are the dominant rotation back down — reject the lid, roll down into the 8.4/10 VERY STRONG SUPPORT + POWER 7/10 cluster at 1.34438–1.34710 where the high-value long sits and the bounce is expected.
🔴 CEILING — overhead supply & sell-side liquidity
▪️ 1.35549–1.35669 — ★★★ 7.2/10 STRONG RESISTANCE · 33 retests · immediate lid, price pressing into it now, liquidity resting into 1.35669 (~+13 to +25 pips)
▪️ 1.35800–1.36000 — ★ 4.6/10 WEAK RESISTANCE · 25 retests · upper cap / thin ceiling, reclaim-and-hold flips bias bullish (~+38 to +58 pips)
🟢 FLOOR — demand & buy-side liquidity
▪️ 1.34438–1.34710 — ★★★★ 8.4/10 VERY STRONG SUPPORT · 42 retests · primary reversal-long, overlaps Bull Liquidity Cluster · nearest high-value zone (~-71 to -98 pips)
▪️ 1.33700–1.33850 — ★ 5.9/10 WEAK SUPPORT · 53 retests · overlaps Bull Liquidity Cluster · deeper magnet (~-157 to -172 pips)
▪️ 1.33100–1.33250 — ★★★ 7.1/10 STRONG SUPPORT · 28 retests · overlaps Bull Liquidity Cluster · deeper high-value pool (~-217 to -232 pips)
▪️ 1.32440–1.32680 — ★★★★ 8.4/10 VERY STRONG SUPPORT · 40 retests · deepest floor / range low (~-274 to -298 pips)
▪️ ORDER FLOW / ZONE MAP
▪️ Overhead: 7.2/10 lid (1.35549–1.35669) → liquidity into 1.35669 → 4.6/10 weak (1.35800–1.36000). Supply thins out fast above the lid; the up-sweep is built to run stops into that overhead pool before turning.
▪️ Below: 8.4/10 VERY STRONG + POWER 7/10 cluster (1.34438–1.34710) → 5.9/10 weak + POWER 9/10 cluster (1.33700–1.33850) → 7.1/10 strong + POWER 9/10 cluster (1.33100–1.33250) → 8.4/10 VERY STRONG (1.32440–1.32680). The demand stack is the heaviest structure on the board — three liquidity clusters and two very-strong pools cushioning every dip.
🔍 SCENARIO PATH
▪️ Up leg first (liquidity grab): push from ~1.3540 through the 7.2/10 lid → toward 1.35669 / the 1.35800–1.36000 weak resistance to tag overhead buy-side liquidity.
▪️ Reversal: reject the lid, print a lower high, roll back down.
▪️ Down rotation: drive into the 8.4/10 VERY STRONG SUPPORT + POWER 7/10 cluster at 1.34438–1.34710 where the primary long fires.
▪️ Bounce / reversal: lift off 1.34438–1.34710 back toward 1.35000 and the 7.2/10 lid.
▪️ Deeper flush (if 1.34438 fails): the POWER 9/10 clusters at 1.33700–1.33850 and 1.33100–1.33250 become the higher-value magnets, with the 8.4/10 at 1.32440–1.32680 the last floor.
▪️ Bull invalidation / continuation: a clean reclaim and hold above 1.36000 negates the rotation and opens fresh highs.
🔒 Levels and paths from the zone model. No signals, no repaint — a scenario, not a promise.
▪️ ProjectSyndicate Levels Desk — weekly S/R & liquidity zones for FX, XAUUSD, GBPUSD, NVDA, NQ, ES & GC. Subscribe to stay up to date.
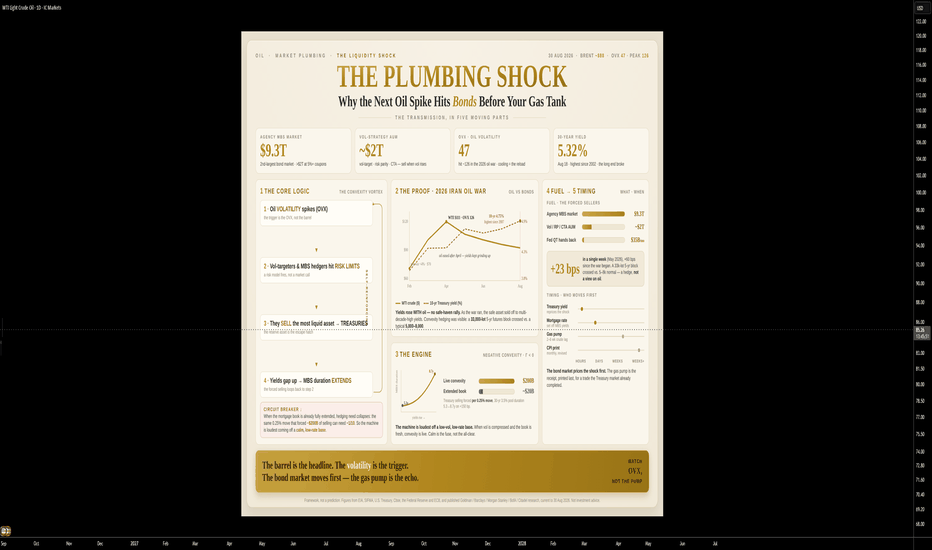
#GBPUSD #Forex #Cable #Trading When Oil Turns Violent, Two Machines Dump Your Bonds First.◼️ EXECUTIVE SUMMARY
When oil spikes, everyone braces for higher pump prices and inflation. That story is real, but it is slow and it is second. The first hit lands in the bond market, within hours, and it is not driven by oil traders. It is driven by automated sellers who have no view on oil at all. The trigger is oil VOLATILITY, not the price. When oil gets violent, the two biggest rules-based selling machines in fixed income are forced to dump US Treasuries at the same moment, pushing yields up and repricing your mortgage long before gas moves. This is a plumbing shock, not an inflation print.
◼️ THE TRIGGER: VOLATILITY, NOT PRICE
The machines size their selling off how fast oil is moving, measured by the OVX (Cboe Crude Oil Volatility Index), not the level of Brent. OVX ran from the high-20s to about 126 in the 2026 oil war, against a record close of 325 in April 2020. A smooth 40% rally barely moves them. A violent one forces their hand.
◼️ THE TWO MACHINES
Machine one: the ~$9.3T agency mortgage-bond market. As yields rise, refinancing slows, mortgages last longer, and the bonds' duration extends. To stay hedged, holders must SELL Treasuries into a falling market, which pushes yields higher, which extends duration further. A self-reinforcing loop called negative convexity.
Machine two: ~$2T of volatility-targeting and risk-parity funds. When measured volatility jumps, their risk model breaches its limit and forces mechanical de-leveraging. They sell the most liquid thing they own, Treasuries, regardless of value.
Neither has an opinion on oil, inflation, or bonds. Both are wired to sell the same asset at the same moment a shock arrives.
◼️ THE PROOF (2026 OIL WAR)
As war drove WTI from ~$70 to $111, the safe asset did NOT rally. It sold off. The 30-year yield crossed 5% for the first time since 2007, then hit ~5.33%, the highest since 2002. Convexity hedging was visible in the tape: a 33,000-contract 5-year futures block versus a typical 5,000 to 8,000. Oil eased after April. Yields kept grinding up.
◼️ THE ORDER OF ARRIVAL
Treasury yield: hours. Mortgage rate: days. Gas pump: 2 to 6 weeks. CPI print: weeks and revised. Everyone watches the last two boxes. The damage is done in the first two.
◼️ THE EDGE
The machine is loudest coming off a calm, low-rate base, when convexity is live and funds have re-levered into the quiet. Calm is not the all-clear, it is the wind-up. Watch the OVX, not the pump.  Long
Nvidia Reports Tonight: A $92B Beat Is Already Priced. 🟢 NVDA Q2 FY27 — Aug 26, after close
💵 Stock ~$214 · ~$5.1T cap · Strong Buy · avg target $305, +44%
📊 Street: EPS ~$2.09 on ~$92.2B rev, +97% YoY · guide was $91B ±2%
🎯 What matters is the Q3 guide, needs ~$100B, plus gross margin holding ~75%
📉 Sell-the-news risk: down day-after 4 quarters straight, 6 of last 8, despite beating every time
⏳ But the drift wins: +0.3% median next day vs +11% a quarter, +88% a year
🌀 Options imply ~±5%, about a $286B swing
🇨🇳 China is free upside. H200 sits outside guidance; +$4–10B/yr if it flows
🚀 Bull: Blackwell sold out, Rubin ramping, hyperscaler capex $475–600B+
⚠️ Bear: "circular financing", $540–750B of deals backing its own customers, CDS spiked, ASICs from Google TPU, Broadcom, OpenAI's "Jalapeño"
🧭 My Read
I expect a clean beat, and probably a reflex dip anyway, because that is how this stock has traded for a year. What I care about is the Q3 guide and the margin line, not the headline. If the guide clears ~$100B and gross margin holds ~75%, I treat the knee-jerk sell-off as a gift. If margin slips below ~74%, or the guide only matches instead of accelerating, the bears finally have something real to hold. My plan is simple: don't chase the print, let the reaction set the level, and add on strength only once the guide and margin confirm. After tonight, the next tell is Rubin's timing and whether China licenses ever turn into revenue. Not advice.
The Setup, The Reaction Record & Ranked Catalysts
As of Aug 25, 2026 close. Stock ~$213.70 · market cap ~$5.1T · consensus Strong Buy, 58 of 61 Buy/Strong Buy, 2 Hold, 1 Strong Sell · avg 12-mo target $305.41, +44%. NVIDIA reports fiscal Q2 2027, quarter ended July 26, 2026, on Wednesday, Aug. 26, after the close. Street wants adj. non-GAAP EPS ~$2.09 on ~$92.2B revenue, +97% YoY, versus Q1's non-GAAP $1.87, a clean +12% QoQ on the comparable basis. Options price a ~5% move either way, about $286B. Educational, not investment advice.
1) The setup: what the Street actually needs
The headline numbers are almost a formality. NVIDIA guided Q2 to ~$91.0B ±2% at ~75% gross margin, and the beat record is near flawless. The reaction rides on four things behind the print.
The Q3 FY27 guide is the single biggest swing factor. After guiding Q2 to $91B, the Street wants a number pushing toward $100B to keep the acceleration story alive.
Gross margin durability at ~75%. Holding it rebuts the argument that custom silicon is eating the pricing.
China commentary. NVIDIA left China Data Center sales out of its ~$91B guidance, so any H200 flow is upside, not baked in.
Bookings, backlog, and the Blackwell-Ultra to Rubin cadence. Visibility is the valuation.
2) 📉 The reaction record: the "expectations premium"
Every headline is fixated here, for good reason. NVIDIA has pulled back the day after reporting in all four of the last quarters, despite meeting or beating on EPS, revenue and guidance. Zoom out and it's fallen the day after in six of the last eight.
Quarter (fiscal) Reported Revenue YoY Result Next-day move
Q2 FY25 Aug 2024 $30.0B +122% Beat −6.4%
Q3 FY25 Nov 2024 $35.1B +94% Beat +0.5%
Q4 FY25 Feb 2025 $39.3B +78% Beat −8.5%
Q1 FY26 May 2025 $44.1B +69% Beat +3.2%
Q2 FY26 Aug 2025 $46.7B +56% Beat −0.8%
Q3 FY26 Nov 2025 $57.0B +62% Beat −3.2%
Q4 FY26 Feb 2026 $68.1B +73% Beat −5.5%
Q1 FY27 May 2026 $81.6B +85% Beat −1.8%
Every bar a record, and the stock still sold off. Over the last four quarters NVDA has averaged −2.8% the day after and −5.3% over two days.
But the day is noise. Since 2016, NVIDIA's median post-earnings return is just +0.3% after one day and +0.4% after a month, but +11.1% over a quarter and +87.6% over a year, with the win rate climbing from 55% at one day to 78% at one quarter to 84% at one year. The first-day reaction is a coin flip; the longer hold has not been.
📝 Bottom line
The tension isn't demand. Blackwell is sold out and the capex cycle is still expanding. It's the bar. A ~97% revenue jump is already consensus, so the reaction lives in the Q3 guide, the margin line, and whether Jensen can quiet the circular-financing narrative that only got louder once the $105B OpenAI guarantee was signed on Aug 17. After tonight, the next decisive catalyst is the Rubin ramp cadence and whether China licenses finally convert to revenue. Not investment advice.  Long

USDCHF H4 Institutional Liquidity Levels Bulls/Bears▪️ My read: Coiled into a 54-retest lid with VERY-STRONG supply above and VERY-STRONG demand below — a classic grab-and-reverse setup. The up-push into 0.80700–0.80800 / toward the 0.80961 liquidity is bait to run buy-side stops before the real move rotates down into the 0.79363–0.79480 demand, where 55 retests make it the highest-value long on the chart. Reclaim and hold above 0.80800 flips bias bullish toward the 0.81300–0.81400 range high. Edges pay, the middle chops.
▪️ USDCHF is trading near 0.8030, pressing up into a ★★★ 7.1/10 STRONG RESISTANCE (54 retests) that caps price right here. Overhead, a ★★★★ 8.3/10 VERY STRONG RESISTANCE (40 retests) at 0.80700–0.80800 is the real sell wall, with resting liquidity at 0.80961 just above it. Below, a ★★★★ 8.1/10 VERY STRONG SUPPORT (55 retests) at 0.79363–0.79480 anchors the floor, cushioned only thinly by a 4.7/10 weak shelf at 0.79760–0.79970. Price is coiled between two loaded VERY-STRONG pools with the near-term push aimed up.
▪️ Primary outlook: up-sweep first, then rotation down into demand. The yellow paths run price up through the 7.1/10 lid → the 8.3/10 wall at 0.80700–0.80800 → toward 0.80961 to tag overhead sell-side liquidity. The red paths are the dominant rotation back down — reject the wall, roll through the 4.7/10 weak shelf, into the 8.1/10 VERY STRONG SUPPORT at 0.79363–0.79480 where the high-value long sits and the bounce is expected.
🔴 CEILING — overhead supply & sell-side liquidity
▪️ 0.80300–0.80430 — ★★★ 7.1/10 STRONG RESISTANCE · 54 retests · immediate lid, price pressing into it now
▪️ 0.80700–0.80800 — ★★★★ 8.3/10 VERY STRONG RESISTANCE · 40 retests · the up-sweep magnet / where the reversal is expected to originate (~+40–50 pips), liquidity resting into 0.80961
▪️ 0.81300–0.81400 — ★★★ 7.3/10 STRONG RESISTANCE · 12 retests · range high / deeper target only if bulls reclaim (~+100 pips)
🟢 FLOOR — demand & buy-side liquidity
▪️ 0.79760–0.79970 — ★ 4.7/10 WEAK SUPPORT · 51 retests · thin shelf beneath price / first catch (~-33 to -54 pips)
▪️ 0.79363–0.79480 — ★★★★ 8.1/10 VERY STRONG SUPPORT · 55 retests · primary reversal-long / deep magnet, highest-value zone on the board (~-82 to -94 pips)
▪️ ORDER FLOW / ZONE MAP
▪️ Overhead: 7.1/10 lid (0.80300–0.80430) → 8.3/10 VERY STRONG (0.80700–0.80800) → sell-side liquidity into 0.80961. Price is leaning into the first lid; the heavy supply sits ~40–50 pips higher — exactly the pool an up-sweep is built to run to grab resting buy-stops before it turns.
▪️ Below: 4.7/10 weak shelf (0.79760–0.79970) → 8.1/10 VERY STRONG (0.79363–0.79480). The weak shelf offers little defense; the 8.1/10 pool — 55 retests, the strongest zone on the chart — is the deepest, highest-value reversal zone.
🔍 SCENARIO PATH
▪️ Up leg first (liquidity grab): push from ~0.8030 through the 7.1/10 lid → into the 8.3/10 supply at 0.80700–0.80800, extending toward 0.80961 to tag overhead sell-side liquidity.
▪️ Reversal: reject the 8.3/10 wall, print a lower high, roll back below the 0.79760–0.79970 weak shelf.
▪️ Down rotation: drive into the 8.1/10 VERY STRONG SUPPORT at 0.79363–0.79480 where the primary long fires.
▪️ Bounce / reversal: lift off 0.79363–0.79480 back up toward 0.80000–0.80100 and the 7.1/10 lid.
▪️ Bull invalidation / continuation: a clean reclaim and hold above 0.80800 negates the rotation and opens the 0.81300–0.81400 range high.
🔒 Levels and paths from the zone model. No signals, no repaint — a scenario, not a promise.
▪️ ProjectSyndicate Levels Desk — weekly S/R & liquidity zones for FX, XAUUSD, GBPUSD, NVDA, NQ, ES & GC. Subscribe to stay up to date.
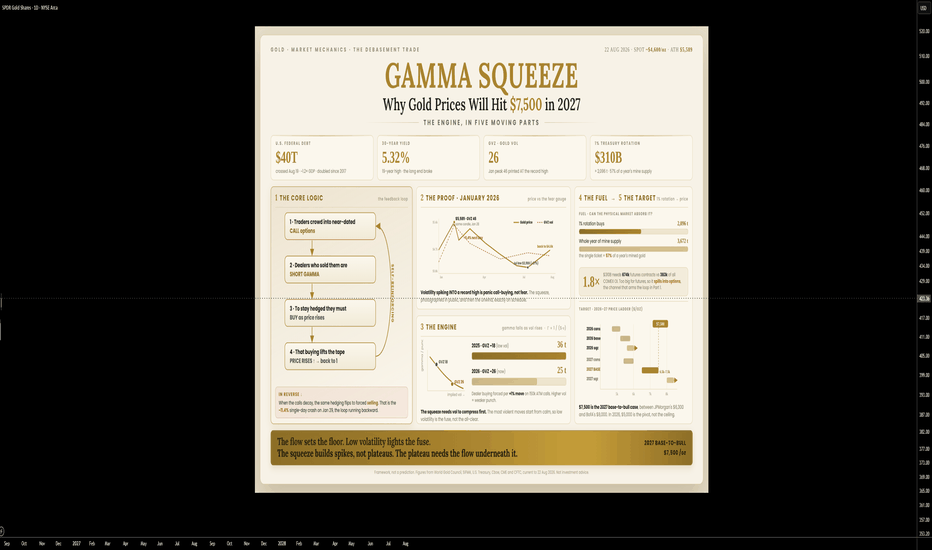
#USDCHF #Forex #Swissy #Trading GAMMA SQUEEZE: Why Gold Prices Will Hit $7,500 in 2027⬛ GAMMA SQUEEZE: Why Gold Prices Will Hit $7,500 in 2027
2026 update, data as of August 22, 2026
◾ Bottom line
Last year's version of this note made one call. A 1% rotation out of U.S. Treasuries could carry gold to $5,000 an ounce, and in a squeeze, past it.
That call got tested in the real world. It passed.
Gold printed an intraday record of $5,589.38 on January 28, 2026 (settlement peak $5,602.23 the next day), the exact self-feeding, options-fed blow-off the framework described. Then it did the other thing the framework warned about. It couldn't hold. The metal dropped 11.4% the very next session and bled more than 27% into a mid-July low near $3,986.
So the argument isn't "can gold reach $5,000" anymore. It got there.
The live questions now:
▪️ Can it get back and stay there? (2026 year-end)
▪️ Does the $7,500 target still hold? (2027)
▪️ What turns steady flow into a squeeze, and is that setup rebuilding right now?
Short version. With U.S. debt through $40 trillion, the 30-year yield at a 19-year high, and the Treasury openly stepping in to cap the long end, the flow case is stronger than it was a year ago. $5,000 is the pivot now, not the ceiling. $7,500 has moved from a 2026 spike-only number to a credible 2027 base-to-bull target. The gamma mechanism is real and proven. What it manufactures is spikes, not plateaus. The plateau needs the flow underneath it.
◾ Executive summary
▪️ The rotation is bigger in dollars now. Marketable U.S. Treasuries have grown to roughly $31 trillion (SIFMA counted $30.3T at Q4 2025, up 7% on the year). A 1% rotation is now about $310B of fresh gold demand, up from the $278B in last year's note.
▪️ The fiscal backdrop is the whole story. Gross federal debt crossed $40 trillion on August 19, 2026, roughly 1.2 times GDP, doubled since 2017. Net interest runs north of $1 trillion a year, more than the country spends on defense. Call it the debasement trade. It's what's moving the tape in August.
▪️ What $310B buys at today's price (~$4,600): about 67.4M ounces, near 2,096 tonnes. At $5,000 it buys ~1,928 t. At $7,500, ~1,286 t. For scale, 2025 mine supply ran ~3,672 t and total supply including recycling hit a record 5,002 t. So one 1% ticket equals ~57% of a year's mine output, or ~42% of all new supply.
▪️ The market is deeper, and so is the pressure. Global gold turnover hit a record ~$488B/day in H1 2026, up from ~$290B in 2025. A $310B program is now about 0.6 of a single day's turnover, not a full day. That cuts both ways. More depth to soak up flow, but this flow runs one direction and it's structural, not churn.
▪️ The squeeze plumbing is loaded. GVZ, the 30-day gold implied vol, sits near 26, down from the January panic peak of 46 but still well above 2025's ~18. COMEX net-long positioning was 538 t at end-June, the highest since January. And the options tail looks wild. There's real open interest in December 2026 calls struck at $19,000 to $20,000.
▪️ Updated targets (a framework, not a prophecy):
Scenario Assumption 2026 year-end 2027
Conservative Flow spread out, mostly physical/ETF/CB $4,700 – $5,200 $5,400 – $6,000
Base case Flow + partial options reflexivity $5,200 – $5,800 (retest ATH) $6,500 – $7,500
Squeeze / overshoot Short-dated call concentration, dealers short gamma new ATH > $5,600 (brief) episodic > $8,000
These bands sit inside the mainstream range (Goldman $5,400 to $5,600 for 2027, JPMorgan $6,300, Bank of America's extreme-demand case $8,000). The thesis stopped being a fringe call. The banks caught up to it.
◾ What changed since 2025: the squeeze already happened
Theory turned into evidence this year. Worth walking through slowly.
The setup (late 2025 into January 2026). Gold entered the year already running, closed $5,318 on Jan 29, printed an intraday high of $5,589.38 on Jan 28. Textbook.
The giveaway. On Jan 29 the gold volatility index closed at 46, a crisis-grade reading, and it printed that at a price record. Read it twice. Volatility spiking into a new high isn't fear buying puts. It's panic buying calls, the exact signature of a gamma squeeze, where the dealers who are short gamma get forced to chase price higher.
The unwind. Next session, gold fell 11.4%, the biggest single-day drop of the year. That's a negative-gamma flip on the way down. The same hedging that fed the rally reverses and feeds the fall.
The grind. What came next was slower and meaner than a crash. Five months of lower highs from March into July as ETF flows dried up (North America logged its weakest first half since 2013), the U.S. and Iran conflict pushed energy inflation higher, the Fed under new chair Kevin Warsh pulled its 2026 rate cuts off the table, and Goldman trimmed its target from $5,400 to $4,900. Gold bottomed near $3,986 on July 16, more than 27% down from the peak.
The lesson, and last year's note called it in advance:
"Squeeze/overshoot window… episodic spikes >$8,000/oz possible, but hard to sustain without continued flow."
The squeeze is real. The overshoot is real. And it mean-reverts unless structural flow keeps turning up. January ran ahead of the flow, the ETF and Western money then faded, price reverted. That's the model, start to finish, proven on live tape.
Now the flow is rebuilding. Gold has ripped more than 4% in a week to ~$4,600, its best level since May, clearing every major moving average, on a single-day ETF inflow of 18 tonnes on Aug 20, the biggest in nearly a year. This time the catalyst is structural. A $40T debt pile, and a bond market coming apart in slow motion.
◾ The macro backdrop: $40 trillion, a 19-year yield high, and a Treasury that blinked
This is the fuel line running into the gold thesis.
▪️ $40 trillion. Gross federal debt crossed the mark on Aug 19, 2026, months earlier than forecast, partly on revenue lost to invalidated tariffs. It's about 1.2 times GDP, a ratio last touched in the Second World War, and it's doubled since 2017.
▪️ Interest is the line item that hurts. Net interest now tops $1 trillion a year, more than the defense budget. Around 19% of federal tax revenue goes to servicing the debt, and the CBO path has it at $43.3 trillion by FY2028. That's fiscal dominance, and it's gold-bullish by construction.
▪️ The long end broke. The 30-year Treasury yield touched 5.32% on Aug 18, a 19-year high, during a buyers' strike that began in late June. The 10-year sits near 4.65%. Rising nominal long yields usually work against gold, which is what makes the next point matter.
▪️ The Treasury blinked. On Aug 19, Bessent's Treasury said it would at least double its long-end liquidity-support buybacks (the 10 to 30 year sector) from $2B to $4B per operation (Sept 9 through Nov 4). Yields fell, the dollar softened, gold jumped more than 4% and held. Analysts at CFR, ING and TD read it the same way. A verbal intervention. A warning shot.
▪️ The detail most readers skip. In the operation right before the announcement, Treasury offered to buy about $20B and dealers handed over only about $2B, the smallest volume of offers all year. The selling queue was shrinking, not flooding. A desk buried in sellers raises its bid because it has to. This desk had almost none, and raised the cap anyway. Read that as intent, not reflex, a decision to lean on the long end. For a gold investor that's the whole thesis in one data point. Washington is now openly managing its own borrowing cost, which is a polite way of saying financial repression. Repressed real yields sitting on top of $40T of debt is the structural bid under bullion.
Even UBS lands in the same place off the same tape. Rising global debt plus a soft dollar, its commodity desk says, should lift gold toward $5,400 over the next twelve months.
◾ Sizing a 1% Treasury to gold rotation (updated math)
Treasury base: ~$31 trillion marketable (SIFMA: $30.3T at Q4 2025, up 7% y/y, higher into mid-2026). 1% is about $310B. (Context: gross debt is $40T, but roughly $8T of that is intragovernmental and non-tradable, so the marketable stock is the honest denominator.)
What $310B buys:
Gold price Ounces Tonnes ≈ COMEX contracts (100 oz)
$4,600 (today) 67.4M 2,096 t 674k
$5,000 62.0M 1,928 t 620k
$5,600 (ATH zone) 55.4M 1,722 t 554k
$7,500 41.3M 1,286 t 413k
Three lenses on how big that is.
① Supply lens. At today's price, 2,096 t is ~57% of a full year of mine output (3,672 t), or ~42% of all 2025 supply (the 5,002 t record). You can't conjure that metal. It has to be bid away from people who already hold it, and price is the only lever that does the bidding.
② Turnover lens. Global gold turnover now runs ~$488B/day (an H1 2026 record, up 68% from 2025's ~$290B). A $310B program is about 0.6 of one day's turnover. Here's the honest bearish caveat. The market is deeper than it was in 2025, so a given dollar of flow moves price less per unit than the old math assumed. But turnover is churn, not one-way absorptive depth. A sustained, single-side rotation still piles up.
③ Demand-value lens. H1 2026 total demand value was a record $380B. A $310B ticket is about 82% of an entire half-year's demand dropped into the system, roughly 1.6 times a normal quarter. That's a real shock to the marginal price.
④ Futures-capacity check. COMEX gold futures open interest is only about 383k contracts (July 2026). At $4,600, $310B works out to ~674k contracts, near 1.8 times all outstanding OI. You can't push that through futures quickly without violent repricing. Even at $7,500 it's ~413k contracts, roughly 1.08 times OI. And that's exactly why the flow, once it routes through options, turns reflexive.
◾ The gamma-squeeze engine (updated for today's vol)
One-line definition. When call-buying piles into near-dated, near-the-money strikes, the dealers who are short gamma have to buy futures as price rises (and sell as it falls) to stay hedged. That feedback speeds the move, up and down.
The powder keg is still there. On top of a large listed options stack, positioning is stretched (538 t net long at end-June) and the speculative tail is something else. There's real open interest sitting in Dec-2026 calls at the $19,000 and $20,000 strikes, a lottery ticket of a macro bet, but a signal of the appetite for convexity.
The non-obvious 2026 wrinkle: higher vol has muffled the per-contract punch.
Black-Scholes gamma for a 30-day ATM option is Γ ≈ φ(0) / (S·σ·√T). Gamma sits inverse to implied vol. With GVZ near 26 today versus ~18 in 2025, each call delivers less hedging pressure per 1% move:
2025 (σ≈18%, S≈$3,500) 2026 (σ≈26%, S≈$4,600)
Gamma (per $) 0.00221 0.00116
Δdelta per oz on a +1% pop 0.077 0.054
Dealer hedge buy per 1% pop, on 150k ATM calls ~36 t ~25 t
What that means. At today's higher implied vol, the same wall of call open interest forces roughly 30% less buying than it did in January. To rebuild a January-scale squeeze from here you need one of two things. More call concentration, or vol to compress first.
And that's the bullish read, not the bearish one. The most violent squeezes start from low vol. When GVZ compresses toward the high teens and a catalyst lands (a soft CPI, a Warsh pivot, a failed 30-year auction, another buyback surprise), gamma per contract jumps, and a call wave hitting a short-gamma dealer book goes off. January began from complacency. So will the next one. Watch the combination: GVZ compressing, call skew steepening, a macro trigger.
The reflexive multiplier, sized. If even 20% to 30% of the $310B rotation shows up as short-dated calls, a 3% to 5% grind over a few days can force 100 to 200 t of extra dealer buying, on top of the flow itself, against a market that mines only ~10 t a day. That's how $5,000 becomes $5,600 becomes a wick to a new record inside a week. It's also how it round-trips just as fast once the calls decay.
◾ Price-target framework: 2026 year-end and 2027
Think in layers. (A) base flow impact, plus (B) options reflexivity, plus (C) second-round effects (central banks, dollar, short-covering).
(A) Flow-only, calibrated to 2020. The 2020 anchor (877 t of ETF inflow against a roughly 36% price rise) implies, on naive proportionality, that 1,700 to 2,100 t maps to +70% to +86%. Off a $4,600 base that's a nominal $7,850 to $8,560. It overstates the case, though. Today's market is about 1.7 times deeper by turnover, and 2020 had its own tailwinds (zero rates, QE, a pandemic). Haircut the pass-through to something realistic and flow-only lands around +15% to +35%, so $5,300 to $6,200.
(B) Options overlay. Add another 10% to 20% while a squeeze is running. The operative words being while it runs.
(C) Second-round bid. Central banks are structural, price-insensitive buyers. They took 288.9 t in Q2 2026 alone (up 62% y/y, a record second quarter), and they bought into falling prices. They hold more than 38,000 t (~26% of global reserves) and they fade dips, not rallies. Add a soft dollar and a Fed that's run out of hawkish room, and the floor keeps ratcheting higher.
Putting it together:
🔹 2026 year-end ▪️ Conservative: $4,700 to $5,200 ▪️ Base: $5,200 to $5,800 (a retest of the January record zone) ▪️ Squeeze: a brief new record above $5,600 → $5,000 is the pivot now, not the target. Getting back above it is a when, not an if, on this backdrop.
🔹 2027 ▪️ Conservative: $5,400 to $6,000 ▪️ Base: $6,500 to $7,500 ▪️ Squeeze/overshoot: episodic, above $8,000
◾ So, does $7,500 still make sense?
Yes. It's just moved houses.
In last year's note, $7,500 was a 2026 base-to-squeeze number. Two things changed.
1) The starting line moved up. We began 2025 near $3,500. We sit near $4,600 today and have already touched $5,600. A move to $7,500 from here is +63%, not the +110% it once meant. A far more ordinary ask.
2) The consensus came to meet it. $7,500 no longer sits on the fringe: ▪️ JPMorgan: $6,000 (Q4 2026), then $6,300 (2027) ▪️ Goldman Sachs: $5,400 to $5,600 (2027) ▪️ UBS / Deutsche / Wells Fargo: $5,400 / $6,000 / $6,100 to $6,300 ▪️ Bank of America (Widmer), extreme-demand case: $8,000 by 2027, citing Fed-leadership uncertainty, structural fiscal deficits, and historically low investor gold allocations
$7,500 threads right between JPMorgan's base and BofA's bull. As a 2027 base-to-bull target it's mainstream-plus now, not heroic. As a 2026 number it's a squeeze print, not a year-end base case.
The honest caveat. Sustained $7,500 needs the flow to keep coming. Central banks staying aggressive, Western ETF money re-engaging (it only just restarted, Aug 20), the fiscal and repression story intact. The gamma engine can spike price through $7,500 on a call wave. Only the structural bid can hold it there.
◾ Risks and reality checks (what breaks the trade)
▪️ Vol runs both ways. The gamma that squeezes up unwinds down just as hard. January's 11.4% day is the warning. Long through short-dated calls means you're also short the round-trip.
▪️ The flow can fade again. H1 2026 proved it. ETF outflows, a hawkish Fed and a firm dollar produced a 27% drawdown even with record central-bank buying. Western demand is fickle.
▪️ A credibly hawkish Fed. Warsh's board is split (a 9-3 hold in July, with three dissents for a hike). If energy inflation forces real hikes, gold's opportunity-cost headwind comes back hard.
▪️ Demand destruction is real. Q2 jewelry fell to ~278 t, one of the weakest quarters on record, and recycling climbs as price climbs. Both cushion the extremes and cap how long a print above ~$7k lasts without fresh flow.
▪️ The buyback might work. If the Treasury's intervention calms the long end and real yields drift down in an orderly way, you lose the crisis premium even while you keep the debasement bid. A slower, quieter path.
▪️ Timing matters most of all. A slow, programmatic 1% rotation spreads the impact and gets absorbed by a $488B/day market. A front-loaded, options-routed rotation is what throws the wicks above $8,000. Same fuel, very different fireworks, depending on when it lands.
◾ References
▪️ Price action: USAGOLD, QZ, Investing.com (Aug 21, 2026): spot ~$4,590 to $4,601, +4.2% on the week, highest since May 15; record $5,602.23 (Jan 29) and $5,589.38 intraday (Jan 28); 2026 low ~$3,986 (Jul 16); drawdown over 27%. ▪️ Debt: Washington Post, CNN, Axios, Al Jazeera, Reason Foundation (Aug 19 to 20, 2026): gross federal debt over $40T, ~1.2× GDP, net interest over $1T/yr and above defense, CBO $43.3T by FY2028. ▪️ Treasuries outstanding: SIFMA Research Quarterly: UST $30.3T (Q4 2025, up 7% y/y). ▪️ Bond market and buyback: U.S. Treasury press release SB0607; CNBC, Quartz, CFR, Axios, FXStreet (Aug 19 to 21, 2026): 30-yr 5.32% (19-yr high), buyback cap $2B to $4B (Sep 9 to Nov 4), "$20B offered, $2B lifted." ▪️ Demand and central banks: WGC Gold Demand Trends Q2 2026: Q2 total demand 1,269 t; H1 2,522 t; record H1 value $380B; CB net buying Q2 288.9 t (up 62% y/y, record Q2); H1 CB net 345 t; PBoC 2,346 t. ▪️ ETF flows and turnover: WGC Gold ETF Flows (Jun to Aug 2026): holdings ~4,068 t (peak 4,176 t Feb 27); H1 up 18 t; record turnover $488B/day; ETF ADV $12.0B/day (up 73% y/y). ▪️ Supply and stocks: WGC: 2025 total supply 5,002 t (record); mine 3,672 t; above-ground stock 219,891 t (~$31T end-2025); CBs hold over 38,000 t (~26% of reserves). ▪️ Volatility: Cboe/FRED GVZ: ~26 (Aug 2026), peak 46.02 (Jan 29), ~37 (Apr). ▪️ Positioning and options tail: CFTC via WGC: 538 t net long (end-June); CME/Bloomberg: Dec-2026 call OI clustered $19,000 to $20,000. ▪️ Bank forecasts: Goldman, JPMorgan, UBS, Wells Fargo, Deutsche, Bank of America, Reuters analyst poll (2026 median ~$4,900).
This note is for information and education only. It isn't investment advice, a recommendation, or a solicitation to buy, sell, or hold any security. Gold is highly sensitive to macro and geopolitical shocks that can move prices sharply and without warning, as 2026 has repeatedly shown. Do your own research and consult a licensed professional before making any investment decision.  Long
USDSGD Institutional Liquidity Levels Bulls/BearsTwo charts, one story — with a fork in the timing. The levels chart says price is parked; the fractal chart says it drops first. Both land in the same spot: down, then up. The only argument is how far down before the turn.
Option A — Levels (Chart 1): 1.2766 is sitting inside an 8.3/10 VERY STRONG shelf. Real demand doesn't show up until the POWER-6 Bull Cluster at 1.2656–1.2668. Shallow sweep → reclaim → rotate back up into the stacked bear liquidity at 1.2880 → 1.2960.
Option B — Fractal (Chart 2): the descending 1-2-3 isn't done. Trendline touch #3 projects ~1.2480 — sub-1.25 — landing October 2026. Same reversal, deeper entry. Red arrows flush it, yellow arrows carry it back.
Reconcile: B is just A on a longer leash. The sweep doesn't stop at 1.2656 — it runs the trendline to 1.2480 before the identical bounce fires. Hold 1.2656 and it's Option A. Lose it, and the fractal owns the tape into Q4.
▪️ My read: A lower-before-higher map, not a collapse thesis. USDSGD at 1.2766 is pinned inside an 8.3/10 shelf with soft ground beneath it — a WEAK 4.8/10 at 1.2695, then a POWER-6 Bull Cluster at 1.2656–1.2668. Levels chart wants a sweep and reclaim off that cluster. Fractal chart wants the same sweep to run the trendline to ~1.2480 by October before the turn. Either way, the tell is the reclaim, not the flush. Down to grab liquidity, up to pay.
▪️ USDSGD is coiled at 1.2766, holding the 8.3/10 zone with a POWER-6 Bull Cluster below at 1.2656–1.2668 and heavy bear liquidity overhead into 1.2880 → 1.2960. Near-term lean is down first to strip buy-side liquidity, then a reclaim that flips the tape back toward the 1.2900s.
🔴 CEILING — overhead supply & sell-side liquidity
▪️ 1.2820–1.2840 — ◆ Bear Cluster POWER 9/10 · 0.57% + ★★ 6.4/10 MODERATE · 51 retests · first lid
▪️ 1.2880–1.2900 — ◆ Bear Cluster POWER 9/10 · 1.04% + ★★★ 7.8/10 STRONG · 43 retests · the heavy wall / primary reclaim target
▪️ 1.2960–1.2978 — ◆ Bear Cluster POWER 6/10 · 1.6% + ★★★ 7.7/10 STRONG · 29 retests · major supply / bull extension
▪️ 1.3000–1.3020 — ◆ Bear Cluster POWER 8/10 · 2.04% + ★ 4.7/10 WEAK · 22 retests · range high
🟢 FLOOR — demand & buy-side liquidity
▪️ 1.2755–1.2770 — ★★★★ 8.3/10 VERY STRONG IN-ZONE · 36 retests · price is here / the shelf to be swept
▪️ 1.2695 — ★ 4.8/10 WEAK SUPPORT · 16 retests · air pocket, not a floor
▪️ 1.2656–1.2668 — ◆ Bull Cluster POWER 6/10 · 0.8% + − 3.6/10 FORMING · 3 retests · Chart-1 sweep target / first reversal-long
▪️ ~1.2480 — trendline touch #3 (Chart 2) · sub-1.25 fractal target · Oct 2026 / deep-sweep reversal zone
▪️ ORDER FLOW / ZONE MAP
▪️ Below: 8.3/10 (1.2760) → WEAK 4.8/10 (1.2695) → Bull Cluster (1.2656–1.2668) → trendline (1.2480). The 8.3 is strong, but the ground under it is soft — one clean break feeds thin support and a POWER-6 pool. The fractal says stops don't settle until 1.2480.
▪️ Overhead: 6.4/10 (1.2820) → 7.8/10 STRONG + Bear Cluster (1.2880) → 7.7/10 STRONG + Bear Cluster (1.2960). Dense, stacked sell-side. The 1.2880–1.2960 band is where a reclaim rally goes to get sold — and where the yellow arrows point.
🔍 SCENARIO PATH
▪️ Down leg (liquidity grab): lose 1.2755, run the WEAK 1.2695, tag the Bull Cluster 1.2656–1.2668. Base case stops here.
▪️ Extension (fractal case): no reclaim at 1.2656 → trendline pull to ~1.2480 into October, completing the 1-2-3.
▪️ Reclaim: reject the sweep — cluster or trendline — and reclaim 1.2700+. That's the trigger, not the low.
▪️ Up rotation: back through 1.2820 → into the 1.2880 STRONG / Bear Cluster where the first target sits; clean strength runs the 1.2960 wall.
▪️ Invalidation: daily close below 1.2480 with no reclaim kills the reversal — the sweep becomes a trend and SGD strength runs unopposed until 1.2700 is reclaimed.
🔒 Levels and paths from the zone model. No signals, no repaint — a scenario, not a promise.
▪️ ProjectSyndicate Levels Desk — weekly S/R & liquidity zones for XAUUSD, GBPUSD, NVDA, NQ, ES & GC. Subscribe to stay up to date.
#USDSGD #SGD #Forex #Trading SpaceX (SPCX) 2026+ Catalysts & Risks Institutional OverviewSPCX (2026+) Catalysts, Risks & Financials: Ranked Desk Views
As of August 18, 2026. Stock ~$146. Consensus rating Moderate Buy (~24 of ~32 analysts buy/strong-buy); average 12-month target ~$223 (~+53% upside); range $75 (low) → $600 (high, Morgan Stanley bull). Syndicate Catalysts Desk 12-mo target $170 (HOLD). Next earnings ~early Nov 2026 (Q3 2026). Latest reported quarter: Q2 2026 (ended Jun 30, 2026) — revenue $7.81B (+92% YoY), Connectivity/Starlink $4.29B (+66%) with $1.66B operating profit, AI $2.6B (+247%). Segment valuations, forward revenue and probabilities are Desk estimates.
🔑 Key Catalysts Driving SPCX (2026+)
🛰️ Starlink Franchise + V3 Capacity Unlock (the core engine)
Starlink is the profit engine — FY25 revenue $11.4B (+50%), ~39% operating margin, and the only profitable segment. Subscribers doubled YoY to 12.0M (30 Jun 2026) across ~160 markets. The economic step-change is the V3 satellite (Starship-launched, ~10× V2 capacity), which is what lets ARPU (~$66) stabilise as subs compound toward a modelled 20M+. Direct-to-cell rides ~65 MHz of EchoStar spectrum (~$17B, FCC-approved 12 May 2026). Impact Score: 9.4/10
🚀 Starship Block 3 + Full Reusability (the upgrade cycle)
Starship Block 3 infrastructure is building at Cape Canaveral; the first Florida flight and orbital booster-and-ship reuse are the prerequisite for Artemis lunar landing, point-to-point, V3 Starlink and larger Starshield/AI payloads. A structural ~$2,700–3,000/kg reusable-launch cost is the moat behind every other segment; sub-$100/kg Starship is the aspiration. Impact Score: 9.0/10
🤖 AI / xAI Cloud ARR Ramp (the second engine, and the optionality)
AI revenue +247% YoY to $2.6B in Q2, of which ~$1.6B was new cloud/compute-hosting revenue; adjusted EBITDA turned positive (+$1.1B) for the first time. Google (~$920M/mo) and Anthropic (~$1.25B/mo) cloud contracts run ~$26B/yr; CFO added $6.7B of new contracts and targets a $100B ARR run-rate by year-end 2026. Colossus scaled to 1.4 GW, targeting 10–20 GW by end-2027. The $60B Cursor (Anysphere) deal closed 15 Aug. Impact Score: 8.8/10
🛡️ Golden Dome / Starshield Defense Stack
~$6.45B of Golden Dome awards in May 2026 — $4.16B SB-AMTI + $2.29B SDN Backbone — plus an 18-mission SBST launch sweep (~$1.6B), together exceeding every rival's combined prototype awards. Near-vertically integrated (builds and launches), with a multi-award pipeline toward a ~600-satellite architecture and prototype milestones through end-2027. Impact Score: 8.3/10
📡 Direct-to-Cell + EchoStar Spectrum
650+ D2C satellites live, T-Mobile service since Oct 2025, and a large nationwide spectrum position. Large TAM against a global space economy projected to reach $1.8T by 2035 (WEF/McKinsey), tempered by the FCC's 23 Apr 2026 block of a separate spectrum bid and urban-coverage limits. Impact Score: 7.5/10
📈 Earnings Cadence & Estimate Revisions
Each of the first public prints is a high-conviction, high-volatility binary; Q2 confirmed +92% growth. Sell-side initiations cluster wide ($210 UBS, $235 Deutsche Bank, $250 Macquarie, $300/$600 Morgan Stanley) around a ~$223 mean, with revision momentum a flow driver. Impact Score: 7.2/10
💵 Capital-Markets / Structural (Index Inclusion + Institutional Accumulation)
Added to the Nasdaq-100 on 7 July 2026 (fast-entry rule; S&P 500 a 2027 candidate). Institutional base includes Alphabet (~$94.2B), Nvidia (~$21B), Fidelity, Saudi PIF, BlackRock, Ontario Teachers', Harvard; 1,500+ institutions disclosed. Impact Score: 7.0/10
🌘 Artemis / Lunar & Commercial Point-to-Point (long-dated optionality)
Human lunar landing (Artemis), commercial point-to-point Earth transport and "AI-in-space" data centres are large but distant, gated on Starship. Impact Score: 6.0/10
🔀 Tesla–SpaceX Merger Optionality
WSJ reported (11 Aug 2026) a clause in Musk's ~$1T Tesla pay package that could unlock on a Tesla-into-SpaceX merger; Musk denied it, prediction markets imply ~17.5% by year-end. Impact Score: 5.5/10
⚠️ Key Risks & Negative Drivers
🫧 Valuation & Multiple De-Rating
~$1.93T cap at ≈84× trailing sales with negative EPS (–$2.27) and no P/E or EV/EBITDA anchor. Roughly half the valuation rests on unproven AI. The stock already round-tripped from a $225.64 high to a $104.83 low; any guidance wobble → sharp de-rating toward Morningstar's ~$40–$62 core-business estimate. Risk Severity: 8.5/10
🔥 AI Cash Burn & Capital Needs (the SPCX "circular-financing" analog)
Capex was $18.37B in Q2 alone ($15.83B AI), >6× YoY; FY26E ~$65B outruns operating cash, with FCF deeply negative (~–$25B H1'26). KeyBanc flags ~$325B of raises over 18–24 months to fund AI compute — massive dilution risk. Risk Severity: 8.5/10
🔒 Lock-Up / Supply Overhang
Musk's ~6.4B-share June-2027 cliff equals ~4× the ~3–5% public float; ~1.7B more insider shares unlock through Dec 2026. The 6 Aug and index-inclusion days already showed "sell-the-news" behaviour. Risk Severity: 7.8/10
👑 Governance / Key-Man
Musk controls ~82.4% of votes via 10-vote super-voting stock; mandatory arbitration, a ~$52.5B derivative-suit threshold, and a Warren/SEC letter (9 Jun 2026) frame limited minority recourse. Headline/distraction risk spans his empire. Risk Severity: 7.5/10
🎯 Segment Profitability Concentration
Starlink is the only profitable leg; it subsidises Space (Starship R&D) and a loss-making AI segment. A Starlink stumble removes the group's earnings ballast. Risk Severity: 7.3/10
☁️ Cloud-Contract Cancellability
The Google and Anthropic cloud contracts (~$26B/yr) are cancellable on 90 days' notice after 31 Dec 2026 — a durability risk against which >half the AI valuation is underwritten. Risk Severity: 7.0/10
🥊 Competition & 🛰️ Execution
Launch: Rocket Lab (Neutron), Blue Origin (New Glenn), ULA (Vulcan). Starlink: Amazon Leo/Kuiper, Eutelsat-OneWeb, Chinese constellations. AI: Nvidia ecosystem, OpenAI, Anthropic, Google — where Grok holds <5% of the global assistant market. Starship remains in test (Flight 13 abort, 16 Jul); Block 3 unproven. Risk Severity: 6.5/10
📉 Macro / AI-Capex Cycle & Rates + 🔀 Earnings Volatility
Long-duration valuation is acutely rate- and sentiment-sensitive; a turn in the AI-capex cycle hits SPCX like the other mega-cap AI names. First prints have already sold off on capex shock. Risk Severity: 6.5/10
💰 Financial Scorecard (Q2 2026, ended Jun 30, 2026)
Each metric scored 0–10 on strength/quality relative to trajectory.
# Metric Latest Value Trend Strength
F1 Total revenue $7.81B +92% YoY; first public print, consensus beat 9.0
F2 Connectivity/Starlink revenue $4.29B +66% YoY; $1.66B op profit — only profitable segment 9.2
F3 Starlink subscribers 12.0M Doubled YoY; ~160 markets; ARPU ~$66 8.5
F4 Adjusted EBITDA $3.5B +191% YoY 8.0
F5 AI segment revenue $2.6B +247% YoY; adj. EBITDA +$1.1B (first positive) 7.0
F6 Cash & equivalents $93.5B vs $36.8B debt/leases post-IPO — strong liquidity 7.5
F7 Defense awards (2026 YTD) ~$6.45B Golden Dome SB-AMTI + SDN; multi-award pool 7.5
F8 Backlog / contracted cloud ~$47.5B / $14.1B Growing government + cloud commitments 7.0
F9 Net loss –$541M Narrowed from –$1.01B — improving but negative 4.5
F10 Capex $18.37B $15.83B AI; >6× YoY; ~$65B FY26E guide 2.5
F11 Free cash flow ~–$25B (H1'26) Deeply negative; implies dilutive raises 2.0
Financial composite (operating strength, avg of F1–F11): ~6.6/10 — elite top-line growth and a world-class Starlink franchise, offset by a loss-making AI leg, extreme capex intensity and negative free cash flow. (Distinct from the Desk's quality-and-trajectory scorecard of ~5.3/10, which also penalises dilution and sparse disclosure.)
🏆 Master Ranking — Catalysts & Financial Strengths Combined
Positive drivers ranked by score. Risks listed separately below.
Rank Driver Type Score (0–10)
1️⃣ 🛰️ Starlink franchise + V3 capacity unlock Catalyst 9.4
2️⃣ 🏢 Starlink revenue $4.29B (+66%, $1.66B op profit) Financial 9.2
3️⃣ 📊 Total revenue $7.81B (+92% YoY) Financial 9.0
3️⃣ 🤖 AI cloud ARR ramp toward $100B Catalyst 9.0
3️⃣ 🚀 Starship Block 3 + full reusability Catalyst 9.0
6️⃣ 📈 Starlink subscribers 12.0M (doubled YoY) Financial 8.5
7️⃣ 🛡️ Golden Dome / Starshield defense stack Catalyst 8.3
8️⃣ 💵 Adjusted EBITDA $3.5B (+191%) Financial 8.0
9️⃣ 🏦 Cash $93.5B vs $36.8B debt Financial 7.5
9️⃣ 🛡️ Defense awards ~$6.45B (2026) Financial 7.5
11️⃣ 📡 Direct-to-cell + EchoStar spectrum Catalyst 7.5
12️⃣ 📑 Earnings cadence & estimate revisions Catalyst 7.2
13️⃣ 📦 Backlog $47.5B + $14.1B contracted cloud Financial 7.0
13️⃣ 💵 Capital-markets: Nasdaq-100 + institutional accumulation Catalyst 7.0
15️⃣ 🌘 Artemis / lunar & point-to-point optionality Catalyst 6.0
⚠️ Risk Ledger (severity-ranked)
Rank Risk Severity (0–10)
1️⃣ 🫧 Valuation & multiple de-rating (~84× sales, neg. EPS) 8.5
1️⃣ 🔥 AI cash burn & ~$325B capital needs / dilution 8.5
3️⃣ 🔒 Lock-up / supply overhang (6.4B-sh Jun-2027 cliff) 7.8
4️⃣ 👑 Governance / key-man (Musk ~82% voting) 7.5
5️⃣ 🎯 Profit concentration (Starlink only profitable leg) 7.3
6️⃣ ☁️ Cloud-contract cancellability (Google/Anthropic 90-day) 7.0
7️⃣ 🥊 Competition + 🛰️ Starship execution / capex 6.5
7️⃣ 📉 Macro / AI-capex cycle & rate sensitivity 6.5
9️⃣ 📡 Regulatory / spectrum / orbital debris 5.8
🔟 🏛️ Policy / government dependence · 🔀 earnings volatility 5.5
📝 Summary Outlook (August 2026)
SpaceX enters H2 CY2026 as the most consequential public company in the space-and-AI buildout — record $7.81B quarterly revenue (+92%), a 12M-subscriber, ~39%-margin Starlink franchise that is the only profitable leg, an AI segment growing +247% with its first positive adjusted EBITDA, and ~$6.45B of Golden Dome defense wins layered on a structural launch monopoly. The Starlink V3 → Starship Block 3 cadence gives a built-in capacity upgrade cycle, and the Tesla merger is pure — and unconfirmed — optionality.
The bear case is not about demand — it's about how the growth is financed. Capex of $18.4B in a single quarter, deeply negative free cash flow, KeyBanc's ~$325B capital-need estimate, cancellable cloud contracts, and a ~6.4B-share June-2027 lock-up cliff sit against a ~$1.9T cap priced at ≈84× sales. Governance (~82% Musk voting control) leaves minority holders as passengers.
Bottom line: the core franchise is as strong as any in the buildout (operating-strength composite ~6.6/10), but the risk isn't operational execution — it's whether the AI-capex flywheel is self-sustaining or dilution-financed, and whether the June-2027 supply cliff is absorbed. We rate HOLD, $170 target: accumulate <$120, trim >$210. The next Q3 print (capex trajectory, AI ARR conversion, Starship timing) is the next decisive catalyst.
Sources: SpaceX S-1 (20 May 2026), 424B, Q2 2026 shareholder letter & transcript (4 Aug 2026); Musk 13G (30 Jun 2026); Space Systems Command award notices (SB-AMTI 29 May, SDN 26 May 2026); CNBC, Teslarati, BigGo, Yahoo Finance (earnings); Tech Times (SBST); stockanalysis.com, TipRanks (price/targets); UBS, Morgan Stanley, Deutsche Bank, Phillip Securities, KeyBanc, Morningstar (ratings); Reuters/Nvidia 13F (holders); Warren–SEC letter (9 Jun 2026); WSJ (11 Aug 2026, Tesla merger); FCC orders; Sensor Tower/Similarweb (Grok share); WEF/McKinsey ($1.8T space economy); Anysphere/Cursor close (15 Aug 2026).  Long

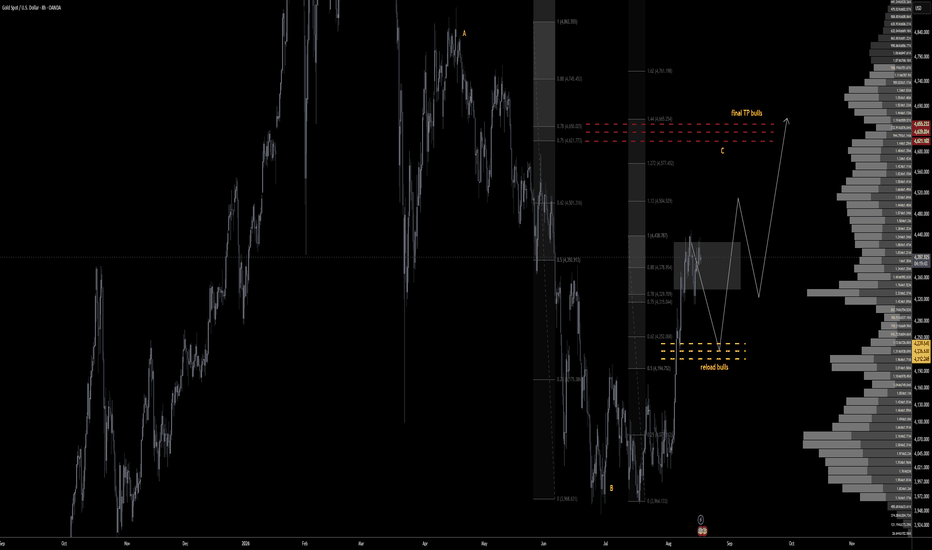
GOLD H8 Institutional Liquidity Levels Bulls/Bears▪️ My read: Corrective ABC into its business end — this is a buy-the-dip-into-reload map, not a chase-it-here map. Price is pinned at 4,390, sitting dead on the 0.5 retrace of the whole 4,862 → 3,964 decline (4,392.913) — the textbook middle, and the middle chops.
The chart's sequence: drift/flush down first into the 4,212–4,252 RELOAD bull cluster (grab the sell-stops resting below the 0.62 sub-fib), reclaim, then rotate the C-leg up to complete into the 4,621–4,665 FINAL-TP cluster. The dip is the bait; the reclaim off the 4,200s cluster is the trade. Buy the flush, hold, exit into the cap.
▪️ Gold (XAUUSD, H8) is coiled at 4,390 between two labeled pools: a Bull Liquidity Cluster at 4,212–4,252 (yellow) just below and a stacked Bull-Target Cluster at 4,621–4,665 (red) overhead. Near-term path is a pullback to reload longs into 4,212–4,252, then a reclaim that drives the C-wave up to the ~4,650 magnet where the move gets banked.
🔴 CEILING — overhead supply & sell-side liquidity
▪️ 4,400–4,438 — ★★ MODERATE · 1.0 sub-fib (4,438.787) + current range top · first lid to clear
▪️ 4,501–4,504 — ★★ MODERATE · 0.62 main-fib (4,501.316) + 1.13 sub-ext (4,504.529) · rotation checkpoint
▪️ 4,577 — ★ MINOR · 1.272 sub-ext (4,577.452) · thin air between checkpoints
▪️ 4,621–4,665 — ◆ Bull-Target Cluster (4,621.102 / 4,639.034 / 4,655.233) + ★★★ STRONG · 0.75 main (4,621.773) + 0.78 main (4,650.025) + 1.44 sub-ext (4,665.254) · FINAL TP / C-wave completion / where longs exit
▪️ 4,745–4,862 — ★★ EXTENSION · 0.88 main (4,745.453) → 1.62 sub-ext (4,761.198) → A-high / 1.0 main (4,862.555) · overshoot only
🟢 FLOOR — demand & buy-side liquidity
▪️ 4,315–4,330 — ★★ MODERATE · 0.75/0.78 sub-fib (4,315.044 / 4,329.709) + 2.54M HVN · first bounce / partial dip
▪️ 4,212–4,252 — ◆ Bull Liquidity Cluster (4,212.248 / 4,226.630 / 4,239.540) + ★★★ STRONG · 0.62 sub (4,252.068) → 0.5 sub (4,194.752) / 0.35 main (4,175.336) + 2.52M HVN below · RELOAD-LONG / where the bull case fires
▪️ 4,045–4,076 — ★★★ MAJOR HVN · 0.25 main (4,076.816) + 2.56M/2.61M nodes · structural floor / deep invalidation
▪️ ORDER FLOW / ZONE MAP
▪️ Below: 4,315–4,330 (HVN speed bump) → RELOAD cluster 4,212–4,252 → 4,045–4,076 major HVN. The 4,315 node is a partial fill; the real reversal fuel sits in the 4,212–4,252 cluster where the two fib sets, the volume node and the labeled cluster all stack. A dip there is a liquidity grab, not a trend change.
▪️ Overhead: 4,400–4,438 lid → 4,501–4,504 → 4,577 → 4,621–4,665 target cluster. The 4,621–4,665 red zone is both the densest fib confluence on the board (0.75 + 0.78 main + 1.44 sub-ext) and the C-wave completion — that's what the arrows point at.
🔍 SCENARIO PATH (buy dips → hold → exit higher)
▪️ Dip first (buy-side grab): from 4,390 through 4,315–4,330 into RELOAD 4,212–4,252 — flush the stops below the 0.62 sub-fib, tag the yellow cluster.
▪️ Reclaim / reload: reject the flush, reclaim back above ~4,252, confirm the reversal off the cluster — that's the long trigger, not the flush itself. Buy the dip / reload longs.
▪️ Hold the rotation: drive back through 4,390 → 4,438 → 4,501–4,504 → 4,577 into 4,621–4,665. Hold the position through the leg; the red cluster is the exit.
▪️ Exit / optional extension: bank into 4,621–4,665; only clean strength beyond opens 4,745 → 4,761 → 4,862 (A-high).
▪️ Bull invalidation: a decisive H8 close and hold below 4,212 (confirmed under 4,175 / into the 4,045–4,076 HVN) breaks the reversal — the dip becomes a breakdown and the bull read is off until price reclaims the 4,200s.
▪️ Dip into the reload, reclaim, ride to the cap. Buy the flush, not the middle. Edges pay, the middle chops.
🔒 Levels and paths from the zone model — fib confluence, structure and the volume-profile weighting on the right. No signals, no repaint — a scenario, not a promise.
▪️ ProjectSyndicate Levels Desk — weekly S/R & liquidity zones for XAUUSD, GBPUSD, NVDA, NQ, ES & GC. Subscribe to stay up to date.
#Gold #XAUUSD #GC #Trading  Long
ES H4 Institutional Liquidity Levels Bulls/Bears▪️ My read: Textbook higher-low staircase — 7,263 → 7,401 → and the market is stepping up to build the next rung now. The early-August runaway gap was the tell: that's strength mid-trend, not exhaustion. Price is stretched into the 7,843 high and owes a pullback, but the pullback is the setup, not the top. The reload sits at the 7,573–7,593 higher low — buy the dip into structure, don't chase the print. Hold the last higher low and the September leg targets fresh range highs. Reloading the low pays; chasing the high doesn't.
▪️ ES futures are trading near 7,814, pressed against the 7,818–7,843 high after a clean run off the 7,401 higher low. The structure is unbroken: two confirmed higher lows, a runaway gap mid-move confirming the trend, and price now extended into thin air at the top of the range. Beneath price the demand shelves stack in order — 7,712, the flipped 7,623 June high, then the primary 7,573–7,593 reload where the third higher low is projected to print. Coiled at the highs with a pullback loading; the dip is where the trade is.
▪️ Primary outlook: pullback first, then continuation off the higher low. The red path is the near-term rotation — reject the 7,843 high, roll back through 7,712 and the 7,623 shelf into the 7,573–7,593 reload where higher low #3 sets. The grey path is the dominant move that follows — buyers defend the higher low, reclaim 7,843, and drive the September leg into new range highs. Pullback into end of August, rally resumes off the lows in September.
🔴 CEILING — overhead supply & breakout liquidity
▪️ 7,818–7,843 — ★★ 5.8/10 recent high · 6 retests · local supply / source of the pullback (price here now)
▪️ >7,843 — ◆ open-air continuation · resting breakout liquidity above the range · September objective ~7,950–8,050 on the measured move off the reload (~140–235 pts up)
🟢 FLOOR — demand, higher-low structure & the reload
▪️ 7,700–7,728 — ★ 5.2/10 WEAK · 9 retests · first pullback shelf / minor demand (~90 pts down)
▪️ 7,640–7,656 — ★ 5.0/10 WEAK · 7 retests · secondary catch
▪️ 7,600–7,623 — ★★ 6.4/10 MODERATE · 12 retests · prior June swing high flipped to support · defends the reload from above
▪️ 7,573–7,593 — ★★★ 7.6/10 STRONG · THE RELOAD · projected higher low #3 · primary buy zone / highest-value long on the board (~230 pts down)
▪️ 7,500–7,560 — ◆ runaway-gap base · August platform · gap-fill demand · deeper catch if 7,573 flushes
▪️ 7,388–7,401 — ★★★ 8.1/10 STRONG · 18 retests · higher low #2 · sequence-defining pivot
▪️ 7,250–7,266 — ★★★ 8.4/10 STRONG · 22 retests · higher low #1 · deepest structural low / bull-thesis invalidation below
▪️ ORDER FLOW / ZONE MAP
▪️ Overhead: price is jammed against 7,843 with open air above. Thin supply at a fresh high into resting breakout liquidity — exactly the kind of ceiling that caps a stretched move and forces the pullback before the trend can extend. Not a top; a pause.
▪️ Below: 7,712 shelf → flipped 7,623 June high → the 7,573–7,593 reload → the 7,401 higher low. The reload is the trade — it's where higher low #3 is projected to print, it sits above the sequence-defining 7,401 pivot, and it's the highest-value long on the chart. Lose 7,401 on a closing basis and the staircase breaks; that's the line that matters.
🔍 SCENARIO PATH
▪️ Pullback first (the gift): reject 7,818–7,843, roll down through 7,712 and the 7,623 shelf into the 7,573–7,593 reload. This is the end-of-August dip.
▪️ Reload: buyers defend 7,573–7,593, print the third higher low, base and turn. If flushed, the 7,500–7,560 gap base catches it; the 7,401 higher low is the last line before structure breaks.
▪️ Continuation: reclaim 7,700 → 7,843, break the high, and the September leg opens toward fresh range highs ~7,950–8,050 on the measured move.
▪️ Bull invalidation: a clean close below 7,401 negates the higher-low sequence and puts 7,263 back in play — stand down on the long until structure repairs.
🔒 Levels and paths from the zone model. No signals, no repaint — a scenario, not a promise.
▪️ ProjectSyndicate Levels Desk — weekly S/R & liquidity zones for XAUUSD, GBPUSD, NVDA, NQ, ES & GC. Subscribe to stay up to date.
#ES #SP500 #Futures #Trading  Long

BTC H2 Institutional Liquidity Levels Bulls/Bears▪️ My read: This is a bear-trap-to-reversal map, not a straight-down thesis. Price near 63,438 is hanging just above a 7.6/10 STRONG support shelf with a POWER-10 Bull Liquidity Cluster stacked below it at 62,072–62,300. The expected sequence is a liquidity sweep first — flush the 7.6/10 shelf and run stops down into the bull cluster — then reclaim, reverse, and turn bullish with the run targeting 65,000 into the overhead Bear Cluster / 7.4/10 STRONG wall. The down move is the bait; the reclaim off the 62,000s POWER-10 demand is the trade. Sweep the floor, reclaim, rotate up. Edges pay, the middle chops.
▪️ Bitcoin is coiled near 63,438, pinned between two loaded pools: a POWER-10 Bull Liquidity Cluster at 62,072–62,300 just below and a stack of POWER-10 Bear Clusters overhead into 64,939 → 65,600. The near-term path is down first to grab sell-side liquidity, then a reclaim that flips the tape bullish toward the 65,000 magnet.
🔴 CEILING — overhead supply & sell-side liquidity
▪️ 64,400–64,600 — ★★★ 7.8/10 STRONG RESISTANCE · 30 retests · first lid overhead
▪️ 64,939–65,000 — ◆ Bear Liquidity Cluster POWER 10/10 · 2.28% + ★★★ 7.4/10 STRONG RESISTANCE · 41 retests · the primary upside target / reclaim destination (~65,000)
▪️ 65,600–65,800 — ◆ Bear Liquidity Cluster POWER 10/10 · 3.37% + ★★ 6.6/10 MODERATE RESISTANCE · 33 retests · range high / bull extension
🟢 FLOOR — demand & buy-side liquidity
▪️ 63,007–63,150 — ★★★ 7.6/10 STRONG SUPPORT · 27 retests · immediate shelf under price / the level to be swept
▪️ 62,072–62,300 — ◆ Bull Liquidity Cluster POWER 10/10 · 2.13% + ★★ 6.9/10 MODERATE SUPPORT · 11 retests · the sweep target / primary reversal-long / where the bull case fires
▪️ ORDER FLOW / ZONE MAP
▪️ Below: 7.6/10 STRONG (63,007–63,150) → Bull Cluster 62,072–62,300 (POWER 10/10, overlapped by 6.9/10 MODERATE). The 7.6/10 shelf is the trap door — a break of it doesn't confirm a trend, it feeds the sweep into the POWER-10 pool right underneath, which is where the reversal is expected to originate.
▪️ Overhead: 7.8/10 STRONG (64,400–64,600) → Bear Cluster + 7.4/10 STRONG at 64,939–65,000 → Bear Cluster + 6.6/10 at 65,600–65,800. Heavy, stacked sell-side liquidity. The 65,000 wall is both the strongest resistance and the natural target once the reclaim plays out — that's what the yellow arrows are pointing at.
🔍 SCENARIO PATH
▪️ Down leg first (liquidity grab): flush from 63,438 through the 7.6/10 shelf (63,007–63,150) into the Bull Cluster 62,072–62,300, running resting sell-stops and tagging buy-side liquidity.
▪️ Reclaim: reject the sweep, reclaim back above 63,150, and confirm the reversal off the POWER-10 demand — this is the trigger, not the flush itself.
▪️ Up rotation: drive back through 63,600 → 64,162 → the 7.8/10 STRONG at 64,400–64,600 → into the 64,939–65,000 Bear Cluster / 7.4/10 STRONG where the primary target sits. Clean strength extends toward the 65,600–65,800 upper cluster.
▪️ Bull invalidation: a decisive break and hold below the Bull Cluster (<62,072) breaks the reversal thesis — the sweep becomes a breakdown and the bullish read is off until price reclaims the 62,000s.
🔒 Levels and paths from the zone model. No signals, no repaint — a scenario, not a promise.
▪️ ProjectSyndicate Levels Desk — weekly S/R & liquidity zones for XAUUSD, GBPUSD, NVDA, NQ, ES & GC. Subscribe to stay up to date.
#BTC #Bitcoin #Crypto #Trading  Long

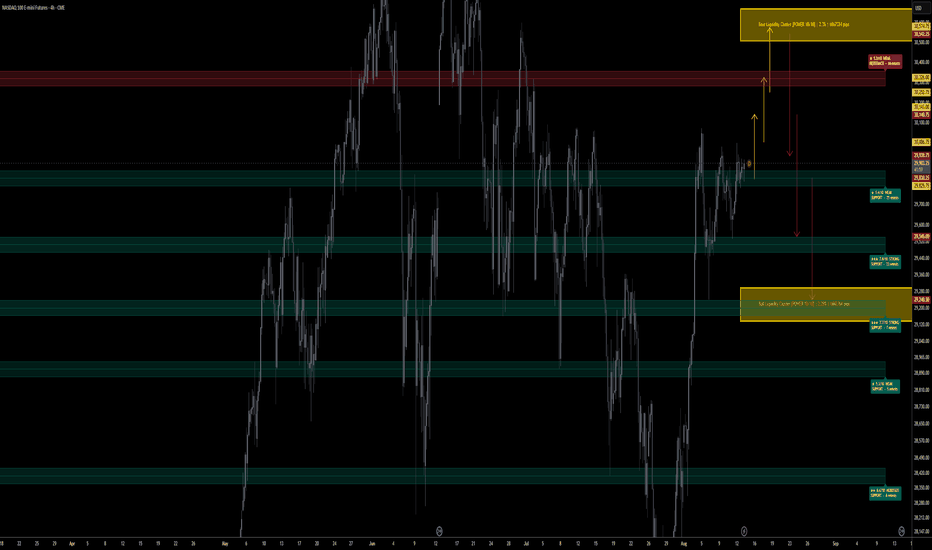
NQ H4 Institutional Liquidity Levels Bulls/Bears▪️ My read: Coiled above a weak shelf with a POWER-10 sell pool above and a POWER-10 buy pool below — a classic grab-and-reverse setup. The up-push into 30,300 / the Bear Cluster is bait to run buy-side stops before the real move rotates down into the 29,240 POWER-10 demand, where the 7.7/10 STRONG overlap makes it the highest-value long on the chart. Reclaim and hold above 30,600 flips bias bullish toward the range high. Edges pay, the middle chops.
▪️ Nasdaq futures are trading near 29,907, pressing up off a ★ 5.4/10 WEAK SUPPORT shelf (25 retests) that sits directly beneath price. Overhead, a POWER 10/10 Bear Liquidity Cluster looms at the top of the range (~30,500–30,600), with a 5.2/10 weak resistance band as the first speed bump into it. Below, a POWER 10/10 Bull Liquidity Cluster waits at 29,240, cushioned by two STRONG demand shelves. Price is coiled between two loaded pools with the near-term push aimed up.
▪️ Primary outlook: up-sweep first, then rotation down into demand. The yellow paths run price up through 30,143 → the 5.2/10 resistance at 30,300 → into the Bear Cluster 30,500–600 to tag overhead sell-side liquidity. The red paths are the dominant rotation back down — reject the cluster, roll through the 7.8/10 shelf at 29,545, into the POWER-10 Bull Cluster at 29,240 where the high-value long sits.
🔴 CEILING — overhead supply & sell-side liquidity
▪️ 30,252–30,326 — ★ 5.2/10 WEAK RESISTANCE · 14 retests · first lid overhead (~400 pts up)
▪️ 30,500–30,600 — ◆ Bear Liquidity Cluster POWER 10/10 · 2.28% · the up-sweep magnet / where the reversal is expected to originate (~650 pts up)
🟢 FLOOR — demand & buy-side liquidity
▪️ 29,825–29,830 — ★ 5.4/10 WEAK SUPPORT · 25 retests · immediate shelf under price (in play now)
▪️ 29,440–29,545 — ★★★ 7.8/10 STRONG SUPPORT · 23 retests · first heavy demand / rotation target
▪️ 29,200–29,280 — ◆ Bull Liquidity Cluster POWER 10/10 · 2.3% · primary reversal-long / deep magnet
▪️ 29,120–29,240 — ★★★ 7.7/10 STRONG SUPPORT · 7 retests · overlaps the bull cluster, reinforcing the pool
▪️ 28,810–28,890 — ★ 5.3/10 WEAK SUPPORT · 5 retests
▪️ 28,350–28,420 — ★★ 6.6/10 MODERATE SUPPORT · 6 retests · range floor / deepest catch
▪️ ORDER FLOW / ZONE MAP
▪️ Overhead: 5.2/10 weak resistance (30,300) → Bear Cluster 30,500–600 (POWER 10/10). Thin, weak supply into a heavy liquidity pool at the top — this is exactly the kind of ceiling an up-sweep runs into to grab resting buy-stops before it turns.
▪️ Below: 5.4/10 shelf (29,825) → 7.8/10 STRONG (29,545) → Bull Cluster 29,240 stacked with 7.7/10 STRONG. The 29,545 shelf is the first line of defense; the 29,200–29,280 pool — reinforced by the overlapping 7.7/10 — is the deepest, highest-value reversal zone on the board.
🔍 SCENARIO PATH
▪️ Up leg first (liquidity grab): rally from 29,907 through 30,143 → 5.2/10 resistance at 30,300 → into the Bear Cluster 30,500–600, tagging overhead sell-side liquidity.
▪️ Reversal: reject the bear cluster, print a lower high, break back below the 5.4/10 shelf (~29,825).
▪️ Down rotation: drive into 29,545 (7.8/10 STRONG) → Bull Cluster 29,240 where the primary long fires. If flushed, the 7.7/10 overlap defends the pool; deeper extension opens 28,810 and the 6.6/10 floor at 28,350–28,420.
▪️ Bull invalidation / continuation: a clean reclaim and hold above the Bear Cluster (>30,600) flips the picture — negates the rotation and opens the range high above.
🔒 Levels and paths from the zone model. No signals, no repaint — a scenario, not a promise.
▪️ ProjectSyndicate Levels Desk — weekly S/R & liquidity zones for XAUUSD, GBPUSD, NVDA, NQ, ES & GC. Subscribe to stay up to date.
#NQ #Nasdaq #Futures #Trading  Long
Eli Lilly LLY 2026+ Catalysts & Risks Institutional OverviewAs of August 12, 2026. Stock ~$1,215. First pharmaceutical company ever to cross a $1 trillion market cap (~$1.05–1.1T). An ~12-bagger since 2018 (~$100 → ~$1,215, roughly +1,100–1,200%) — a quiet, low-profile secular compounder that has outperformed most of the AI mega-caps over the cycle. Consensus rating Buy / Strong Buy (~22 covering analysts, ~20 buy / 2 hold); average 12-month price target ~$1,290–$1,300 (~+6–7% upside); range $850 (low) → $1,600 (high). Post-Q2 Street targets cluster higher: Morgan Stanley $1,419, BMO $1,400, one desk $1,385, Truist $1,376, Wells Fargo $1,330. Latest reported quarter: Q2 2026 (ended Jun 30, 2026) — revenue $23.0B (+48% YoY), Mounjaro $9.9B (+91% YoY). Next earnings ~late Oct/early Nov 2026 (Q3); Investment Community Meeting Dec 7, 2026.
🧬 Key Catalysts Driving LLY (2026+)
💊 The Incretin Franchise — Tirzepatide (Mounjaro + Zepbound), the core engine
Combined Mounjaro + Zepbound revenue reached $14.9B in Q2 (~65% of total revenue), contributing $6.3B of the quarter's growth. Mounjaro alone grew 91% to $9.9B; Zepbound $4.9B (+44% U.S.). Lilly holds ~60% U.S. GLP-1 share and accounts for 6 of 10 total U.S. obesity prescriptions and 7 of 10 injectable scripts. Tirzepatide has shown superiority vs. semaglutide in head-to-head diabetes and obesity data, and management guides patent protection into the back half of the 2030s in major markets. Impact Score: 9.7/10
🧪 Foundayo (Orforglipron) — The First Small-Molecule Oral GLP-1
FDA-approved April 1, 2026 as the first once-daily oral small-molecule GLP-1 for chronic weight management (no food/water restrictions). The oral form factor is the real story: pills are radically cheaper and easier to manufacture and ship than weekly injections, unlocking a far larger global and emerging-market TAM. First full quarter contributed $98M with prescriptions doubling month-over-month and ~1 in 4 new patient starts; already filed in ~40 countries. Efficacy (~11–12% weight loss) sits below top injectables but the convenience/scale trade is a category expander, not a cannibalizer. Impact Score: 9.5/10
🧬 Retatrutide — Best-in-Class Next-Gen Triple Agonist
Investigational GIP/GLP-1/glucagon triple receptor agonist; TRIUMPH-1 delivered ~28.3% weight loss (~70 lbs) at 80 weeks — approaching bariatric-surgery magnitude and the deepest of any GLP-1 to date. NDA filing guided to late 2026 / early 2027. Retatrutide gives Lilly a built-in upgrade cycle above tirzepatide and extends the efficacy frontier competitors are still chasing. Impact Score: 9.3/10
⬛ Obesity / GLP-1 TAM Expansion
The global obesity-drug market was ~$66B in 2025 and is guided to $120B+ by 2030 (Bloomberg Intelligence), with Lilly positioned as the primary beneficiary. Crucially, only ~1–2% of the eligible global population is currently treated — this is a penetration story, not a saturation story. Diabetes, cardiovascular, sleep apnea and other tirzepatide label expansions widen the runway further. Impact Score: 9.2/10
🌍 International & Emerging-Market Expansion
Ex-U.S. revenue jumped 80% to $8.6B; Mounjaro outside the U.S. surged 172% (China NRDL inclusion plus strong cash-pay demand in Brazil, India, China). Management notes most international patients pay out of pocket, signaling durable, price-insensitive demand as oral supply scales. This diversifies the franchise beyond a U.S. market that is beginning to mature. Impact Score: 8.7/10
🔬 Pipeline Breadth Beyond Obesity
Kisunla (donanemab) in Alzheimer's, Jaypirca in oncology (CLL/SLL), Taltz/Ebglyss in immunology & dermatology, and a growing cardiometabolic pipeline (Lp(a) and lipid programs) reduce single-franchise dependence. Aggressive business development (Orna, Centessa, Kelonia, Ajax, plus vaccines/psychiatry) is refilling the long-dated pipeline. This is the optionality layer most "GLP-1 only" bulls under-model. Impact Score: 8.5/10
👥 Aging Demographics + Chronic-Disease Supercycle
The structural tailwind: global populations are aging rapidly and the prevalence of obesity, type-2 diabetes, Alzheimer's and cardiovascular disease is rising in lockstep — precisely the therapeutic areas where Lilly leads. Demand for metabolic, neuro and chronic-care drugs compounds for decades, not quarters, giving Lilly one of the most durable secular demand curves in large-cap healthcare. This is the slow, unglamorous engine behind the "stealth bull market." Impact Score: 8.5/10
🏭 Manufacturing Scale-Up as a Moat
$27B+ committed to U.S. manufacturing (plus a fresh $4.5B for Indiana capacity for oral/retatrutide supply). In a demand-constrained category, capacity is competitive advantage — and the build-out secured a 3-year tariff reprieve under the administration's pricing deal. Supply, not demand, has been the binding constraint; closing it directly converts to revenue. Impact Score: 8.0/10
🖤 Capital Returns + Potential Stock Split
Quarterly dividend $1.73 (~$6.92/yr, ~0.57% yield) with a low ~26% payout ratio — ample room to grow. Post-Q2, split speculation intensified (last split 1997); a split wouldn't change fundamentals but would broaden retail access and tends to add a near-term bid. Impact Score: 7.5/10
⬛ Analyst Momentum & Estimate Revisions
Buy/Strong Buy consensus with a wave of post-Q2 target raises into the $1,330–$1,420 range. 2026 EPS estimates have been revised up steadily (Zacks ~$33.9, Street ~$35.50–$36.50 guided); positive revision momentum tends to pull in institutional flows. Impact Score: 7.5/10
⬛ Key Risks & Negative Drivers
⬛ Drug-Pricing Policy — MFN, IRA & Net-Price Erosion (the loudest bear case)
The dominant overhang. Lilly signed a "Most-Favored-Nation" deal committing future launches to MFN-referenced pricing across commercial, Medicare, Medicaid and cash (via the TrumpRx portal), and the administration is pushing to codify elements into law (Lilly opposes). Separately, IRA Medicare negotiation is expanding (15 more drugs in 2027, scaling thereafter). U.S. realized price already fell ~9–13% in Q2; management guides continued low-to-mid-teens U.S. price drag in 2026. Risk Severity: 8.0/10
⬛ Valuation & Franchise Concentration
A >$1T cap on a forward P/E of ~32x (TTM ~40x) prices in sustained hypergrowth, and ~65% of revenue rides one molecule class (tirzepatide/incretins). Any GLP-1 stumble — efficacy scare, supply miss, pricing shock — risks a sharp multiple de-rating. The stock has repeatedly shown two-way volatility around policy headlines. Risk Severity: 7.5/10
⬛ Competition — Novo Nordisk, Generics & Next-Gen Entrants
Novo (Wegovy/Ozempic, oral Wegovy, CagriSema, amycretin) remains a well-capitalized #2 and pre-announced steep 2027 price cuts (~50% Wegovy / ~35% Ozempic) that pressure the whole category. Generic semaglutide is emerging in markets like India and Brazil, and Viking, Amgen (MariTide) and Roche are advancing credible assets. Second-sourcing and price competition are structural features of a maturing category. Risk Severity: 7.0/10
⬛ Margin & Net-Price Erosion (rebates, formulary, mix)
Rising rebates/discounts, CVS formulary dynamics for Zepbound, declining medical-exception usage, and a shift toward lower-priced oral and international volume all pressure realized price and gross-to-net. Volume growth (+60% in Q2) is offsetting it today, but the margin math tightens if volume ever decelerates. Risk Severity: 6.5/10
⬛ Pipeline, Regulatory & Legal Risk
Reliance on the pipeline delivering: retatrutide faces litigation over its FDA regulatory pathway, Foundayo's ramp has been slower than some expected, and oral efficacy trails injectables. Add an ongoing Novo lawsuit over Mounjaro advertising and periodic compounding disputes. Binary clinical/regulatory events can move the stock hard. Risk Severity: 6.0/10
⬛ Tariffs & M&A / IPR&D Drag
Pharma import tariffs (floated at ~25%) remain a policy risk despite the temporary reprieve. Aggressive dealmaking carries integration risk and lumpy acquired-IPR&D charges — Q2 reported EPS absorbed $3.03 of IPR&D, muting the headline print even as underlying guidance rose. Risk Severity: 5.5/10
⬛ Long-Dated Patent Cliff
Tirzepatide is protected into the back half of the 2030s in major markets — comfortably distant, but a real eventual loss-of-exclusivity that the next-gen pipeline (orforglipron, retatrutide) must be positioned to absorb. Low near-term severity, non-trivial long-term. Risk Severity: 4.5/10
🩺 Financial Scorecard (Q2 2026, ended Jun 30, 2026)
Each metric scored 0–10 on strength/quality relative to expectations and trajectory.
# Metric Latest Value Trend Financial Strength
F1 Revenue $23.0B +48% YoY, ~+16% QoQ; volume +60%, price −13% 9.6
F2 Incretin franchise (M+Z) $14.9B ~65% of revenue; +$6.3B of growth YoY 9.7
F3 Mounjaro $9.9B +91% YoY; ex-U.S. +172% 9.7
F4 Gross Margin 86.3% +1.3pp YoY; pharma-leading 9.5
F5 Non-GAAP EPS $8.38 +33% YoY (reported $7.94, incl. $3.03 IPR&D) 9.0
F6 FY2026 Revenue Guidance $85–87B Raised from $82–85B 9.4
F7 Performance Margin (FY guide) 49–50.5% Strong operating leverage 8.8
F8 Cash Generation / Reinvestment Strong OCF Heavy $27B+ capex build-out compresses near-term FCF 7.5
F9 International Revenue $8.6B +80% YoY; volume +113% 9.3
F10 Pipeline / R&D Productivity Orforglipron approved; retatrutide filing; donanemab Deep, front-loaded catalyst slate 9.5
F11 Pricing Headwind / IPR&D Drag U.S. price −9 to −13%; $3.03 IPR&D Net-price erosion + lumpy charges = quality watch-item 6.5
Financial composite (avg of F1–F11): ~9.0/10 — exceptional top-line, best-in-class gross margins and a uniquely deep catalyst pipeline; the soft spots are U.S. net-price erosion, IPR&D lumpiness, and heavy reinvestment that holds down near-term free cash flow.
🏆 Master Ranking — Catalysts & Financial Strengths Combined
Positive drivers ranked by score. Risks listed separately as deductions.
Rank Driver Type Score (0–10)
1 Mounjaro $9.9B (+91% YoY) Financial 9.7
1 Incretin franchise $14.9B (~65% of revenue) Financial 9.7
1 Tirzepatide franchise dominance Catalyst 9.7
4 Revenue $23.0B (+48% YoY) Financial 9.6
5 Gross margin 86.3% Financial 9.5
5 Orforglipron / Foundayo (oral GLP-1) Catalyst 9.5
5 Pipeline / R&D productivity Financial 9.5
8 FY2026 guidance raised to $85–87B Financial 9.4
9 Retatrutide (triple agonist) Catalyst 9.3
9 International revenue $8.6B (+80%) Financial 9.3
11 Obesity / GLP-1 TAM ($66B → $120B+ by 2030) Catalyst 9.2
12 Non-GAAP EPS $8.38 (+33%) Financial 9.0
13 Performance margin 49–50.5% Financial 8.8
14 International / emerging-market expansion Catalyst 8.7
15 Pipeline breadth beyond obesity Catalyst 8.5
15 Aging demographics / chronic-disease supercycle Catalyst 8.5
17 Manufacturing scale-up as moat Catalyst 8.0
18 Capital returns + potential split Catalyst 7.5
18 Analyst momentum & revisions Catalyst 7.5
⬛ Risk Ledger (severity-ranked)
Rank Risk Severity (0–10)
1 Drug-pricing policy (MFN / IRA / net price) 8.0
2 Valuation & franchise concentration 7.5
3 Competition (Novo, generics, next-gen) 7.0
4 Margin & net-price erosion 6.5
5 Pipeline, regulatory & legal 6.0
6 Tariffs & M&A / IPR&D drag 5.5
7 Long-dated patent cliff 4.5
🖤 Long-Term Price Target Framework (BUY / HOLD)
12-Month (analyst consensus): ~$1,290–$1,300 average, range $850 → $1,600; post-Q2 Street raises cluster $1,330–$1,420. Rating: Buy / Strong Buy.
10-Year BUY / HOLD target: roughly 2x from current levels → ~$2,400–$2,500 base case.
The math is undemanding relative to the growth: with revenue compounding at a moderating mid-teens+ CAGR off an $85–87B 2026 base, EPS can plausibly build from ~$36 (2026) toward ~$70–90+ by the mid-2030s. Even assuming meaningful multiple normalization (from ~32x forward today toward a high-20s/low-30s "mature compounder" multiple), a double over a decade implies only ~7% annual price appreciation — a conservative outcome for a franchise leader in an under-penetrated, secularly expanding market. Some Street voices are more aggressive (a widely-cited call sees a $2T market cap by ~2031). Aging demographics and rising chronic-disease prevalence are the ballast under this thesis: the demand curve compounds regardless of the quarterly tape.
Scenario band (10-yr, directional):
• Bear (~$1,300–$1,600): MFN codified + aggressive price cuts + share loss compress both growth and multiple.
• Base (~$2,400–$2,500): steady incretin leadership, successful oral/retatrutide scale-up, TAM expansion as modeled.
• Bull ($3,000+): retatrutide best-in-class, oral unlocks emerging markets, pipeline (Alzheimer's/cardiometabolic) delivers a second engine.
Posture: a long-term BUY / core HOLD — accumulate on policy-driven drawdowns, size for the two-way volatility around pricing headlines and quarterly prints.
📝 Summary Outlook (August 2026)
Eli Lilly is the quiet heavyweight of the market — the first pharma to cross $1 trillion, an ~12-bagger since 2018, and a franchise growing revenue 48% at 86% gross margins while most investors are watching the AI names. The engine is tirzepatide (Mounjaro + Zepbound, ~65% of revenue), now flanked by the first oral small-molecule GLP-1 (Foundayo) and a best-in-class triple agonist (retatrutide) filing into 2026/27. With only ~1–2% of the eligible global population treated, a $66B market heading to $120B+ by 2030, and an aging, chronically-sicker world underneath it all, the demand runway is measured in decades.
The bear case is not about demand — it's about price and policy. MFN referencing, IRA negotiation and the TrumpRx framework are eroding U.S. net price (−9 to −13% and counting), a >$1T cap on ~32x forward earnings prices in continued excellence, and Novo plus generics plus next-gen entrants keep the category competitive. Volume growth is currently swamping the price drag; the risk is what happens to the margin math if that ever reverses.
Bottom line: fundamentals are among the best in mega-cap healthcare (financial composite ~9.0/10), the pipeline is uniquely deep, and the secular demographic tailwind is real and durable. The debate isn't whether Lilly grows — it's how much of that growth policy and pricing extract along the way. For a 10-year horizon, a conservative "roughly double" (~$2,400–$2,500) is a reasonable base case, with genuine upside if oral GLP-1 and retatrutide scale as the data suggests.
Sources: Lilly Q2 2026 & Q1 2026 press releases and CFO commentary (SEC 8-K, investor.lilly.com, PRNewswire); CNBC, Yahoo Finance, Quartz, GuruFocus, FXLeaders (earnings); StockAnalysis, WallStreetZen, Public.com, TipRanks, CNN, TradingView (targets/ratings); PharmExec, AJMC, PhysiciansWeekly, Lilly IR (orforglipron/retatrutide); CNBC, BioPharma Dive, Bloomberg, Axios, Barchart, DrugDiscoveryTrends (MFN/IRA/tariffs); The Motley Fool, The Corner, Zacks, TIKR (competition/TAM/valuation).  Long
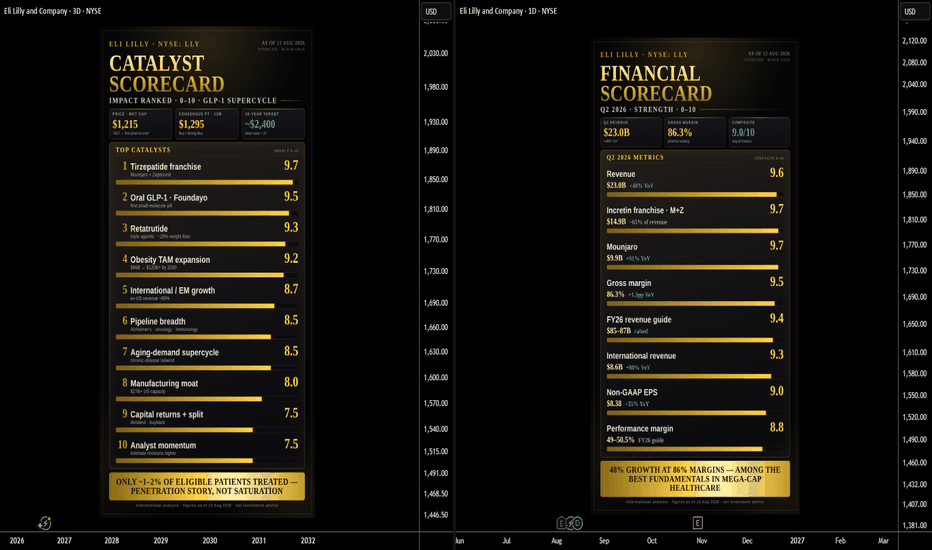
BTCUSD H1 Institutional Liquidity Levels Bulls/Bears▪️ BTCUSD H1 SNAPSHOT — EXECUTIVE SUMMARY
▪️ Bitcoin is trading near 64,511, pressing up out of the Aug 3 demand base into a stack of overhead liquidity. Price sits just beneath the first heavy liquidity pool — only ~$190 overhead — while deep London demand waits far below. The tape is coiled at the ceiling.
▪️ Primary outlook: liquidity grab higher first, then rejection and rotation lower. — Price pushes up to sweep the overhead pools, fails to hold, then reverses down through 64,000 into demand. The dominant leg on the chart points down into the 63,580 shelf.
▪️ Key resistance zone: 64,850 → 65,400 — twin bands of heavy overhead liquidity, the reversal pocket where the up-sweep is expected to stall. Above that sits the 66,000 Bearish FVG (3/10, London).
▪️ Major defense line: 63,580 — a 9/10 STRONG London Bullish OB, the first real demand shelf and where the down arrows terminate. Beneath it lies the true floor.
▪️ Primary downside targets on a break: 64,000 midpoint → 63,580 Bullish OB, where the down leg lands and liquidity pools.
▪️ Major liquidity magnet below: 63,580 → 62,610 — the deep pull if 64,000 cracks and the 63,580 OB fails. Magnet above: 64,850 → 65,400 liquidity → 66,000 FVG.
▪️ Bullish scenario: Reclaim and hold above 65,400 liquidity, and the ceiling breaks — path opens toward the 66,000 Bearish FVG and beyond, invalidating the reversal.
▪️ Bearish scenario: Sweep the 64,850 / 65,400 liquidity, print a lower-high retest, then reject → drive back through 64,000 → sell into 63,580, with extension toward 62,950 / 62,610 demand.
▪️ KEY LEVELS
▪️ Current Price: ~64,511
RESISTANCES
▪️ 66,000 — ★ 3/10 · Bearish FVG · London · ~$1,490 away
▪️ 65,400 — ◆ Heavy overhead liquidity (upper pool) · ~$890 away
▪️ 64,850 — ◆ Heavy overhead liquidity (lower pool) · ~$340 away
SUPPORTS
▪️ 63,580 — ★★★★ 9/10 STRONG · Bullish OB · London · ~$930 away
▪️ 62,950 — ★★★ 6/10 · Bullish FVG · London · ~$1,560 away
▪️ 62,610 — ★★★★★ 10/10 STRONG · Bullish OB · London · ~$1,900 away
▪️ ORDER FLOW / ZONE MAP
▪️ Overhead supply: 64,850 liquidity → 65,400 liquidity → 66,000 Bearish FVG (3/10) — stacked sell-side pools. This is the ceiling the up-sweep runs into, and where the reversal is expected to originate.
▪️ Below demand: 63,580 Bullish OB (9/10 STRONG) → 62,950 Bullish FVG (6/10) → 62,610 Bullish OB (10/10 STRONG) — the demand shelf and deep magnet. The 62,610 OB is the highest-value reversal zone on the chart; the 63,580 OB is the first line of defense.
🔍 SCENARIO PATH
▪️ Up leg first (liquidity grab): rally from current price into 64,850 → 65,400 overhead liquidity, tagging resting sell orders.
▪️ Reversal: reject the liquidity pool, print a lower high, then break back below 64,000.
▪️ Down rotation: drive into the 63,580 Bullish OB → extend toward 62,950 / 62,610 demand where the arrows bottom out.
▪️ My read: Coiled beneath layered liquidity with deep demand waiting. This is a grab-and-reverse setup — the up-push is bait to sweep 64,850/65,400 before the real move rotates down into 63,580/62,610. The high-value long is a flush into deep demand that holds; a clean reclaim of 65,400 flips the whole picture bullish toward 66,000. Edges pay, the middle chops.
🔒 Levels and paths from the zone model. No signals, no repaint — a scenario, not a promise.
▪️ ProjectSyndicate Levels Desk — weekly S/R & liquidity zones for XAUUSD, GBPUSD, NVDA, NQ, ES & GC. Subscribe to stay up to date.
#BTCUSD #Bitcoin #Crypto #Trading Short 
Nvidia (NVDA) 2026+ Catalysts & Risks Institutional OverviewNVDA (2026+) Catalysts, Risks & Financials: Ranked Analyst Views
As of August 10, 2026. Stock ~$222–223. Consensus rating Strong Buy (58 of 61 analysts buy/strong-buy); average 12-month price target ~$302–304 (~+47% upside); range $180 (low) → $500 (high). Next earnings ~Aug 26–27, 2026 (Q2 FY2027). Latest reported quarter: Q1 FY2027 (ended Apr 26, 2026) — record revenue $81.6B (+85% YoY), Data Center $75.2B (+92% YoY).
🔑 Key Catalysts Driving NVDA (2026+)
🏗️ Blackwell Ramp + Rubin Transition (the core engine)
Blackwell is the fastest product ramp in NVIDIA's history — GB300 NVL72 demand described as "off the charts," with frontier labs and hyperscalers cumulatively deploying hundreds of thousands of GPUs. Next-gen Vera Rubin is on track for an H2 FY2027 ramp, giving a built-in upgrade cycle. Jensen Huang forecast at GTC 2026 that AI data-center revenue could reach ~$1 trillion by 2027, with ~25% upside beyond that including CPU/systems. Impact Score: 9.7/10
🌐 Data Center Dominance & Networking Explosion
Data Center is ~92% of total revenue ($75.2B in Q1 FY2027). The under-appreciated story is networking: DC networking revenue hit a record $14.8B, up 199% YoY (NVLink scale-up, Spectrum-X Ethernet, Quantum-X InfiniBand). This turns NVIDIA from a chip vendor into a full rack-scale systems supplier and deepens the moat. Impact Score: 9.5/10
🧠 CUDA Software Moat & Full-Stack Lock-In
"NVIDIA is the only platform that runs every frontier AI model" (Huang) — Anthropic, OpenAI, Meta, Google Gemini, xAI. CUDA + the systems stack create switching costs that custom silicon struggles to match, sustaining pricing power and mid-70s gross margins. Impact Score: 9/10
💵 Massive Capital Returns (Dividend + Buyback)
On May 18, 2026 the board raised the quarterly dividend 25× (from $0.01 to $0.25) and added an $80B buyback authorization (no expiration). First nine months of FY2026 already returned $37B to shareholders. Signals management confidence and provides a valuation floor. Impact Score: 8.5/10
🌍 Sovereign AI + Hyperscaler Capex Supercycle
Microsoft, Amazon, Alphabet, Meta, Oracle are guiding to ~$140B+ (some estimates $650–700B across top firms) of AI capex in 2026. Data Center is diversifying beyond hyperscale into AI Clouds, industrial, enterprise and sovereign customers (now ~50% of DC), broadening and de-risking the demand base. Impact Score: 8.5/10
🇨🇳 China Re-Opening (H200 with Revenue-Share)
The Trump administration cleared H200 exports to China under a 15–25% revenue-share ("AI tax") framework with Commerce licensing. China was ~20–25% of DC revenue pre-controls (~$10–15B/yr). Huang says demand is "very high" and hasn't ruled out Blackwell/Rubin for China "in time." Upside optionality not currently baked into guidance (management assumes $0 China DC compute in the outlook). Impact Score: 8/10
📈 Analyst Momentum & Estimate Revisions
Strong Buy consensus; targets clustering $300–330 (KeyBanc $330, Bernstein sees a break above $300). Current-year EPS estimates revised up ~7.8% in 90 days. Positive revision momentum tends to pull in institutional flows. Impact Score: 7.5/10
⚠️ Key Risks & Negative Drivers
🫧 AI-Bubble / Circular-Financing Thesis
The loudest bear case. Michael Burry disclosed sizable NVDA puts (Jul 2026), arguing much demand is vendor-financed and off-balance-sheet, with "future revenues majority financed in a circular arrangement." NVIDIA has announced >$540B of circular-financing deals in 2026 (Bloomberg). BofA's semiconductor Bubble Risk Indicator hit 0.91; IMF and BIS both flagged AI circular financing as a systemic risk. Mark Cuban compared it to the dot-com burst. Risk Severity: 8.5/10
💸 Valuation & Concentration Risk
Multi-trillion-dollar market cap (~$5T) priced for sustained hypergrowth. Magnificent-7 shed >$2.2T in June 2026 alone; NVDA lost ~$250B cap in a single July session on bubble fears. Any guidance wobble → sharp de-rating. Semiconductor ETF (SOXX) trading at ~76× P/E. Risk Severity: 8/10
🇨🇳 China Policy Whiplash & The "AI Tax"
Even with H200 clearance, the 15–25% revenue-share erodes margins, Beijing is reportedly limiting approved buyers, and $0 China DC compute is currently in guidance — a reminder of how fast policy can swing (Q1 FY26 had $4.6B China Hopper; Q1 FY27 had none). Blackwell/Rubin access remains uncertain. Risk Severity: 7.5/10
🥊 Competitive Pressure (AMD + Custom Silicon)
AMD's MI400/MI450 + Helios racks (incl. the Anthropic 2GW deal) are a credible #2, and hyperscaler custom silicon (Google TPU, AWS Trainium, Microsoft Maia) targets the same TAM. Sustained share/margin defense is not guaranteed as buyers seek second sources. Risk Severity: 7/10
📉 Depreciation & Chip-Obsolescence Accounting
Burry's secondary thesis: if AI GPUs have a real 2–3 year useful life, hyperscalers' extended depreciation schedules inflate reported profits and mask deteriorating ROI on AI capex — which could slow the capex supercycle NVIDIA depends on. Risk Severity: 6.5/10
⚡ Rising Costs, Inventory & Commitments
GAAP opex +52% YoY to $7.6B; inventory $25.8B; supply/purchase commitments $119.0B. Aggressive capacity build-out raises execution and write-down risk if demand ever hesitates (the balance-sheet-expansion factor analysts flag). Risk Severity: 6/10
🔀 Near-Term Earnings Volatility
Even blowout prints have sold off on "whisper" expectations (the stock slid despite DC nearly doubling in Q1 FY27). The Aug 26 report is a binary event around Blackwell demand, margins and Rubin timing. Risk Severity: 5.5/10
💰 Financial Scorecard (Q1 FY2027, ended Apr 26, 2026)
Each metric scored 0–10 on strength/quality relative to expectations and trajectory.
# Metric Latest Value Trend Financial Strength
F1 Revenue $81.6B +85% YoY, +20% QoQ, 3rd straight quarter of accelerating YoY growth 9.8
F2 Data Center Revenue $75.2B +92% YoY, +21% QoQ; ~92% of total 9.8
F3 DC Networking $14.8B +199% YoY, +35% QoQ 9.7
F4 Free Cash Flow $48.6B Record; FCF margin ~60% 9.7
F5 Non-GAAP Gross Margin ~75% Mid-70s sustained; guided 75.0% next Q 9.5
F6 Operating Cash Flow $50.3B Up from $27.4B YoY (+84%) 9.5
F7 Operating Margin ~66% Highest in trailing 8 quarters 9.5
F8 Non-GAAP EPS $1.87 +140% YoY 9.4
F9 Next-Q Guidance ~$91.0B ±2% Implies continued sequential acceleration, assumes $0 China 9.3
F10 Capital Returns $0.25 div + $80B buyback Dividend up 25×; huge new authorization 8.8
F11 Balance-Sheet Expansion Inventory $25.8B; commitments $119.0B; opex +52% Rising obligations = quality watch-item 6.5
Financial composite (avg of F1–F11): ~9.2/10 — exceptional top-line, margins and cash generation; the only soft spot is the fast-expanding balance sheet and supply commitments.
🏆 Master Ranking — Catalysts, Financials & Risks Combined
Positive drivers (catalysts + financial strengths) ranked by score. Risks listed separately as deductions.
Rank Driver Type Score (0–10)
1️⃣ 📊 Revenue $81.6B (+85% YoY, accelerating) Financial 9.8
1️⃣ 🏢 Data Center $75.2B (+92% YoY) Financial 9.8
3️⃣ 🌐 DC Networking +199% YoY Financial 9.7
3️⃣ 💵 Free Cash Flow $48.6B (record) Financial 9.7
5️⃣ 🏗️ Blackwell ramp + Rubin transition Catalyst 9.7
6️⃣ 🌐 Data-center dominance & networking moat Catalyst 9.5
6️⃣ 📈 Non-GAAP gross margin ~75% Financial 9.5
6️⃣ 💵 Operating cash flow $50.3B Financial 9.5
6️⃣ ⚙️ Operating margin ~66% Financial 9.5
10️⃣ 🧠 CUDA software moat / full-stack lock-in Catalyst 9.0
10️⃣ 📑 Next-Q guidance ~$91B Financial 9.3
12️⃣ 💵 Capital returns (div + $80B buyback) Catalyst 8.5
13️⃣ 🌍 Sovereign AI + hyperscaler capex supercycle Catalyst 8.5
14️⃣ 🇨🇳 China re-opening (H200, optionality) Catalyst 8.0
15️⃣ 📈 Analyst momentum & estimate revisions Catalyst 7.5
⚠️ Risk Ledger (severity-ranked)
Rank Risk Severity (0–10)
1️⃣ 🫧 AI-bubble / circular-financing thesis 8.5
2️⃣ 💸 Valuation & concentration risk 8.0
3️⃣ 🇨🇳 China policy whiplash + "AI tax" margin drag 7.5
4️⃣ 🥊 Competition (AMD MI400/450, custom silicon) 7.0
5️⃣ 📉 Depreciation / chip-obsolescence accounting 6.5
6️⃣ ⚡ Rising costs, inventory & $119B commitments 6.0
7️⃣ 🔀 Near-term earnings volatility 5.5
📝 Summary Outlook (August 2026)
NVIDIA enters H2 CY2026 as the single most important company in the AI buildout — record $81.6B revenue, Data Center up 92%, ~75% gross margins, and $48.6B of quarterly free cash flow that funds a 25× dividend hike and an $80B buyback. The Blackwell → Rubin cadence plus a 199%-growth networking business and the CUDA moat give it a durable, full-stack lead, and China H200 re-opening is pure optionality not yet in guidance. Analysts remain overwhelmingly bullish (Strong Buy, ~$302 target).
The bear case is no longer about demand — it's about how that demand is financed. Burry, Cuban, the IMF and BIS all point at circular vendor-financing (>$540B in 2026 deals), aggressive depreciation math, and a semiconductor bubble indicator at 0.91. With a ~$5T cap priced for perfection, valuation leaves little room for error, and China policy remains a two-way swing factor.
Bottom line: fundamentals are as strong as any mega-cap in history (financial composite ~9.2/10), but the risk isn't operational execution — it's whether the AI-capex flywheel is self-sustaining or self-referential. The Aug 26 print (Blackwell demand, margins, Rubin timing, any China commentary) is the next decisive catalyst.
Sources: NVIDIA Q1 FY2027 & Q4/Q3 FY2026 press releases and CFO commentary (SEC 8-K, nvidianews.nvidia.com); CNBC, TIKR, StockTitan, S&P Global, IG, Futurum (earnings); Public.com, StockAnalysis, MarketBeat, Finbold/KeyBanc, Watcher.Guru/Bernstein (targets/ratings); TheStreet, Blockonomi, GuruFocus, TradingKey, Yahoo Finance (Burry/Cuban bubble thesis); TechPowerUp, Tom's Hardware, tech-insider (China/H200). Long 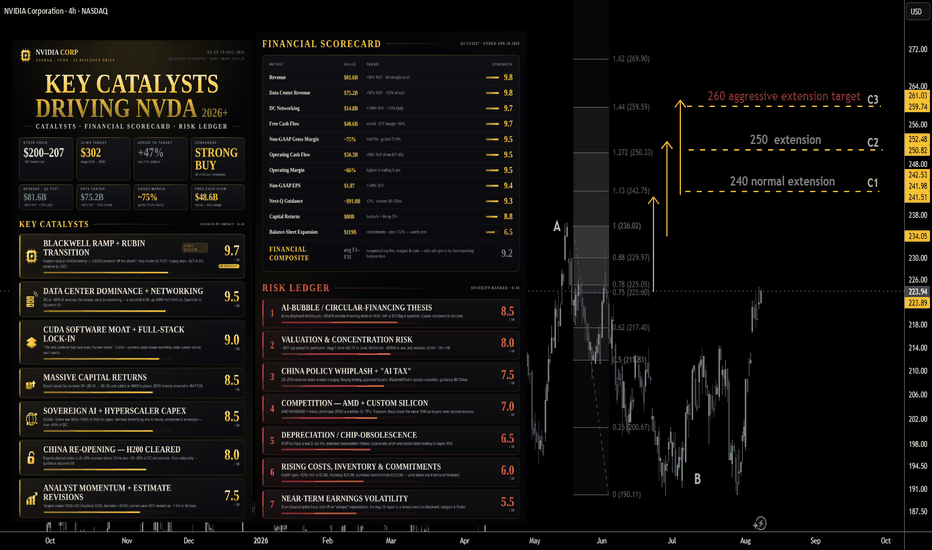
RACE: Ferrari Bulls are in in control next target is 400 USD▪️ RACE / FERRARI — THE RECLAIM IS DONE. NEXT STOP IS THE 400 LIQUIDITY POOL. 🐎
▪️ Ferrari is pressing higher near 357, having already reclaimed its very-strong floor and turned it into a launch pad. Price is out of the base and climbing — this isn't a "will it hold" chart, it's a "how far does the run go" chart, and the answer sitting overhead is 400, where the biggest sell-side pool on the board rests.
▪️ Primary outlook: bullish continuation — reclaim confirmed, liquidity run in progress. The path of least resistance is up, with one intermediate wall to clear before the 400 target comes into range.
▪️ Key resistance zone: 376–384 — a ★★ 6.2/10 MODERATE wall leaned on 15 times, the one real speed bump between price and the target. Clear it and the lane to 400 opens.
▪️ Final target overhead: 400–408 — the Bear Liquidity Cluster (POWER 9/10, 13.81% depth), the "400 USD TP" for bulls. This is where trapped short liquidity and resting sell orders pool — in a bullish run, that cluster isn't resistance to fear, it's the magnet to aim at. Bulls hunt the sell-side.
▪️ Major defense line: 345–350 — a ★★★★ 8.1/10 VERY STRONG support at 10 retests, the freshly reclaimed floor and the line that keeps the bullish read alive. Lose it and the momentum thesis stalls.
▪️ Primary upside targets: clear 376–384 → 400 (Bear Cluster POWER 9/10).
▪️ Structural invalidation: a daily close back below 345 flips continuation into range, opening 329 → 305–313.
▪️ Bullish scenario (primary — yellow paths): hold above the reclaimed 345–350 floor → grind through the 376–384 moderate wall → drive into the 400–408 Bear Liquidity Cluster where the sell-side pool gets eaten. The staged run: floor → mid-wall → the pool. That's the 400 USD TP.
▪️ Bearish scenario (invalidation only): rejection before 376 and a loss of 345–350 → pullback into 329 (5.1 WEAK) and 305–313 (6.9 MODERATE). Deep invalidation is the 281–289 Bull Liquidity Cluster — the structural demand shelf that only comes into play if the whole reclaim unwinds.
▪️ KEY LEVELS
▪️ Current Price: ~357
RESISTANCES
▪️ 400–408 — Bear Liquidity Cluster · POWER 9/10 · 13.81% depth · final target / "400 USD TP BULLS" (sell-side pool)
▪️ 376–384 — ★★ 6.2/10 MODERATE · 15 retests · intermediate wall
SUPPORTS
▪️ 345–350 — ★★★★ 8.1/10 VERY STRONG · 10 retests · reclaimed floor / launch pad
▪️ 329 — ★ 5.1/10 WEAK · 5 retests
▪️ 305–313 — ★★ 6.9/10 MODERATE · 13 retests
▪️ 281–289 — Bull Liquidity Cluster · POWER 8/10 · 20.36% depth · deep demand magnet (structural)
▪️ 271–278 — ★★ 6.5/10 MODERATE · 12 retests
▪️ LIQUIDITY CLUSTER MAP
▪️ Overhead (sell-side pool): 400–408 — Bear Cluster POWER 9/10, 13.81% — the highest-value objective on the board and the target of this run. In an uptrend this is where price gets pulled: trapped shorts above 400 become fuel, and the resting sell orders are the liquidity bulls are driving toward. ~+12–13% from current.
▪️ Below (buy-side pool): 281–289 — Bull Cluster POWER 8/10, 20.36% — the deepest pool on the chart (biggest % depth) and the ultimate demand shelf. It's the catastrophe magnet, not an active level — only relevant if the reclaim fully fails. ~-20% from current.
▪️ The asymmetry: the active magnet is overhead (bear pool at 400), the safety-net magnet is far below (bull pool near 285). That's a bullish structure — the near-term pull is up.
🔍 THE SCENARIO PATH
▪️ Yellow legs (the run — primary): from 357, hold the 345–350 reclaimed floor → push through the 376–384 moderate wall (first checkpoint) → extend into the 400–408 Bear Liquidity Cluster (final TP). Two staged yellow arrows: the first clears the mid-wall, the second delivers into the pool. A multi-week traverse on the Daily, roughly +12% top to bottom of the move.
▪️ Invalidation leg (only if 345 breaks): step-down through 329 → 305–313, with the 281–289 Bull Cluster as the deep catch. Not the base case while the reclaim holds.
▪️ My read: The hard part already happened — reclaiming the 8.1 very-strong floor is what turns a bounce into a trend, and that's done. From here it's a liquidity run: the 400 Bear Cluster is a magnet, not a wall, because pools like that pull price in before they reverse. The high-value long is the continuation while 345–350 holds beneath; the 376–384 wall is the only friction between here and target. Structure stays bullish above 345 — that's the one number that matters. Lose it and this becomes a range again; hold it and 400 is the draw.
🔒 Levels and paths from the zone model. No signals, no repaint — a scenario, not a promise.
▪️ ProjectSyndicate Levels Desk — Overview of key S/R zones for XAUUSD, NVDA, NQ, ES & GC traders every week. Subscribe to stay up to date with the latest levels.
#RACE #Ferrari #Stocks #Trading  Long

USDSGD H4 Institutional Liquidity Levels Bulls/Bears▪️ USDSGD — THE FLUSH IS THE SETUP. BUY THE SPRING, NOT THE PANIC. 🩸
▪️ The Singapore dollar pair is drifting near 1.28214, sitting mid-range after rejecting the 1.28400 shelf. Price is coiled between a very-strong floor just below and a stack of strong resistance overhead — the setup here isn't the chop, it's the dip that comes before the launch.
▪️ Primary outlook: pullback before strong reversal — bullish once the flush is bought. The base case is a drop that sweeps the floor, holds, and reverses hard back up through the range.
▪️ Key resistance zone: 1.28380–1.28450 — a ★★★ 7.9/10 STRONG wall leaned on 67 times, the first ceiling and the first reversal target. Final objective overhead: 1.28850–1.28920 — a ★★★ 7.8/10 STRONG zone worn 23 times, the top of the range.
▪️ Major defense line: 1.27850–1.27920 — a ★★★★ 8.3/10 VERY STRONG support at 40 retests, the first real floor. But the primary path doesn't stop there — it sweeps through it into 1.27450–1.27520, a ★ 4.7/10 WEAK zone that's been tapped 76 times. Low star rating, highest retest count on the board — that contradiction is the whole trade. That's the decision zone, not the weak spot it's labeled as.
▪️ Primary reversal trigger: 1.27500 — sweep the 8.3 floor, tag the 76-retest magnet, then reclaim.
▪️ Primary upside targets on the flip: 1.27900 reclaim → 1.28400 → 1.28900.
▪️ Structural invalidation: losing 1.27200 (★ 5.1/10 WEAK · 29 retests) kills the bullish read and opens a deeper leg.
▪️ Bullish scenario (primary — gray flush → yellow reversal): rejection near 1.28400, pullback that sweeps the 1.27900 very-strong support into the 1.27500 magnet → hold / spring → drive back up through 1.27900 and 1.28400 → target 1.28900. The false breakdown below the 8.3 floor is where trapped shorts become fuel.
▪️ Bearish scenario (invalidation): 1.27500 fails to hold on the sweep → continuation into 1.27200 (5.1 WEAK) and the bullish thesis is off until price reclaims 1.27900. Below the middle, the floor stops being a spring and starts being a trapdoor.
▪️ KEY LEVELS
▪️ Current Price: ~1.28214
RESISTANCES
▪️ 1.28850–1.28920 — ★★★ 7.8/10 STRONG · 23 retests · range top / final reversal target
▪️ 1.28380–1.28450 — ★★★ 7.9/10 STRONG · 67 retests · first ceiling / first reversal target
SUPPORTS
▪️ 1.27850–1.27920 — ★★★★ 8.3/10 VERY STRONG · 40 retests · first floor (swept in the primary path)
▪️ 1.27450–1.27520 — ★ 4.7/10 WEAK · 76 retests · the magnet / reversal trigger (most-tested level on the board)
▪️ 1.27145–1.27260 — ★ 5.1/10 WEAK · 29 retests · structural invalidation
▪️ ZONE MAP
▪️ Overhead: 1.28400 (~0.15% / ~19 pips) → 1.28900 (~0.53% / ~69 pips) — the 67-retest wall then the range lid; both have to be reclaimed for trend-up to confirm.
▪️ Below: 1.27900 (~0.24% / ~31 pips) → 1.27500 (~0.56% / ~71 pips) → 1.27200 (~0.79% / ~101 pips) — the very-strong floor, the 76-retest magnet beneath it, and the last-line invalidation.
🔍 THE SCENARIO PATH
▪️ Bearish leg (the pullback): from 1.28214, roll down through the 1.27900 very-strong support and into the 1.27500 magnet. This is a sweep, not a trend change — the strong floor gets pierced to grab resting liquidity below.
▪️ Bullish leg (the reversal): from 1.27500, spring back up → reclaim 1.27900 → break 1.28400 (first target, 7.9 STRONG) → extend into 1.28850–1.28920 (final target, 7.8 STRONG). Full reversal leg is ~140 pips / ~1.10%, a multi-session traverse on H4.
▪️ My read: This is a spring, not a breakdown. The tell is the 1.27500 level — 76 taps and still holding despite the weak label, which is exactly what a genuine accumulation floor looks like on the tape. The high-value long is the sweep that reclaims: let price flush through the 8.3 support, tag 1.27500, and only trust it once 1.27900 is back overhead. Buying the panic candle into the floor is the trap; buying the reclaim is the trade. Lose 1.27200 and none of this applies — that's the line that flips the whole idea.
🔒 Levels and paths from the zone model. No signals, no repaint — a scenario, not a promise.
▪️ ProjectSyndicate Levels Desk — Overview of key S/R zones for Forex, Metals, Indices, NVDA, NQ, ES & GC traders every week. Subscribe to stay up to date with the latest levels.
#USDSGD #Forex #Trading USDCHF H2 Institutional Liquidity Levels Bulls/Bears▪️ USDCHF — BOXED IN. BOTH EDGES ARE LOADED. 🩸
▪️ Swissy is rotating near 0.80864, fair-valued in the upper half of a tight, heavily-tested range. Price is pinned between a strong lid above and the single heaviest floor on the board below — the box holds until one edge breaks.
▪️ Primary outlook: range-bound, compression before expansion. — 0.80640 is the near defense; 0.80960 is the near lid. The broad range (0.80330 → 0.81200) is intact until a clean break resolves it.
▪️ Key resistance zone: 0.81150–0.81200 — a ★★★ 7.7/10 STRONG wall, leaned on 7 times. This is the ceiling both scenarios point to. Intermediate resistance: 0.80920–0.80960 — a ★ 5.6/10 WEAK shelf worn 29 times; a speed bump, not a wall.
▪️ Major defense line: 0.80600–0.80640 — a ★★ 6.5/10 MODERATE support at 21 retests, the first floor. True structural floor: 0.80330–0.80360 — a ★★★ 7.8/10 STRONG zone tested 74 times, by far the most respected level here and the deep magnet below.
▪️ Primary downside targets on a break: 0.80640, then 0.80330–0.80360 where resting demand is deepest.
▪️ Primary upside targets on a reclaim: 0.80960, then 0.81150–0.81200.
▪️ Bullish scenario (maroon path): Sweep the lows into 0.80330–0.80360, trap the breakout sellers, then reverse up through 0.80640 → 0.80960 → drive the 0.81150–0.81200 lid (Bullish Target). The floor giving a false break is where the highest-value long sets up.
▪️ Bearish scenario (yellow path): Pop into 0.81150–0.81200, get rejected off the strong wall, then flush back through 0.80960 → 0.80640 → into the 0.80330–0.80360 floor (Bearish Scenario). The lid rejection is the short trigger.
▪️ KEY LEVELS
▪️ Current Price: ~0.80864
RESISTANCES
▪️ 0.81150–0.81200 — ★★★ 7.7/10 STRONG · 7 retests · scenario ceiling / Bullish Target
▪️ 0.80920–0.80960 — ★ 5.6/10 WEAK · 29 retests · intermediate shelf
SUPPORTS
▪️ 0.80600–0.80640 — ★★ 6.5/10 MODERATE · 21 retests · first floor
▪️ 0.80330–0.80360 — ★★★ 7.8/10 STRONG · 74 retests · structural floor / Bearish Target
▪️ ZONE MAP
▪️ Overhead: 0.80960 (~0.09% / ~8 pips) → 0.81150–0.81200 (~0.38% / ~31 pips) — the weak shelf then the strong lid that has to be eaten before trend-up confirms.
▪️ Below: 0.80640 (~0.30% / ~24 pips) → 0.80330–0.80360 (~0.64% / ~52 pips) — the near defense then the 74-retest floor, the highest-value reversal zone on the board.
🔍 THE SCENARIO PATH
▪️ Bearish path (up-first, bearish resolve): from 0.80864, rotation up into the 0.81150–0.81200 wall → rejection → step down through 0.80960 and 0.80640 → settle into the 0.80330–0.80360 floor. Edge-sweep on the topside first, then the full range traverse lower.
▪️ Bullish path (down-first, bullish resolve): from 0.80864, flush down into the 0.80330–0.80360 floor → hold / bear trap → reversal back up through 0.80640 and 0.80960 → target the 0.81150–0.81200 lid. Rough full-rotation window ~2 weeks on H2, with the edge sweep landing in the first several sessions.
▪️ My read: Compressed range, price sitting mid-to-upper with a much deeper, better-defended floor (74 retests) than lid (7 retests). That asymmetry says a sweep into 0.80330–0.80360 that holds is the high-value long; a clean rejection at 0.81150–0.81200 is the clean short. The edges pay, the middle chops — don't get chopped up trading the 0.80640–0.80960 no-man's-land.
🔒 Levels and paths from the zone model. No signals, no repaint — a scenario, not a promise.
▪️ ProjectSyndicate Levels Desk — Overview of key S/R zones for metals, FX. indices, NVDA, NQ, ES & GC traders every week. Subscribe to stay up to date with the latest levels.
#USDCHF #Forex #Trading GBPUSD H1 Institutional Liquidity Levels Bulls/Bears1️⃣ TRADINGVIEW POST (long-form)
▪️ GBPUSD H1 SNAPSHOT — EXECUTIVE SUMMARY
▪️ Cable is trading near 1.34339, pinned directly beneath a fresh Bearish FVG and stacked supply, while a wall of institutional demand sits far below. Price is compressed at the decision point — the first rejection zone is only 9 pips away.
▪️ Primary outlook: rejection lower first, then rotation up. — 1.3436 is the trigger above; the maroon path expects a flush down into demand before the yellow recovery legs fire.
▪️ Key resistance zone: 1.3510 — a 10/10 STRONG London Bearish OB, 306 bars old, the heaviest supply on the board. Above sit two Asian Bearish FVGs at 1.3530 and 1.3550.
▪️ Major defense line: 1.3330 — an 8/10 Asian Bullish FVG and the first real demand shelf, backed by the 1.3294 London Bullish OB (10/10 STRONG), the structural floor.
▪️ Primary downside targets on a break: 1.3370 midpoint → 1.3330 Bullish FVG, where the maroon arrows terminate and liquidity pools.
▪️ Major liquidity magnet below: 1.3330–1.3294 — the pull if 1.3357 Bearish BB cracks. Magnet above: 1.3436 → 1.3510.
▪️ Bullish scenario: Reclaim 1.3436 and hold, and the yellow path opens toward 1.34677, then extended supply at 1.3510.
▪️ Bearish scenario: Reject the 1.3436 Bearish FVG → drive through the 1.3357 Bearish BB → sweep into 1.3330 / 1.3294 demand, then bull trap reversal.
▪️ KEY LEVELS
▪️ Current Price: ~1.34339
RESISTANCES
▪️ 1.3550 — ★★★ 6/10 · Bearish FVG · Asian · 125 pips away
▪️ 1.3530 — ★ 3/10 · Bearish FVG · Asian · 92 pips away
▪️ 1.3510 — ★★★★★ 10/10 STRONG · Bearish OB · London · 306 bars · 73 pips away
▪️ 1.3436 — ★ 3/10 · Bearish FVG · Asian · 9 pips away
SUPPORTS
▪️ 1.3357 — ★★★★ 8/10 · Bearish BB · 804 bars (flip zone)
▪️ 1.3330 — ★★★★ 8/10 · Bullish FVG · Asian · 107 pips away
▪️ 1.3294 — ★★★★★ 10/10 STRONG · Bullish OB · London · 88 bars · 146 pips away
▪️ ORDER FLOW / ZONE MAP
▪️ Overhead supply: 1.3436 FVG → 1.3510 London OB (10/10) → 1.3530/1.3550 FVGs — layered sell-side, the ceiling that must break for trend up.
▪️ Below demand: 1.3357 Bearish BB (8/10 flip) → 1.3330 Bullish FVG (8/10) → 1.3294 London OB (10/10) — the demand shelf and deep magnet. The 1.3294 OB is the highest-value reversal zone on the chart.
🔍 SCENARIO PATH
▪️ Maroon leg first: rejection from 1.3436 → break 1.3357 BB → drive into 1.3330 Bullish FVG.
▪️ Yellow rotation: from 1.3330 demand → recovery back through 1.3357 → target 1.34677 → 1.3510 supply.
▪️ My read: Coiled beneath supply with deep demand waiting. This is a reject-and-reverse setup — a flush into 1.3330/1.3294 that holds is the high-value long; a clean reclaim of 1.3436 flips bias early and opens 1.34677+. Edges pay, the middle chops.
🔒 Levels and paths from the zone model. No signals, no repaint — a scenario, not a promise.
▪️ ProjectSyndicate Levels Desk — weekly S/R & liquidity zones for XAUUSD, GBPUSD, NVDA, NQ, ES & GC. Subscribe to stay up to date.
#GBPUSD #Cable #Forex #Trading EURUSD H1: Weekly High Swept, Then Reclaimed 🔥 EURUSD H1: Weekly High Swept, Then Reclaimed — 1.14840 Is the Only Line Left
▪️ EURUSD H1 SNAPSHOT — EXECUTIVE SUMMARY
▪️ The Euro trades at 1.14765, back above a weekly high it swept and initially rejected from. The prior week's high at 1.14500 graded 6.7/10 Strong and is tagged Swept — stops were taken, price closed back inside, and buyers have since pushed through it again.
▪️ Primary outlook is cautiously bullish, but unconfirmed. A sweep that gets reclaimed is only a breakout once it closes beyond acceptance. Until then this is still the trap band.
▪️ The decision level: 1.14840. A close above it converts the failed sweep into a genuine weekly break and opens 1.14950.
▪️ What holds it up: the reclaimed 1.14500 is now the line in the sand beneath price, with 1.14590 as the immediate stop-run reference.
▪️ Failure case: losing 1.14500 again puts the golden pocket at 1.14150–1.14100 back in play, then 1.13640 at 5.0/10 Moderate.
▪️ Below all of it, 1.13230 is an untouched weekly low — unfinished business and the deepest magnet on the chart.
▪️ Bearish scenario: rejection at 1.14840 with a close back under 1.14500 turns this into a failed break, historically the highest-conviction reversal condition this framework prints.
▪️ KEY LEVELS
RESISTANCEs
▪️ 1.14950 — Range Extension Target
▪️ 1.14840 — Acceptance Level
▪️ Current Price: 1.14765
SUPPORTs
▪️ 1.14590 — Sweep Trap Level
▪️ 1.14500 — ★★★ 6.7 Strong · Swept → reclaimed
▪️ 1.14150–1.14100 — Golden Pocket / Equilibrium 50%
▪️ 1.13800 — filled weekly gap
▪️ 1.13640 — ★★ 5.0 Moderate · Intact
▪️ 1.13540 — Sweep Trap Level
▪️ 1.13230 — Acceptance Level / Virgin PWL
▪️ ProjectSyndicate Levels Desk — Overview of key weekly zones for EURUSD, XAUUSD, ES, BTC & XAGUSD traders every week. Subscribe to stay up to date with the latest levels.
▪️ Get the same weekly levels plotted on your own chart with the free TradingView indicator
▪️ XAUUSD H2: Bear Trap Reversal 3955 USD▪️ XAUUSD H2 SNAPSHOT — EXECUTIVE SUMMARY
▪️ Gold is rotating near 4,039.77 inside a well-worn range, respected on both sides. Price is fair-valued between supply and demand.
▪️ Primary outlook: range bound conditions.— 4,022.50 is the level to watch; the range holds until it doesn't.
▪️ Key resistance zone: 4,081.50, leaned on 7 times. Above that sits 4,120.50 as the extended ceiling.
▪️ Major defense line: 4,022.50 — a very strong level at 23 retests, the floor that has repeatedly turned price.
▪️ Primary downside targets on a break: 3,959.50, where liquidity pools.
▪️ Major liquidity magnet below: 4,022.50–3,959.50 — the pull if the floor cracks.
▪️ Bullish scenario: Reclaim 4,081.50 and 4,120.50 becomes the objective bulls want.
▪️ Sweep or Recent lows and then reversal / bear trap at:near 3955 USD
▪️ KEY LEVELS
▪️ Current Price: 4,039.77
RESISTANCEs
▪️ 4,120.50 — ★★★★ 8.6 Very Strong · 19 retests
▪️ 4,081.50 — ★★ 6.0 Moderate · 7 retests
SUPPORTs
▪️ 4,022.50 — ★★★★ 8.1 Very Strong · 23 retests
▪️ 3,959.50 — ★ 5.9 Weak · 3 retests
▪️ ProjectSyndicate Levels Desk — Overview of key S/R zones for XAUUSD, NVDA, NQ, ES & GC traders every week. Subscribe to stay up to date with the latest levels. Long 
BTCUSD H1: Weekly Low Swept at 63,662 — Now 65,300 Caps bounce📊 BTCUSD H1: Weekly Low Swept at 63,662 — Now 65,300 Caps the Bounce
▪️ BTCUSD H1 SNAPSHOT — EXECUTIVE SUMMARY
▪️ Bitcoin trades at 64,735 after sweeping the previous week's low. That level graded 5.4/10 Moderate at 63,662 and is tagged Swept — price pushed under it, took stops down to 63,150, and closed back inside. The rejection has carried roughly a thousand handles.
▪️ Primary outlook is neutral with a constructive tilt. The sweep worked, but the bounce has not yet reached equilibrium — this is recovery, not trend.
▪️ First real test: the golden pocket at 65,500–65,300. Weekly equilibrium sits at the top of it, and mean-reversion bounces routinely stall exactly here.
▪️ Above that, 66,921 at 6.2/10 Moderate is the prior week's high, with the untouched 67,300 stacked just beyond it.
▪️ Support structure: 63,662 is the reclaimed shelf. Losing it a second time invalidates the sweep and exposes 61,902.
▪️ Deepest draw: 61,720 and 61,275 are both virgin weekly levels — never traded into, and the strongest magnets on the chart if the bid fails.
▪️ Bearish scenario: rejection at 65,300 followed by a close back under 63,662 turns the successful sweep into a failed one, and the untouched levels below become the objective.
▪️ KEY LEVELS
RESISTANCEs
▪️ 68,683 — Acceptance Level
▪️ 68,500 — Range Extension Target
▪️ 67,394 — Sweep Trap Level
▪️ 67,300 — Virgin PWH · never tagged
▪️ 66,921 — PWH ★★ 6.2 Moderate · Intact
▪️ 65,500–65,300 — Golden Pocket / Equilibrium 50%
▪️ Current Price: 64,735
SUPPORTs
▪️ 63,662 — PWL ★★ 5.4 Moderate · Swept → reclaimed
▪️ 63,588 / 63,198 — Sweep Trap Level
▪️ 61,902 — Acceptance Level
▪️ 61,720 / 61,275 — Virgin PWL · never tagged
▪️ ProjectSyndicate Levels Desk — Overview of key weekly zones for BTC, XAUUSD, ES, EURUSD & XAGUSD traders every week. Subscribe to stay up to date with the latest levels.
▪️ Get the same weekly levels plotted on your own chart with the free TradingView indicator
▪️ Long 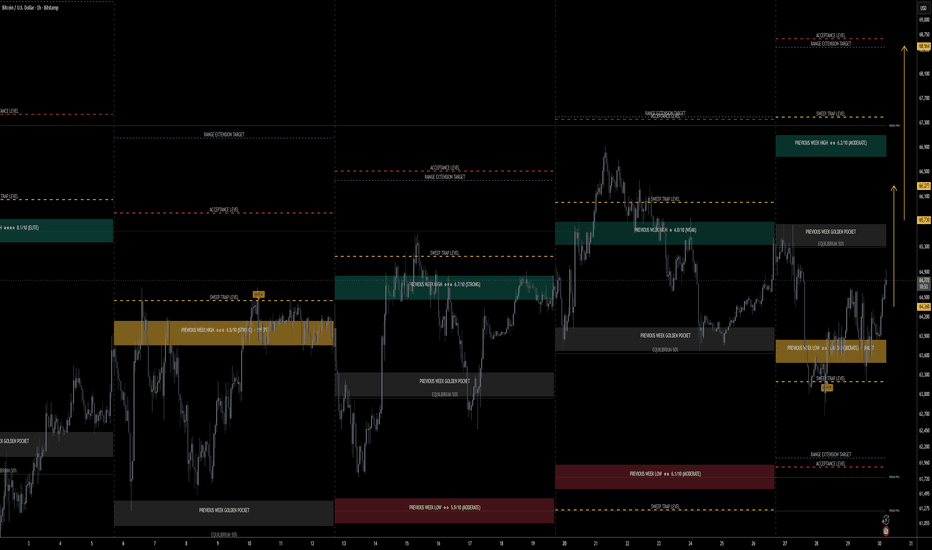
ES H1: Last Week's Low Already Broke⚡ ES H1: Last Week's Low Already Broke — the 7,397 Retest Decides 7,563 or 7,335
▪️ ES H1 SNAPSHOT — EXECUTIVE SUMMARY
▪️ The S&P 500 is at 7,397.75, back underneath a weekly low it has already lost. The prior week's low at 7,412 graded just 4.6/10 Weak — and weak levels break. It was accepted through, price extended to the downside, and this is the retest from below.
▪️ Primary outlook is bearish-while-below 7,412. That broken shelf is now overhead supply, not support. This is the cleanest structural read on the desk this week.
▪️ Overhead: 7,412 caps it first, then the golden pocket at 7,500–7,490, with 7,563 at 7.5/10 Strong as the level that actually matters. Above there sit two untouched weekly highs at 7,632 and 7,649.
▪️ Immediate pivot: 7,397 — the stop-run band price is resting on right now. Holding it keeps the retest alive; losing it resumes the move.
▪️ Downside objectives: 7,355 on a confirmed close, then 7,335 as the measured range-extension target.
▪️ Liquidity note: the weekly opening gap has already filled at 7,470, so there is no unfinished business overhead until 7,632.
▪️ Bullish scenario: reclaim 7,412 and close back above it, and the broken low flips back to support — that opens 7,490 and then 7,563.
▪️ KEY LEVELS
RESISTANCEs
▪️ 7,649 / 7,632 — Virgin PWH · never tagged
▪️ 7,620 — Acceptance Level
▪️ 7,579 — Sweep Trap Level
▪️ 7,563 — PWH ★★★ 7.5 Strong · Intact
▪️ 7,500–7,490 — Golden Pocket / Equilibrium 50%
▪️ 7,412 — ★ 4.6 Weak · Accepted → flipped overhead
▪️ Current Price: 7,397.75
SUPPORTs
▪️ 7,397 — Sweep Trap Level
▪️ 7,355 — Acceptance Level
▪️ 7,335 — Range Extension Target
▪️ ProjectSyndicate Levels Desk — Overview of key weekly zones for ES, XAUUSD, EURUSD, BTC & XAGUSD traders every week. Subscribe to stay up to date with the latest levels.
▪️ Get the same weekly levels plotted on your own chart with the free TradingView indicator
▪️ Short 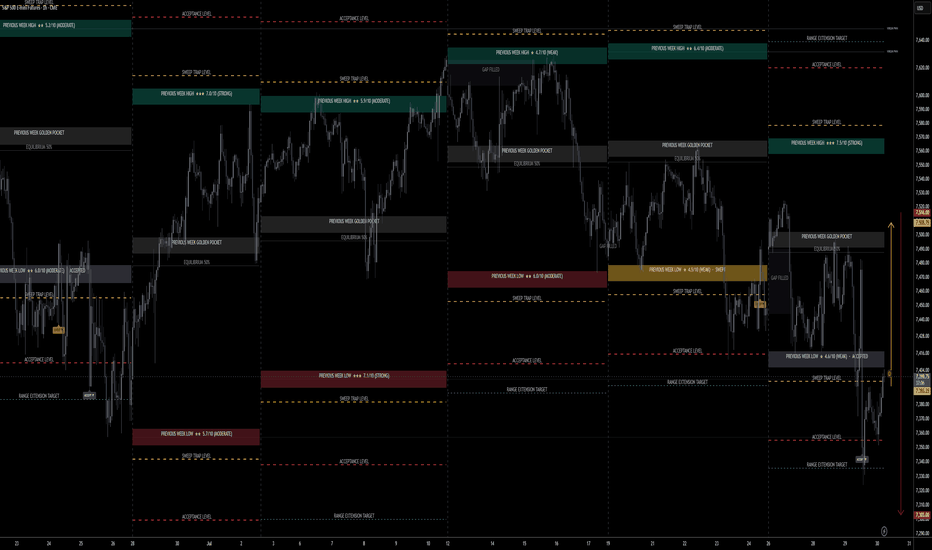
XAGUSD H1: Silver Slipped Under Weekly Equilibrium🎯 XAGUSD H1: Silver Slipped Under Weekly Equilibrium — 60.93 Ceiling vs 55.52 Shelf
▪️ XAGUSD H1 SNAPSHOT — EXECUTIVE SUMMARY
▪️ Silver is at 58.0825, a shade below the previous week's 50% equilibrium at 58.30. Price spent the week rotating around the midpoint and has come to rest just on the wrong side of it — a subtle but real loss of the range's balance point.
▪️ Primary outlook is neutral-to-soft. Nothing is broken, but the discount half of the weekly range is where price currently lives, and buyers have not reclaimed the middle.
▪️ Ceiling: 60.93 at 7.3/10 Strong, well above the market and unchallenged. 61.51 sits above it as the stop-run band. This is a level to sell into rather than expect a break of.
▪️ Reclaim level: 58.30. Getting back above the golden pocket at 58.70–58.30 is the minimum required to argue for the upper half again.
▪️ Downside: 55.52 at 5.8/10 Moderate is the weekly floor, with 54.94 beyond it as the trap band.
▪️ Note the untouched 54.85 weekly low beneath everything — never traded into, and the reason a flush here tends to overshoot rather than stop neatly at support.
▪️ Bullish scenario: reclaim and hold 58.30, and the path back toward the filled gap at 59.00 opens, with 60.93 the extended objective.
▪️ KEY LEVELS
RESISTANCEs
▪️ 61.51 — Sweep Trap Level
▪️ 60.93 — PWH ★★★ 7.3 Strong · Intact
▪️ 59.00 — filled weekly gap
▪️ 58.70–58.30 — Golden Pocket / Equilibrium 50%
▪️ Current Price: 58.2125
SUPPORTs
▪️ 55.52 — PWL ★★ 5.8 Moderate · Intact
▪️ 54.94 — Sweep Trap Level
▪️ 54.85 — Virgin PWL · never tagged
▪️ ProjectSyndicate Levels Desk — Overview of key weekly zones for XAGUSD, XAUUSD, ES, EURUSD & BTC traders every week. Subscribe to stay up to date with the latest levels.
▪️ Get the same weekly levels plotted on your own chart with the free TradingView indicator
▪️  Short


 Short


