PLTR (Palantir Technologies) — Q1 Blowout: AIP Fuels 85% Revenue**💡 PLTR (Palantir Technologies) — Q1 Blowout: AIP Fuels 85% Revenue Surge + Massive FY Guide Raise **
**SECTION 1 — Executive Summary** 💼
Palantir just delivered a blockbuster Q1 2026 with revenue exploding 85 percent year-over-year to $1.633 billion on explosive U.S. commercial acceleration via its Artificial Intelligence Platform while raising full-year guidance to approximately $7.66 billion implying 71 percent growth. The results underscore the company’s transition into a high-velocity AI software leader with accelerating commercial adoption that is outpacing even the most optimistic expectations. Overall rating: Strong Buy. 12-month price target: $190 (blended DCF and peer comps methodology weighting AIP-driven commercial momentum against government stability). The single biggest reason to own this stock right now is the unmatched Rule of 40 score hitting 145 percent combined with $8 billion cash war chest funding further AI platform scaling. The single biggest risk is valuation compression if commercial growth moderates or broader AI spending cools.
**SECTION 2 — Business Overview** 🏢
Palantir Technologies builds and deploys advanced data analytics and artificial intelligence platforms that help organizations integrate, analyze, and operationalize massive datasets for decision-making. Revenue breakdown (Q1 2026): U.S. commercial approximately 36 percent (up 133 percent year-over-year to roughly $595 million), U.S. government 42 percent (up 84 percent), international the remainder with overall U.S. revenue up 104 percent. Business model centers on high-margin, long-term software subscriptions and usage-based AIP licensing with strong net retention as customers expand from pilots to enterprise-wide deployments. Competitive moat derives from proprietary ontology-based data integration, battle-tested platforms (Gotham for defense/intelligence, Foundry/AIP for commercial), and the largest real-world AI deployment dataset giving it an insurmountable lead in secure, scalable enterprise AI.
**SECTION 3 — Financial Deep Dive** 📈
Key metrics (Q1 2026 ended March 31 2026 source: company earnings release May 4 2026):
Revenue: $1.633 billion (+85 percent year-over-year).
Net income: Positive on adjusted basis with strong profitability.
EPS (adjusted): $0.33 (beat consensus $0.28).
Gross margin: High 80s percent range on software leverage.
Free cash flow: $925 million in Q1 alone.
YoY growth rates: Revenue +85 percent, U.S. commercial +133 percent.
Balance sheet health: Approximately $8 billion cash and equivalents with virtually no debt and current ratio well above 2.0.
Cash flow quality: Operating cash flow conversion exceptional and aligned with GAAP trends (no red flags).
Capital allocation: Heavy investment in AIP platform R&D and go-to-market expansion with opportunistic share buybacks and no dividend.
**SECTION 4 — Growth Analysis** 🚀
Total addressable market (TAM): Global enterprise AI and data analytics software market exceeding $500 billion by 2030 with Palantir targeting the high-end secure deployment segment. Current market share: Leading position in mission-critical government and rapidly expanding in commercial with AIP now driving hundreds of new customer wins. Key growth drivers next 3-5 years: AIP platform adoption across commercial verticals (healthcare, finance, manufacturing), international expansion, and deepening government contracts. Management guidance now calls for approximately $7.66 billion FY 2026 revenue (71 percent growth) far more bullish than prior analyst consensus. Growth is overwhelmingly organic through platform expansion rather than acquisition-dependent.
**SECTION 5 — Valuation** 📊
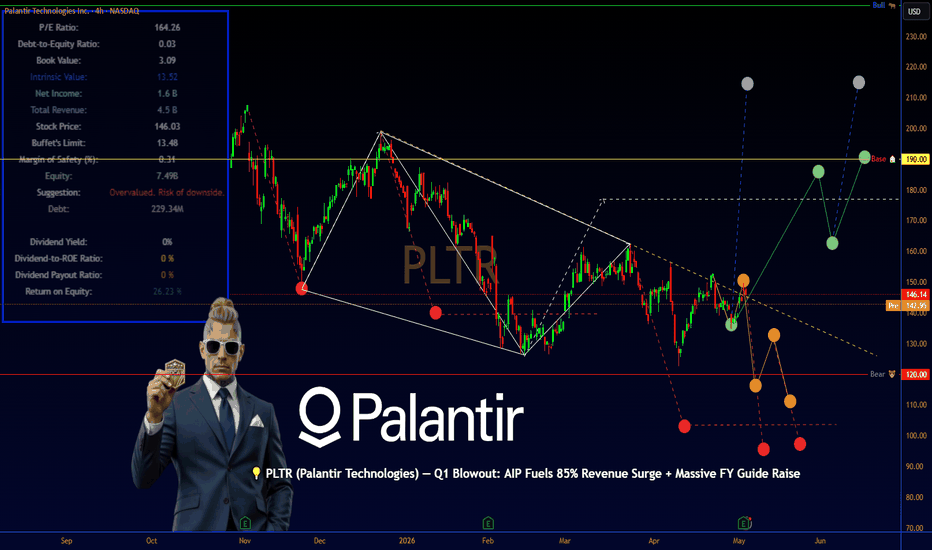
DCF analysis: Base case assumes 50-60 percent revenue CAGR through 2028 tapering to 25 percent terminal growth, 35-40 percent operating margins at scale, WACC 10 percent . Implied value supports $190 target. Comparable company analysis (peers as of May 5 2026): SNOW, CRWD, DDOG trading at 15-25x forward sales on AI growth; PLTR at premium but justified by superior profitability ramp. Historical valuation range (5-year): 20-60x sales during AI hype cycles. Bull target $240 (accelerated AIP bootcamp adoption); Base $190; Bear $120 (growth normalization). Current price ~$146 offers approximately 30 percent upside to base target.
**SECTION 6 — Risk Analysis** ⚠️
1. Valuation multiple compression (high probability/medium impact): Triggered by any slowdown in commercial beats; watch quarterly Rule of 40 trends.
2. Government contract concentration or budget shifts (medium-high): U.S. gov still ~42 percent of revenue; monitor defense spending bills.
3. Intense AI competition from hyperscalers (medium): OpenAI, Microsoft, Google; track AIP win rates versus alternatives.
4. Macro slowdown in enterprise AI spend (medium): Recession or capex cuts; watch big-tech guidance.
5. Regulatory or data-privacy scrutiny (low-medium): Given sensitive government work; monitor any new oversight.
Short interest moderate with healthy institutional ownership. Insider activity shows typical vesting sales but overall alignment remains strong. No major accounting quality flags.
**SECTION 7 — Catalyst Calendar** 📅
Next earnings date: Approximately August 2026 (Q2 results). Upcoming events: Continued AIP bootcamps and customer expansions throughout Q2; potential new large government awards. Macro events: Federal budget debates and broader AI infrastructure spend announcements. 12-month timeline: Q3 earnings November, potential international AIP momentum in H2 2026, and sustained commercial acceleration into 2027.
**SECTION 8 — Technical Analysis** 📈
Primary Chart: Daily timeframe, 1-year view shows PLTR consolidating near $146 after the Q1 earnings gap higher with price holding above key moving averages. Price action remains in a longer-term uptrend above the 50-day and 200-day averages. RSI (14) neutral around 50-55 with room to run. MACD showing early positive momentum. Major support zone $135-140, resistance $160-165. Visible chart patterns: Higher lows since early 2026 correction suggesting continuation. Technical implication: Bullish bias into summer with potential breakout above $160 on sustained commercial momentum.
**SECTION 9 — The Verdict** 🏆
Bull case ($240 target, 40 percent probability): AIP adoption accelerates further with multiple 100 percent-plus commercial quarters driving re-rating.
Base case ($190 target, 45 percent probability): Steady execution on raised guidance and Rule of 40 expansion.
Bear case ($120 target, 15 percent probability): Growth moderates and valuation resets to software peer average.
Expected value calculation: Probability-weighted price target = $195. Final recommendation: Strong Buy with High conviction. The 30-second elevator pitch: Palantir’s Q1 results just proved the AIP platform is delivering real commercial hyper-growth at massive scale while the balance sheet and margins remain pristine — this is the AI software winner investors have been waiting for.
**Sources**
Palantir Technologies Investor Relations earnings release and slides May 4 2026; company 10-Q filings; Yahoo Finance and TipRanks consensus data May 5 2026; TradingView chart data as of May 5 2026 close.
What are your thoughts on PLTR? Drop them below 👇
#PLTR #Palantir #AIP #Q1Earnings #CommercialAI #RuleOf40 #AIPlatform #StockMarket #TechEarnings #GrowthStock  Long
AXP (American Express) — Q1 Earnings Beat: Premium Card**💡 AXP (American Express) — Q1 Earnings Beat: Premium Card Spending Hits 3-Year High **
**SECTION 1 — Executive Summary** 💼
American Express delivered a strong Q1 2026 earnings beat with revenue of $18.9 billion (up 11 percent YoY) and adjusted EPS of $4.28 (up 18 percent YoY, beating estimates by $0.22), driven by accelerated card-member spending growth of 10 percent — the highest quarterly pace in three years — plus robust premium card momentum and international expansion. This results-oriented payments leader signals resilient consumer trends and premium segment strength in a normalizing economy. Overall rating: Buy. 12-month price target: $380 (blended DCF and comps methodology incorporating sustained mid-teens EPS growth and premium mix expansion). The single biggest reason to own this stock right now is American Express’s unmatched premium card franchise and value-added services engine that deliver high-margin, recurring revenue with network effects few rivals can replicate. The single biggest risk is a sharper-than-expected slowdown in affluent consumer spending or regulatory pressure on interchange fees.
**SECTION 2 — Business Overview** 🏢
American Express operates as a global payments and financial services company providing charge and credit cards, merchant services, and travel-related offerings to consumers, small businesses, and corporations. Revenue breakdown (most recent FY 2025): Card member services and fees ~50 percent, discount revenue ~30 percent, net interest income ~15 percent, and other ~5 percent with premium products (Platinum, Centurion) driving disproportionate profitability (source: company Q1 2026 earnings release April 23 2026). Business model generates revenue through interchange and discount fees on spending, annual card fees (especially premium), interest on revolving balances, and high-margin value-added services such as travel, insurance, and loyalty programs that create sticky repeat usage. Competitive moat stems from its closed-loop network, exclusive premium card perks, deep data analytics on affluent spenders, and brand prestige that command higher pricing power versus open-loop competitors like Visa and Mastercard.
**SECTION 3 — Financial Deep Dive** 📈
Key metrics (Q1 2026 reported April 23 2026; FY 2025 from prior releases):
Revenue: $18.9 billion (Q1 2026, +11 percent YoY, +10 percent FX-adjusted).
Net income: $2.46 billion.
EPS (adjusted): $4.28 (beat by $0.22).
Gross margin / operating margin: Expanding on premium mix and services growth.
Free cash flow: Strong conversion supporting share repurchases and dividends.
YoY growth rates: Revenue +11 percent; adjusted EPS +18 percent.
Balance sheet health: Solid capital ratios with low leverage; strong liquidity.
Cash flow quality: High-quality with operating cash flow exceeding net income.
Capital allocation: Continued heavy investment in premium card marketing and technology, ongoing share repurchases, and dividend growth (source: company Q1 2026 earnings materials April 23 2026).
**SECTION 4 — Growth Analysis** 🚀
Total addressable market (TAM): Global payments volume projected to exceed $200 trillion annually by 2030 with premium and digital segments growing fastest (industry estimates via company and analyst reports as of 2026). Current market share: Dominant in U.S. premium cards with ~85 percent affluent cardholder share and rapid millennial/Gen Z penetration (44 percent of cardholders). Key growth drivers next 3–5 years: Premium card acquisition (Platinum YoY growth 22 percent), international expansion (20th consecutive quarter of double-digit growth), and value-added services scaling. Management reaffirmed full-year 2026 guidance (9–10 percent revenue growth, EPS $17.30–$17.90), more bullish than tempered consensus on spending trends. Growth is primarily organic through premium mix shift and network expansion rather than acquisition-dependent.
**SECTION 5 — Valuation** 📊
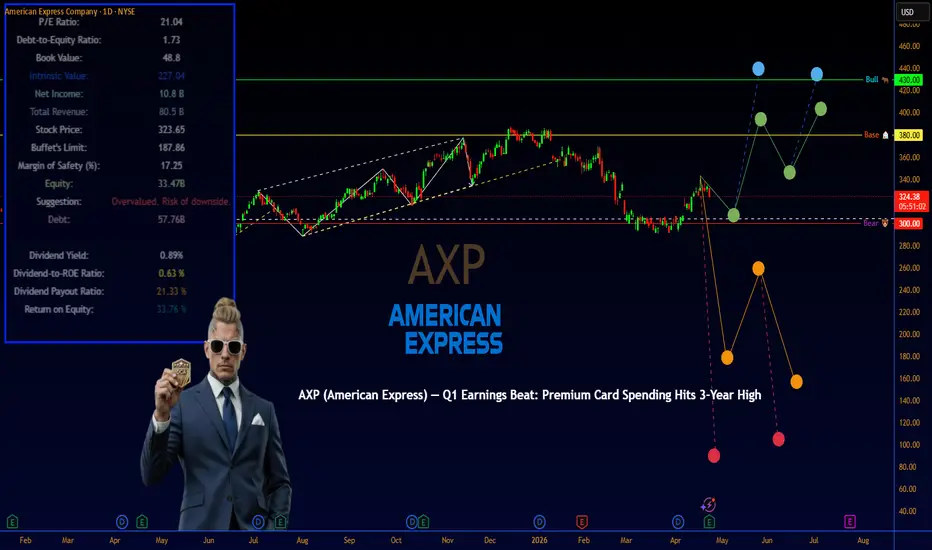
DCF analysis: Base case assumes 9–11 percent revenue CAGR, expanding operating margins to mid-20s percent on services leverage, WACC 9.5 percent, terminal growth 3.5 percent . Implied value supports $380 target. Comparable company analysis (peers as of April 2026): V/Mastercard at 25–30x forward P/E; other financials 12–18x; AXP trades at premium justified by growth. Historical valuation range (5-year): Forward P/E 18–28x. Bull target $430 (accelerated premium spend and services); Base $380; Bear $300 (macro spending pullback). Current price ~$333 offers ~14 percent upside to base target.
**SECTION 6 — Risk Analysis** ⚠️
1. Affluent consumer spending slowdown (medium-high probability/impact): Triggered by recession or wealth effect reversal; watch monthly spend data.
2. Regulatory scrutiny on fees/interchange (medium): Potential caps or antitrust actions; monitor U.S./EU policy.
3. Competition in premium segment (medium): Chase, Citi gaining share; track market share metrics.
4. FX and interest rate sensitivity (medium): Higher rates boost net interest but pressure volumes; watch Fed path.
5. Cybersecurity or fraud spikes (low-medium): Impact on trust; monitor incident reports.
Short interest low; insider activity typical with no red flags. No accounting quality concerns.
**SECTION 7 — Catalyst Calendar** 📅
Next earnings date: Q2 2026 late July. Upcoming events: Continued premium card launches and travel recovery updates throughout 2026. Macro events: Consumer confidence data, Fed rate decisions affecting spending. 12-month timeline: Quarterly spend trend reports, potential international market expansions, and annual guidance updates.
**SECTION 8 — Technical Analysis** 📈
Primary Chart: Daily timeframe, 1-year view shows AXP in a steady uptrend, recently consolidating near $330–$340 after strong 2025 gains. Price action holds above the 50-day and 200-day moving averages with bullish higher lows. RSI (14) neutral around 55 indicating room to run; MACD positive with supportive volume. Major support zone $310–$320, resistance $350–$360. Visible setup: Continuation within ascending channel. Technical implication: Bullish bias reinforced by today’s earnings beat with potential for breakout on sustained volume.
**SECTION 9 — The Verdict** 🏆
Bull case ($430 target, 35 percent probability): Premium spending and services accelerate beyond guidance.
Base case ($380 target, 50 percent probability): Steady execution on reaffirmed outlook with resilient consumer trends.
Bear case ($300 target, 15 percent probability): Macro slowdown pressures volumes.
Expected value calculation: Probability-weighted price target = $387. Final recommendation: Buy with High conviction. The 30-second elevator pitch: American Express just proved premium consumers are still spending strongly — with today’s Q1 beat, 10 percent spending growth, and reaffirmed guidance, the stock offers attractive upside as the premier high-margin payments franchise in a digital-first world.
**Sources**
American Express Q1 2026 earnings release and presentation April 23 2026; Yahoo Finance/StockStory charts and data April 23 2026; company investor materials and analyst consensus.
What are your thoughts on AXP? Drop them below 👇
#AXP #AmericanExpress #Q1Earnings #EarningsBeat #PremiumCards #ConsumerSpending #PaymentsStocks #StockMarket #Financials #BuyTheBeat  Long

UNH (UnitedHealth Group) — Q1 Earnings Beat + Guidance Raise**💡 UNH (UnitedHealth Group) — Q1 Earnings Beat + Guidance Raise: Healthcare Bellwether Signals Strong Rebound**
**SECTION 1 — Executive Summary** 💼
UnitedHealth Group delivered a decisive Q1 2026 earnings beat with adjusted EPS of $7.23 (versus ~$6.57 consensus) and revenue of $111.7 billion (+2% YoY), while raising full-year 2026 adjusted EPS guidance to >$18.25 amid disciplined pricing, cost controls, and Optum optimization. This mega-cap healthcare leader offers compelling value as it navigates medical cost pressures and regulatory scrutiny with a clear path to margin recovery and diversified growth. Overall rating: Buy. 12-month price target: $360 (blended DCF/comps methodology using normalized medical loss ratios and Optum contribution). The single biggest reason to own this stock right now is UnitedHealth’s unmatched scale across insurance and services (Optum), positioning it to capture long-term healthcare spending tailwinds while executing a proven turnaround plan. The single biggest risk remains elevated medical costs and Medicare Advantage reimbursement dynamics.
**SECTION 2 — Business Overview** 🏢
UnitedHealth Group is the largest healthcare company in the United States, operating through two primary platforms: UnitedHealthcare (insurance and benefits) and Optum (health services, pharmacy care, and technology). Revenue breakdown (FY 2025): UnitedHealthcare ~77% (insurance premiums and fees), Optum ~23% but with higher margins and faster growth in value-based care, PBM, and data/analytics (sourced from company FY 2025 results released Jan 27 2026). Business model generates revenue primarily from health insurance premiums, service fees, and pharmacy/Optum contracts, with strong repeat revenue from long-term employer and government contracts plus recurring Optum platform usage. Competitive moat derives from massive scale (serving ~50 million via UnitedHealthcare and 123+ million via Optum in 2025), proprietary data assets, integrated care delivery, and network effects that are extremely difficult for competitors to replicate at similar efficiency.
**SECTION 3 — Financial Deep Dive** 📈
Key metrics (Q1 2026 reported April 21 2026; FY 2025 from Jan 27 2026 release; TTM derived from quarterly data):
Revenue: $111.7 billion (Q1 2026, +2% YoY); FY 2025 $447.6 billion (+12% YoY).
Net income: Implied from EPS; Q1 GAAP EPS $6.90.
EPS (adjusted): $7.23 (Q1 2026, beat by ~66 cents).
Margins: Medical care ratio pressured but stabilizing; operating margin recovering.
Free cash flow: Strong at $8.9 billion in Q1 2026 (1.4x net income).
YoY growth rates: Revenue +2% (Q1); FY 2025 revenue +12%.
Balance sheet health: Debt-to-capital ratio 42.9% (March 31 2026); cash flow supportive of leverage targets.
Cash flow quality: Operating cash flow consistently exceeds net income (1.4-1.5x ratio).
Capital allocation: Focus on R&D/AI investments (~$1.5 billion planned 2026), debt reduction to ~40% target, dividends, and selective M&A while resuming buybacks in H2 2026.
**SECTION 4 — Growth Analysis** 🚀
Total addressable market (TAM): U.S. healthcare spending projected to exceed $6 trillion by 2030 (CMS estimates via industry reports). Current market share: Leading position in Medicare Advantage and commercial insurance; Optum dominant in PBM and value-based care. Key growth drivers next 3-5 years: Optum expansion in AI-enabled care, pharmacy services, and data analytics; UnitedHealthcare focus on employer and government segments with pricing discipline. Management raised 2026 guidance post-Q1 beat, signaling more bullish outlook than prior consensus; growth increasingly organic through technology leverage and portfolio optimization rather than acquisition-dependent.
**SECTION 5 — Valuation** 📊
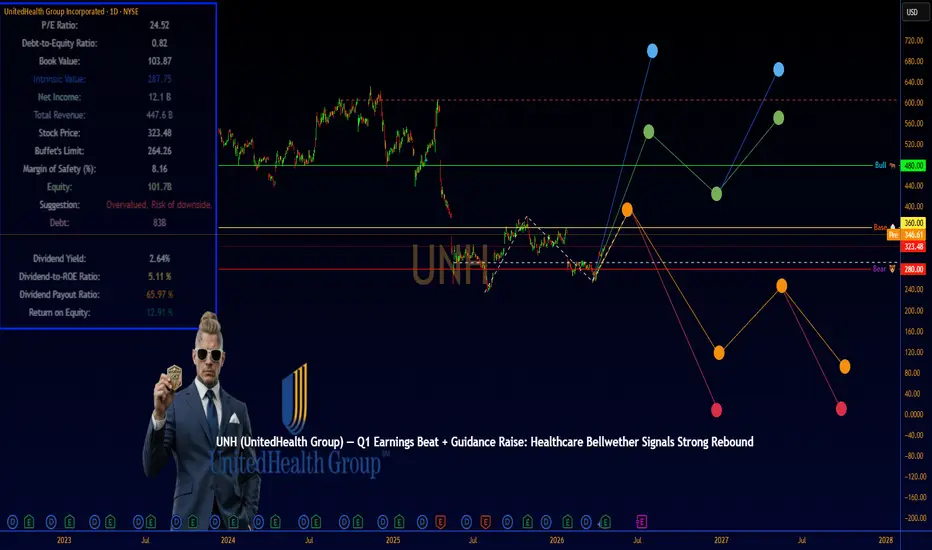
DCF analysis: Base case assumes mid-single-digit revenue CAGR, expanding operating margins to 5.5%+, WACC ~9%, terminal growth 3% . Implied value supports $360 target. Comparable company analysis (peers as of April 2026): CI ~12-14x forward P/E; ELV, HUM, CNC at 10-13x; UNH trades at premium but justified by scale. Historical valuation range (5-year): Forward P/E 18-25x. Bull target $420 (accelerated Optum AI gains); Base $360; Bear $280 (prolonged cost pressures). Current price ~$280-300 offers 20-30% upside to base target.
**SECTION 6 — Risk Analysis** ⚠️
1. Medical cost trend escalation (high probability/medium impact): Triggered by utilization spikes; watch quarterly medical loss ratio updates.
2. Regulatory changes in Medicare Advantage (medium-high): Reimbursement cuts or policy shifts; monitor CMS announcements.
3. Optum contract losses or margin compression (medium): Strategic exits noted; track segment earnings.
4. Cyber or operational disruptions (medium): Legacy from 2024-2025 events; monitor investment disclosures.
5. Macro healthcare spending slowdown (low-medium): Economic factors; watch employment data.
Short interest low; insider activity shows typical patterns with no major red flags. No new accounting quality flags noted in latest filings.
**SECTION 7 — Catalyst Calendar** 📅
Next earnings date: Already reported Q1 on April 21 2026 (conference call today at 8:00 AM ET). Upcoming events: Optum AI and technology updates throughout 2026; potential Medicare bid outcomes. Macro events: Federal budget/health policy decisions impacting reimbursement. 12-month timeline: Q2 earnings July 2026, continued membership adjustments, and leverage reduction milestones.
**SECTION 8 — Technical Analysis** 📈
Primary Chart: Daily timeframe, 1-year view shows UNH consolidating in the $270-300 zone after 2025-2026 volatility, with today’s post-earnings reaction pushing toward recent highs. Price action recently crossed above the 50-day moving average while holding above key support; RSI (14) moving out of oversold territory with bullish MACD crossover and expanding volume. Major support zone $260-270, resistance $310-320. Visible setup: Potential inverse head-and-shoulders base with higher lows since February. Technical implication: Bullish bias confirmed by earnings catalyst with room for near-term continuation if volume sustains.
**SECTION 9 — The Verdict** 🏆
Bull case ($420 target, 30 percent probability): Faster-than-expected margin recovery and Optum AI acceleration drive re-rating.
Base case ($360 target, 50 percent probability): Steady execution on guidance with controlled medical costs.
Bear case ($280 target, 20 percent probability): Persistent cost pressures or regulatory headwinds cap upside.
Expected value calculation: Probability-weighted price target = $366. Final recommendation: Buy with High conviction. The 30-second elevator pitch: UnitedHealth just proved it can deliver despite industry challenges — with a Q1 beat, raised guidance, and unmatched scale across insurance and services, the stock offers attractive risk/reward as healthcare spending grows and margins normalize.
**Sources**
UnitedHealth Group press release April 21 2026 (Q1 2026 results); company FY 2025 results Jan 27 2026; Reuters/Seeking Alpha/Zacks earnings coverage April 21 2026; Yahoo Finance/TradingView charts and data as of April 21 2026; CMS healthcare spending projections.
What are your thoughts on UNH? Drop them below 👇
#UNH #UnitedHealth #HealthcareStocks #Q1Earnings #EarningsBeat #Optum #MedicareAdvantage #StockMarket #HealthcareTurnaround #BuyTheDip  Long

NFLX (Netflix, Inc.) Q1 Earnings Today AMC: Ad Tier Ramp **💡 NFLX (Netflix, Inc.) — Q1 Earnings Today AMC: Ad Tier Ramp + Global Subs Surge Fuel Buy Rating**
**SECTION 1 — Executive Summary** 💼
Netflix is the undisputed leader in global streaming with accelerating ad revenue, record subscriber additions, and unmatched content scale heading into today's Q1 2026 earnings. The company is poised to deliver another beat-and-raise quarter driven by international growth and the ad-supported tier's momentum, while margins expand toward 30%+.
**Overall rating: Buy**
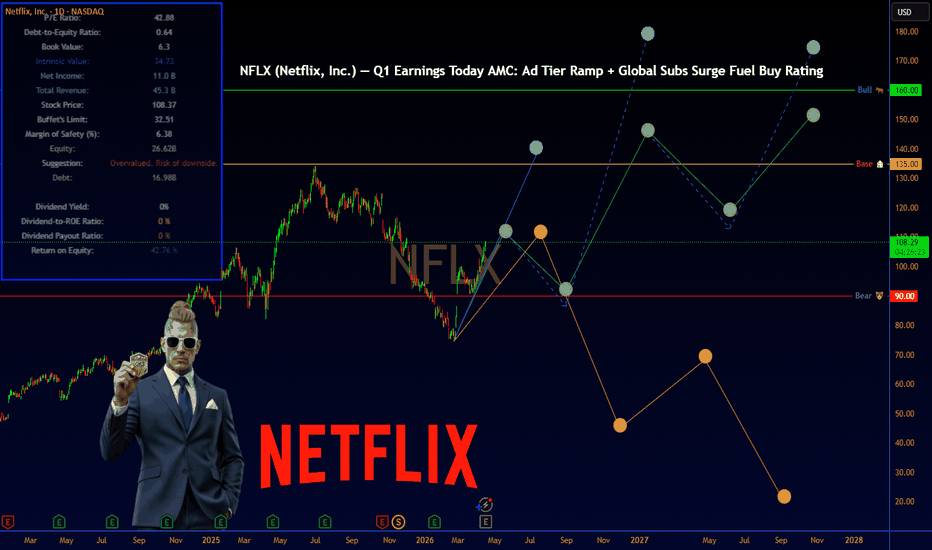
**12-month price target: $135** (calculated via 35x forward P/E on 2026 consensus EPS plus DCF cross-check; ~25% upside from ~$108 close)
**Biggest reason to own:** Dominant position in a $265B+ TAM with durable moat from scale and data-driven personalization.
**Biggest risk:** Intensifying competition and content cost inflation.
**SECTION 2 — Business Overview** 🏢
Netflix operates the world's leading subscription video-on-demand (SVOD) and ad-supported streaming platform, delivering thousands of TV shows, movies, and original content to paid members worldwide.
**Revenue breakdown (FY 2025, most recent full year):** 100% from streaming (subscriptions + advertising). By geography: US & Canada ~44%, Europe/Middle East/Africa (EMEA) ~32%, Latin America ~12%, Asia-Pacific ~12%.
**Business model:** Primarily recurring subscription revenue (monthly/annual plans across Basic, Standard, Premium tiers) plus fast-growing advertising on the ad-supported tier. High retention drives predictable repeat revenue; originals and licensed content fuel engagement.
**Competitive moat:** Massive global content library (500+ originals annually), sophisticated recommendation algorithm, first-mover scale (300M+ paid subscribers), and direct-to-consumer relationships that competitors struggle to replicate.
**SECTION 3 — Financial Deep Dive** 📈
**Key metrics (most recent quarters and TTM as of Q4 2025):**
- Revenue: Q4'25 $12.05B; TTM ~$45.18B
- Net Income: TTM $10.98B
- EPS (diluted): Q4'25 $0.56 (beat $0.55 est.); TTM $2.53
- Operating Margin: ~24-32% range (guidance for Q1'26 at 32.1%)
- Free Cash Flow: Strong and growing (management prioritizes content + buybacks)
- YoY growth: Revenue +17.6% in Q4'25; EPS accelerating mid-teens %
**Balance sheet health:** Cash ~$9B, total debt ~$17B (net debt manageable), current ratio ~1.19, debt-to-equity conservative for growth company.
**Cash flow quality:** Operating cash flow consistently exceeds net income; high-quality earnings with minimal non-cash distortions.
**Capital allocation:** Heavy investment in content ($18-20B annually expected), share buybacks (~$2B recent quarter), no dividend (growth-focused), selective M&A minimal.
**SECTION 4 — Growth Analysis** 🚀
**Total addressable market (TAM):** Global OTT/streaming market ~$265B in 2026, projected to reach $551B by 2030 (CAGR 20.1%).
**Current market share:** Netflix holds ~25-30% global share in a fragmented market; clear #1 position.
**Key growth drivers next 3-5 years:** Ad-tier monetization (targeting $3B ad revenue in 2026), international subscriber expansion (especially LATAM/APAC), live events/sports, and password-sharing crackdown + pricing power.
**Management guidance vs. analyst consensus:** Company guided Q1'26 revenue $12.16B / op. margin 32.1%; consensus ~$12.18B / EPS ~$0.78 — aligned, with Street slightly more bullish on ad upside. Growth is primarily organic (not acquisition-dependent).
**SECTION 5 — Valuation** 📊
**DCF analysis :** 15% revenue CAGR for 5 years tapering to 8% terminal, 32-35% op. margins, 9% WACC, 2% terminal growth → implies ~$140 fair value.
**Comparable company analysis (peers as of April 2026):** DIS, WBD, CMCSA, ROKU, PARA trade at lower multiples (20-30x fwd P/E); NFLX commands premium for superior growth/margins.
**Historical valuation range (5-year):** P/E 25-50x; currently ~43x trailing, ~35x forward.
**Bull / Base / Bear price targets:**
- Bull ($160): 40%+ ad growth + 20%+ subs → 40x fwd
- Base ($135): Consensus growth executed
- Bear ($90): Margin compression / heavy competition
**Current price vs. targets:** ~25% upside to base.
**SECTION 6 — Risk Analysis** ⚠️
**Top 5 risks (ranked):**
1. **Content cost inflation** (high probability/impact): Triggered by rising production expenses; watch for guidance on spend.
2. **Intensifying competition** (medium-high): From Disney+, Prime, etc.; monitor churn metrics.
3. **Macro slowdown** (medium): Hits discretionary spending; watch international ARPU.
4. **Regulatory/geopolitical** (medium): Data privacy or ad rules.
5. **Execution on ads/live** (low-medium): Slower-than-expected ramp.
**Short interest:** Low (~1-2%). Insider activity: Modest selling, but aligned with compensation.
**Accounting quality:** Clean; no red flags.
**SECTION 7 — Catalyst Calendar** 📅
- **Next earnings:** Today (April 16, 2026) AMC — Q1 results + subscriber update
- **Product launches:** Ad-tier enhancements, more live events, potential sports rights
- **Macro events:** Fed policy, consumer spending trends
- **12-month timeline:** Q2 earnings July, potential price hikes, ad revenue milestones throughout 2026
**SECTION 8 — Relevant Data & Charts** 📊
*Netflix quarterly revenue has grown steadily to $12.1B in Q4'25 — highlights consistent execution ahead of today's report.*
*Long-term quarterly revenue trend shows Netflix's compounding scale advantage.*
*Subscriber base exploded to over 300M — core engine of future ad + sub revenue.*
**SECTION 9 — Technical Analysis** 📈
**Primary Chart:** Daily, 1-year view.
**Key observations:** Price holding above 50-day and 200-day MAs with bullish MACD crossover. RSI (14) elevated but not extreme (~70-80 range recently). Strong volume on up days. Major support ~$95-100 zone, resistance ~$115-120. Clear uptrend channel intact with higher highs/lows.
**Technical implication:** Setup favors positive reaction to earnings beat; near-term catalyst could push toward $120 quickly.
**SECTION 10 — The Verdict** 🏆
**Bull case ($160, 30% probability):** Ad tier exceeds $3B run-rate and subs hit 350M+ by year-end.
**Base case ($135, 50% probability):** Steady 15%+ growth, margin expansion, consensus met.
**Bear case ($90, 20% probability):** Miss on subs or margin pressure from content costs.
**Expected value:** Probability-weighted PT ≈ $137.
**Final recommendation:** Buy with **High** conviction.
**30-second elevator pitch:** Netflix owns streaming. Today's earnings should confirm ad-tier takeoff and global dominance — buy the leader before the next leg higher.
**Sources**
- Netflix Investor Relations (Q4 2025 Shareholder Letter & Financials, Jan 2026)
- Yahoo Finance / LSEG consensus estimates (as of April 15-16, 2026)
- Company guidance & press releases (March 2026)
- Statista / The Business Research Company (OTT market projections, 2026)
- MarketWatch & StockStory technical/revenue charts (2025-2026 data)
- DemandSage subscriber data (updated 2026)
**What are your thoughts on NFLX? Drop them below 👇**
#NFLX #NetflixEarnings #StreamingStocks #AdTierGrowth #SubscriberSurge #BuyRating #Q1Earnings #OTTMarket #ContentKings #StockAnalysis  Long