RBRK Earnings Just Changed the Cybersecurity GameRubrik just walked into earnings and did what expensive growth stocks are supposed to do.
It beat the Street and then raised the damn bar, Q2 revenue hit $427.3 million. That was up 38% year over year and about $31 million above consensus. Adjusted EPS came in at $0.20 against $0.04 expected.. That is not a small beat, That is the kind of number that tells you management is executing faster than Wall Street modeled. The market still punished the stock after hours. Good. That tells you the problem is not the business. The problem is what investors were already pricing into the stock
ARR Is Where the Money Is
Forget the headline revenue for a second, Look at the recurring machine underneath it. Rubrik finished the quarter with $1.66 billion in Subscription ARR. That is up 33% year over year. Net new Subscription ARR jumped 35%. Cloud ARR reached $1.48 billion and grew 39%. That is the metric I want to see because ARR tells you where the revenue engine is heading rather than where it has already been. Customers are committing more money to Rubrik and the cloud business is expanding faster than the overall subscription base. That gives this story real momentum
Now It Is Making Money Too
Here is where Rubrik gets interesting, High growth is easy to love when someone else is paying the bill. Rubrik is starting to show that it can grow and improve economics at the same time. Operating cash flow reached $76.8 million while free cash flow came in at $65.7 million. The company posted an 18% operating cash flow margin and a 15% free cash flow margin for the quarter. Subscription ARR contribution margins are also expanding. Management now expects roughly 15.5% for the full fiscal year. That changes the conversation. Rubrik is no longer just a cyber sec growth story.. It is becoming a growth plus cash flow story
Management Just Raised the Stakes
Management did not come out of this quarter playing defense. They raised the full year numbers. Rubrik now expects $1.685 billion to $1.693 billion in revenue and $1.88 billion to $1.885 billion in Subscription ARR. Full year adjusted EPS is now expected at $0.47 to $0.53 with free cash flow guidance at $323 million to $333 million . That is what you want after a strong quarter.. You want management looking at the next six months and saying the demand is strong enough to raise the target. The market can argue about valuation, It cannot argue that the company is sitting still
AI Is the Bigger Bet
Rubrik is also trying to turn AI from a threat into a revenue opportunity. Its pitch is cyber resilience for the AI era with security around autonomous AI agents and the data they touch. That matters because every new AI deployment creates another attack surface and another pile of valuable enterprise data that needs protection. Rubrik is still early here
Agent Cloud has more than 15 paying customers and management is treating the current ARR contribution as minimal. That means the market is not yet paying for a massive AI revenue stream. If Rubrik can turn that product into a meaningful growth engine over the next few years then today's numbers could look like the opening act
The Stock Is the Problem
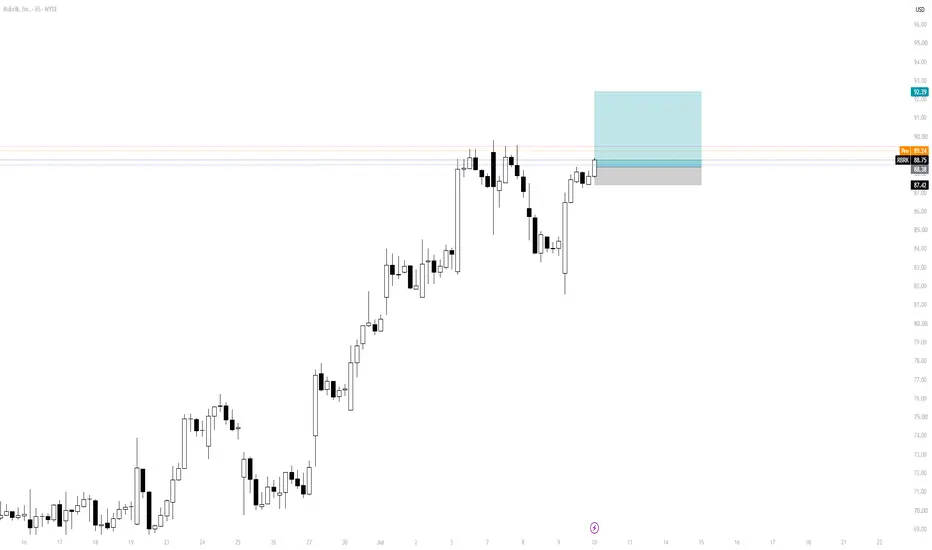
Now we get to the part that separates a good company from a good trade, RBRK aint cheap. Shares had already gained roughly 50% during Aug. So investors were not walking into this report expecting Rubrik to simply beat
They were expecting perfection. That is why the selloff makes sense. My aggressive bull case puts $125 to $135 in play if Rubrik keeps delivering 30%+ ARR growth while expanding cash flow and profitability. The bear case is a compression toward the $85 to $95 zone if growth slows and the market decides the multiple got ahead of itself. But if you are looking for the trade with the better asymmetric setup I would rather watch the weakness than chase the green candle
The company just proved the numbers are real. Now the stock has to prove the valuation is.
 Long