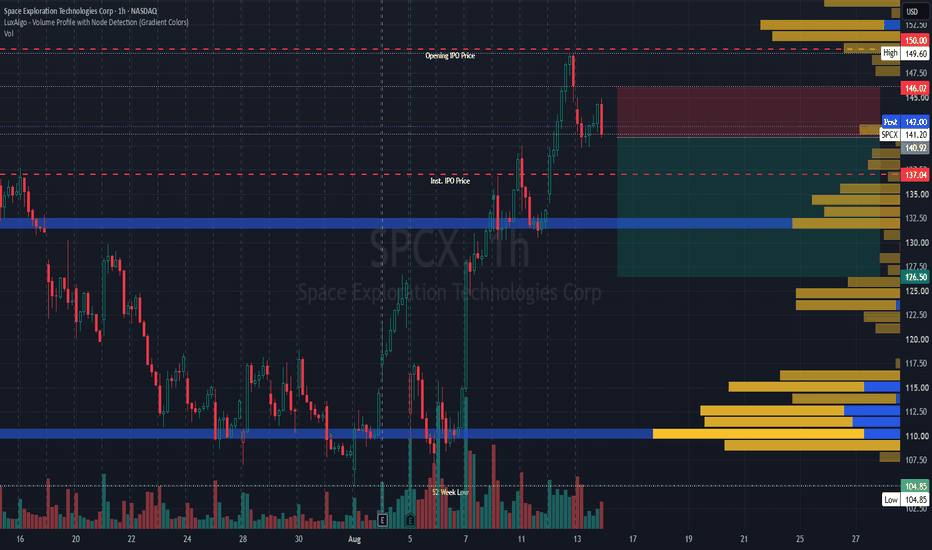
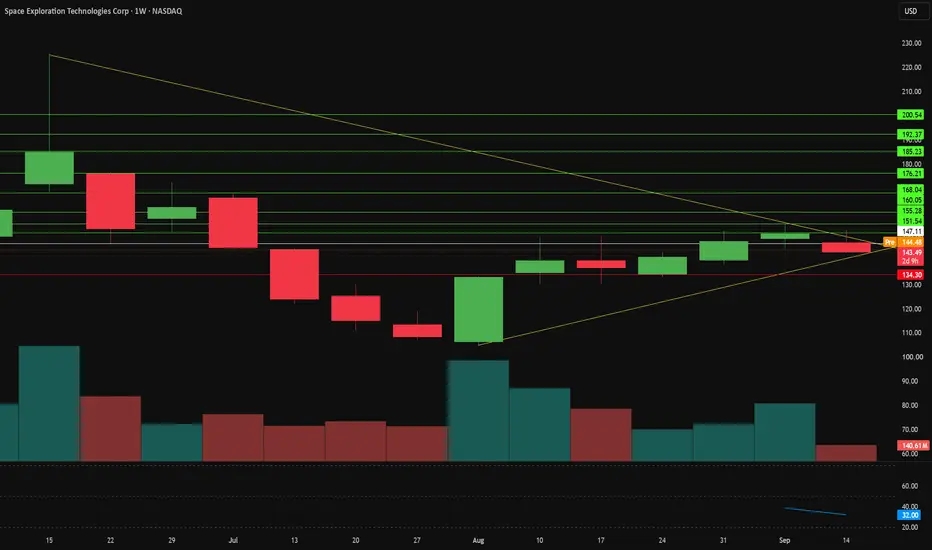
Long

Can Starlink's Profits Outrun a $75 Billion Cash Burn?SpaceX trades near $143.49 per share after its public debut, valuing the company at roughly $1.94 trillion. The macro backdrop works against that multiple. The ten-year Treasury yield has approached 5.0%, lifting discount rates across growth equities, while crude above $100 per barrel raises aerospace supply chain costs. Near-term flows cut the other way: the September 18 Nasdaq-100 rebalance lifts SpaceX's weighting from 1.28% to 2.82%, forcing up to $22 billion of passive buying. That demand meets heavy supply. Lockup releases have already added over 1.2 billion shares, and another 2.3 billion will become tradable before year-end.
Second-quarter revenue reached $7.81 billion, up 91.9% year-over-year, against $18.7 billion for all of 2025. Management guides toward $100 billion in annual recurring revenue by December. Connectivity carries the business, with Starlink producing $4.3 billion in quarterly revenue and $2.6 billion in adjusted EBIT from 12 million subscribers at $66 ARPU. AI compute leasing added $2.6 billion in revenue and $1.1 billion in operating profit, helped by one undisclosed client paying $1.11 billion monthly. The launch segment still loses money, posting a $200 million adjusted EBIT loss as Starship development absorbs connectivity profits. Quarterly capital expenditures hit $18.4 billion, an annualized pace near $75 billion. David Einhorn has publicly questioned how investment-grade ratings square with persistent negative free cash flow.
Government demand supplies the strategic ballast. A White House directive on commercial space transportation accelerates launch approvals, and Italy is negotiating a $1.6 billion Starlink security contract despite domestic opposition and Brussels' preference for the €10 billion IRIS² constellation, which will not fly before 2030. Starshield extends the franchise into defense, with satcom terminals planned across the F-35 fleet by 2031. The Pentagon's IL5 accreditation for Grok for Government opened a recurring software revenue line reaching 1.7 million defense personnel. Data center capacity of 1.4 gigawatts is scaling toward 2.0 gigawatts this year, at roughly $50 billion per gigawatt to build.
Starship Flight 14 launches September 22 as the program's first orbital and first revenue-generating mission, deploying 26 Starlink V3 satellites. That single flight adds 26 terabits per second of bandwidth against 2.6 from a Falcon 9, with production missions targeting 60. The patent data reveals where management believes the moat sits: 73.5% of published families cover RF and user terminals, while rockets and propulsion account for just 3%. Engines and metallurgy stay locked as trade secrets rather than public blueprints. The investment question reduces to timing. If Starship reaches full reusability, SpaceX controls orbital bandwidth economics outright. Until operating cash flow covers the capital budget, the shares stay volatile. Long 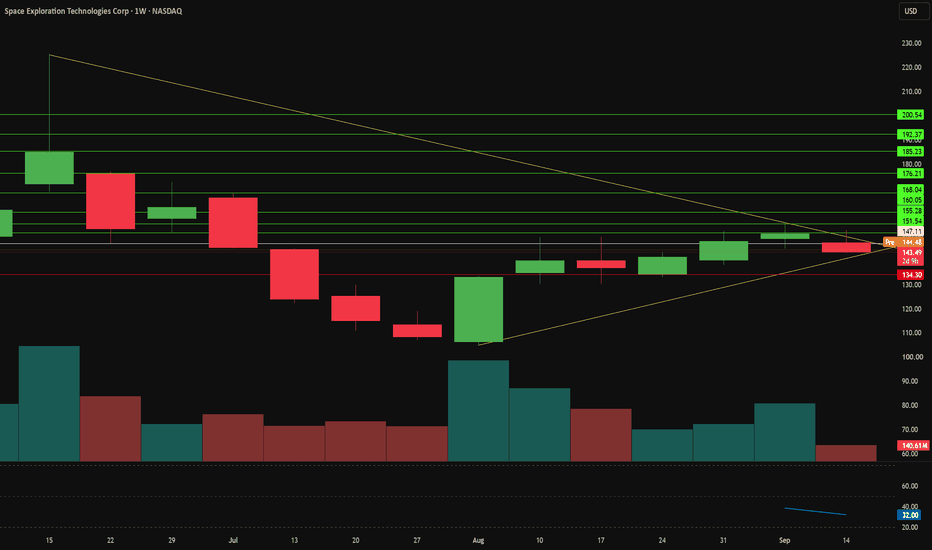
Can SpaceX Monopolize Space and AI Computing?Macroeconomics and Economic Realities
SpaceX targets an astonishing $100 billion annualized revenue run rate by December 2026. Chief Financial Officer Bret Johnsen frames that as a forward-looking exit run-rate, not recognized full-year revenue. He also ties it to fully integrating the recently acquired AI startup Cursor. Second-quarter revenue reached $7.8 billion, up 92 percent year over year. That pace annualizes to roughly $31 billion today. Massive new AI compute leasing deals drive this rapid financial expansion. The company recently signed a $1.11 billion monthly compute contract beginning in December. That agreement adds over $13 billion in annualized revenue. However, Johnsen describes almost all hosting deals as 90-day commitments with 90-day exit provisions. These amount to roughly six-month commitments rather than guaranteed multi-year backlog. The company still lost $541 million last quarter, narrowing from $1 billion a year earlier. Investors closely monitor whether subscription compute revenues can sustain current valuation growth.
Geopolitics and Geostrategy
Satellite constellations now serve as vital assets in modern international defense. Starlink provides sovereign nations with resilient communication infrastructure during military conflicts. Consequently, Western governments view SpaceX as an indispensable national security partner. The U.S. Department of Defense relies on specialized Starshield satellite arrays. Meanwhile, launch reliance on foreign nations has vanished across North America. Sovereign access to low Earth orbit strengthens Western geopolitical posture. However, concentrated reliance on a single private contractor creates strategic geopolitical tensions.
High-Tech Industry Trends
The high-tech landscape is witnessing a convergence of space launch and artificial intelligence. AI developers urgently require massive computational capacity and reliable power sources. SpaceX actively leases access to high-density GPU clusters at dedicated facilities. Anthropic pays $1.25 billion monthly for the majority of capacity at Colossus 1 in Memphis. That facility houses roughly 220,000 Nvidia processors across 300 megawatts, under contract through May 2029. Google pays $920 million monthly from October 2026 through June 2029. Those two deals alone generate about $2.17 billion monthly, a $26 billion annualized run rate. All three contracts together lift monthly external compute revenue toward $3.28 billion. Concurrently, direct-to-device Starlink capabilities threaten legacy telecom operators worldwide. Next-generation direct-to-cell satellites deploy next year, targeting commercial 5G-grade service by early 2028. This dual disruption across telecom and cloud compute reshapes global tech trends.
Technology, Science, and Pharmaceuticals
Reusable orbital rockets drastically reduce the cost of conducting scientific research in microgravity. Microgravity enables perfect protein crystal growth impossible under Earth’s gravitational pull. Pharmaceutical firms leverage Dragon missions to formulate advanced therapeutic drugs and biopharmaceuticals. Furthermore, the massive Starship launch vehicle carries next-generation Starlink V3 satellites into orbit. That mission marks Starship’s first deployment flight generating direct revenue. The upcoming Starship Flight 14 test flight targets late September 2026. This launch system promises unprecedented payload capacity for deep-space science and commercial payloads.
Business Models and Leadership
Chief Executive Officer Elon Musk built a vertically integrated commercial enterprise. SpaceX operates as a launch provider, satellite internet operator, and compute landlord. Chief Financial Officer Bret Johnsen successfully monetized excess computing infrastructure through flexible enterprise contracts. Vertical integration allows SpaceX to build rockets, engines, and satellites in-house. This strategy drastically lowers operating costs while maintaining high gross margins. Capturing market share across telecom and cloud services accelerates total revenue diversification.
Company Culture and Cybersecurity
SpaceX maintains a culture centered on rapid hardware iteration and engineering speed. Fail-fast testing methodologies accelerate technological breakthroughs across all engineering departments. Furthermore, space-based communication networks demand impenetrable hardware and software cybersecurity protocols. Engine-level encryption and secure laser inter-satellite links protect user data against state-sponsored cyberattacks. Orbital communications must resist electronic jamming during geopolitical crises. Enterprise clients prioritize this high level of cyber resilience when selecting satellite networks.
Patent Analysis and Future Outlook
Patent filings reveal extensive intellectual property covering reusable thermal shielding and propulsion systems. Proprietary Raptor engine architecture and staging mechanisms create massive technical barriers for competitors. Advanced phased-array antenna patents protect Starlink hardware from low-cost knockoffs. Will SpaceX successfully execute its dual expansion into orbital launch and global AI compute? The company possesses unmatched technical velocity and strong market momentum. SpaceX stands poised to dominate high-tech infrastructure on Earth and in orbit. Long 
Long 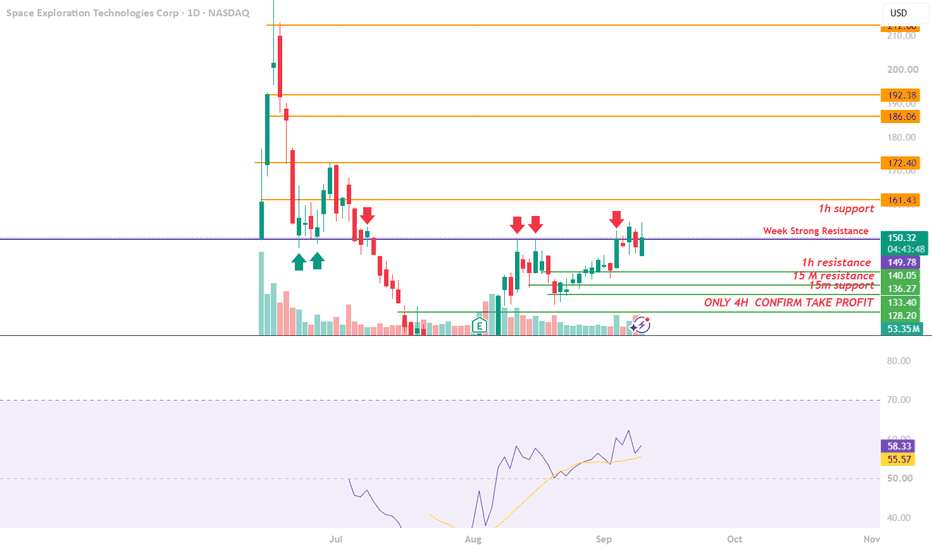
Long

SPCX: A Post-IPO Base, Read HonestlyA young chart is the hardest place to be honest about a tool. SPCX has a few months of trading history - which means every layer reading it has had a few months to learn it, not years. We publish the read anyway, and we say that limitation out loud, because a tool that only speaks where it looks good is not a tool.
What the structure layer marked. After the post-IPO run to the low 220s, price spent June and July giving most of it back, and built a base through the summer around 107-118. Across that base the panel marked an accumulation zone, and the signal you can see on the chart was stamped 14 bars ago on this 4h clock - printed into the base, dated before the question of "was that the low" had an answer. The adaptive reference sits at 141.59. Relative volume on the current tape reads LOW.
The first attempt is already on the chart. In mid-August price pushed up through the reference and spent a handful of bars above it - then gave the level back and returned below. We are not going to dress that up: an attempt that does not hold is information, the same way an attempt that holds would have been. The level was touched, the market was not ready to stay there, and the chart says so in public.
What we are watching now is the second approach. Price sits just under the line, a few percent below it, drifting back toward the level rather than away from it. Whether a second attempt comes, and whether it behaves differently from the first, is not something we predict - it is something the chart will answer. Two things would make that answer worth reading: what participation does (relative volume is LOW - a push on quiet tape is a weaker fact than the same push on expanding tape), and what happens on any retest from above, if price gets there at all.
The protocol is the same as always. Acceptance means price back above the reference and staying accepted there - retests holding, participation firming. Rejection means a second failure at the line, or a slide back toward the zone lows - and that would be information too, not an embarrassment. Zones can fail. Young charts fail faster than old ones, because there is less structure underneath them to lean on.
One more thing worth naming: this panel has spoken exactly once in this chart's entire life - 14 bars ago . On an instrument this young, that silence is most of the story. The layer is not built to narrate every candle; it is built to mark the few places worth watching. This is one. What happens at it is the market's job.
Educational market commentary - not financial advice. Long 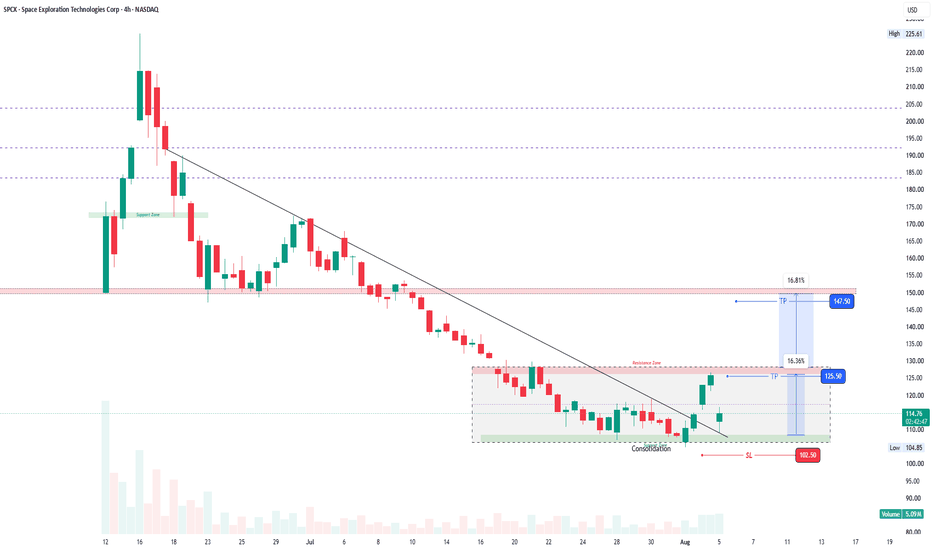
Long 
Short 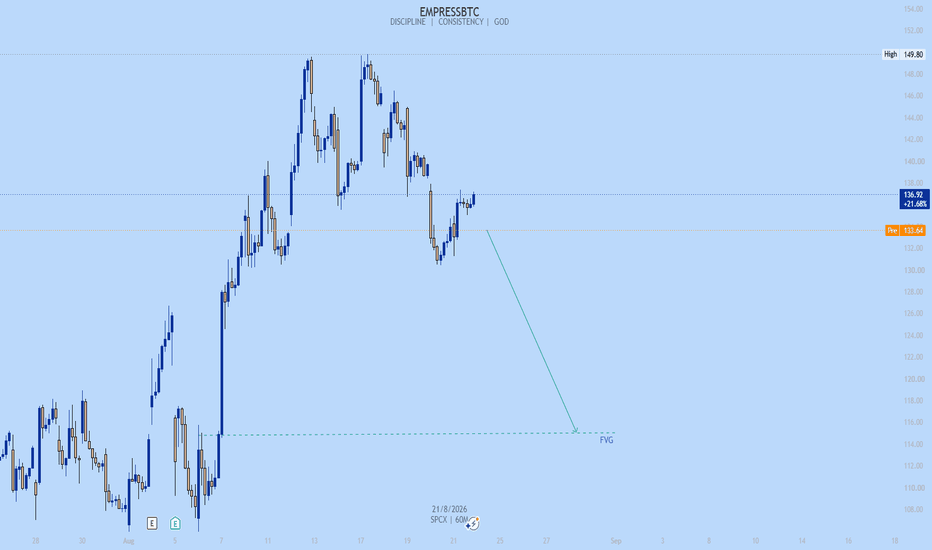
SPACEX: 149.92 Decides Everything!🚀 SPACEX (SPCX) — Offered It at $143. I Want It at $87.
📊 THE FACTS FIRST
SpaceX is now the 7th largest company in the world. Market cap: $1.889 trillion. Ticker SPCX, Nasdaq, listed June 12, 2026 at $135.
And right now there is FOMO everywhere — especially on X, which is Elon's own territory.
I understand why.
🛰️ Starlink — a connectivity business that can genuinely print money
🤖 xAI + Grok — real AI, real revenue potential, and it's hot
add GrokBOt, Elon's new surprise (AI Employee agents on cloud personal computers..clawbot+ without setups hassles..great idea/huge potential!)
🤖 Cursor deal also hot (read below)
𝕏 X — the distribution and data layer
🚀 SpaceX — the launch business underneath all of it
One ticker. Four businesses. That's a real story and I'm not here to argue against it.
⚠️ BUT
At the end of the day this is space exploration.
Think about the R&D it takes to build rockets and make Elon's dreams reality . That money has to come from somewhere — and shareholders have to stay happy while it's being spent.
There are pros and cons here. Anyone can take these same facts and build whatever narrative they want.
I don't do narratives.
I'm the FXProfessor. I'm all about the levels.
📈 THE LEVELS
🔴 149.92 — the major resistance and the key pivot. Everything hinges here.
Break above it and price can unleash toward:
▪️ 167.62
▪️ 188.91 — next major resistance
But we are under resistance right now. So I am obliged to be short.
🎯 Downside targets:
▪️ 127.06
▪️ 108.22 — previous support, tested and confirmed from July 2026 into early August 2026, and we rebounded from it
Given we're capped under resistance, I expect 108.22 gets tested again.
💙 WHERE I BUY
And to cut a long story short — I wouldn't be surprised to be buying at:
▪️ 87.65
▪️ or even lower, at 75.88
Those are my levels. That's where I want size.
⚡ AND IF I'M WRONG?
Don't forget — I'm a day trader.
If price pops even an inch over the $150 mark, I flip long.
▪️ Entry: just over 150
▪️ Stop: just under 149
No ego. The level decides, not me.
📅 ONE MORE THING NOBODY IS DRAWING
This stock has a supply calendar written into its own prospectus.
911.5 million shares unlocked on August 6. 319 million more unlock today, August 20. Roughly 700 million in September. Close to that again in October. Full 180-day expiry December 8.
Musk's 6.4 billion shares stay locked until June 12, 2027.
There's also a price trigger in the agreement: closes above $175.50 on 5 of any 10 sessions release another 455.8 million shares early. It didn't trigger before earnings — those rolled into December.
Read that again. Strength above 175.50 creates its own supply.
Every rally between now and December walks into new paper. That's not a forecast. That's a schedule.
And it's not only unlocks. On August 14, SpaceX closed the $60B all-stock acquisition of Cursor (Anysphere) — issuing roughly 389 million new Class A shares, plus assumed RSUs and options on top. That's brand new paper, created five days ago, on top of everything already scheduled.
⚠️ Where I could be wrong: August 6 was supposed to break this stock and it rose 6% that day, then 15% the next. Short interest had peaked near 34% of float — crowded shorts into a scheduled event are squeeze fuel. It's near 11% now. The supply may be arriving late rather than not at all.
So my answer at this price is simple: NO.
Not to the company. SpaceX is one of the great businesses of our lifetime and I want to own it.
No to this price under such resistance...No!
Play the levels. 🎯
One Love.
The FXPROFESSOR 💙
Not financial advice. My levels, my risk. Short 
SPACEX One last correction to $100 may be the market bottom.More than a month ago (July 7, see chart below), we posted a post-IPO roadmap for SpaceX (SPCX):
So far it has been following this structure fairly closely, with the price declining almost as low as $100 and then rebounding to $150 again.
As mentioned on that analysis, the $100 – $150 range can be treated as the potential macro accumulation area. If price spends enough time consolidating inside that zone, it would indicate that the market is moving from emotional post-IPO trading into a more mature institutional accumulation phase. That is usually where the strongest long-term trend reversals are built.
The most important technical level on this structure is the $150 - $155 Resistance Zone. A confirmed break above that area would be the first serious sign that the accumulation phase has ended and that buyers are starting to regain control of the trend.
Above that zone, SpaceX could enter its main expansion wave, with the first major upside area around $220, followed by a potential macro target near $270 (the 1.236 Fibonacci extension from its current All Time High).
So far that's not happening. And the fact that the price has spent its last 5 days consolidating just below $150, just shows that buyers don't have (so far) enough strength to push above it and as long as the market stays under it, the selling pressure will gradually pile up and confirm our idea above, that it is the most critical Resistance Zone.
What we do expect to happen next, is a final Bearish Leg to $100 or even $90, calling it a 'Capitulation Bottom'. A few months of price maturity consolidation within $100 - $150 would serve as a market discovery Accumulation Phase that will reveal when the long-term buyers will eventually prevail and break and turn $150 into a Support for the expansion wave.
As mentioned in July this chart simply suggested waiting for the market to complete its emotional post-IPO reset, form a deeper accumulation base, and then confirm the reversal through the $150 – $155 breakout zone. So far SpaceX continues to follow the classic post-IPO cycle: euphoria, distribution, capitulation, accumulation, breakout, and expansion. The biggest value will be found not now but after the market builds a strong enough base after this first major correction that it had, in order to create the structure for a sustainable long-term trend.
Technical Roadmap intact
Bullish confirmation:
A break and hold above $150 – $155.
Accumulation zone:
Between $100 – $150.
Deep value zone:
Around $90 – $100.
Upside targets:
First target $220, macro target $270.
Invalidation risk:
Failure to reclaim $150 – $155 after the correction would keep the structure neutral and delay the bullish expansion scenario.
---
** Please LIKE 👍, FOLLOW ✅, SHARE 🙌 and COMMENT ✍ if you enjoy this idea! Also share your ideas and charts in the comments section below! This is best way to keep it relevant, support us, keep the content here free and allow the idea to reach as many people as possible. **
---
💸💸💸💸💸💸
👇 👇 👇 👇 👇 👇 Short 
SPCX Earnings | Why the Market Got SpaceX Completely WrongHello to all space nerds, rocket fans, and traders trying to catch the next launch!
SpaceX just dropped its latest earnings, so let's see whether this rocket is heading to the Moon..or making an unexpected landing back on Earth
🚀 A Massive Revenue Beat Shows SpaceX Is Scaling Fast
SpaceX delivered an impressive first earnings report as a public company, reporting Q2 revenue of $7.8 billion, a remarkable 92% year over year increase that easily topped Wall Street expectations of roughly $6.9 billion. The company also posted a smaller than expected loss of $0.09 per share, demonstrating that its rapidly expanding businesses are generating meaningful operating leverage.
The strongest contributors were Starlink's continued subscriber growth, commercial launch services, and the rapidly expanding AI segment, confirming that SpaceX is evolving beyond a pure aerospace company into a diversified technology platform
🌍Starlink Continues To Be The Company's Financial Engine
The biggest highlight remains Starlink, which has grown into SpaceX's largest revenue generator. Management reported approximately 12 million subscribers, double the level seen a year ago, while Starlink revenue climbed to roughly $4.3 billion. Enterprise and government demand also remained strong, helping offset slower consumer growth in some regions.. As satellite internet adoption expands worldwide, Starlink is becoming a recurring, high margin revenue stream that provides stability alongside the company's more cyclical launch business
🤖AI Is Becoming The Next Multi Billion Dollar Growth Driver
Beyond rockets and satellites, investors received another look at SpaceX's aggressive AI ambitions. AI related revenue surged roughly 350% year over year, supported by deeper integration with xAI technologies and strategic access to Nvidia's advanced AI chips.. Management also outlined long term plans for AI infrastructure, including future space-based data centers. While these initiatives are expensive today, they demonstrate SpaceX's strategy of building multiple high growth businesses instead of relying solely on aerospace revenue
💸Heavy Spending Overshadowed Strong Results
Despite the outstanding top-line performance, Wall Street focused on one major concern: capital expenditures. AI infrastructure investments reached levels well above analyst expectations, with billions being deployed into computing capacity, satellites, and next gen technologies. Investors worried that these elevated spending levels could delay profitability, causing the stock to fall around 7–8% in after hours trading even after the earnings beat. The upcoming expiration of a large insider lockup period added further uncertainty, increasing concerns about near term share volatility
🚀Management Is Thinking Much Bigger Than Quarterly Earnings
CEO Elon Musk emphasized that the company's strategy remains focused on long term expansion rather than maximizing near term profits. Management reiterated its vision of reaching a $100 billion annual revenue run rate in the near future while suggesting SpaceX could eventually become a $1 trillion annual revenue business by the end of the decade if Starlink, AI, launch services, and future space infrastructure continue scaling successfully. New government contracts, improving Starship capabilities, and expanding commercial demand all support this ambitious roadmap
📈Exceptional Growth, But Expect High Volatility
SpaceX continues to demonstrate one of the strongest growth stories in the public market, combining leadership in commercial spaceflight, satellite communications, AI infrastructure, and government contracts. However, investors should expect continued volatility as the company prioritizes aggressive investment over short term earnings
If management successfully converts today's enormous capital spending into durable cash flow over the next several years, SPCX could justify its premium valuation.. For long term investors willing to tolerate near term swings, the latest earnings reinforce the view that SpaceX remains one of the market's most ambitious growth companies, even if profitability may take longer to arrive
What's your target for SPCX after these earnings? Long 
SpaceX (SPCX) 2026+ Catalysts & Risks Institutional OverviewSPCX (2026+) Catalysts, Risks & Financials: Ranked Desk Views
As of August 18, 2026. Stock ~$146. Consensus rating Moderate Buy (~24 of ~32 analysts buy/strong-buy); average 12-month target ~$223 (~+53% upside); range $75 (low) → $600 (high, Morgan Stanley bull). Syndicate Catalysts Desk 12-mo target $170 (HOLD). Next earnings ~early Nov 2026 (Q3 2026). Latest reported quarter: Q2 2026 (ended Jun 30, 2026) — revenue $7.81B (+92% YoY), Connectivity/Starlink $4.29B (+66%) with $1.66B operating profit, AI $2.6B (+247%). Segment valuations, forward revenue and probabilities are Desk estimates.
🔑 Key Catalysts Driving SPCX (2026+)
🛰️ Starlink Franchise + V3 Capacity Unlock (the core engine)
Starlink is the profit engine — FY25 revenue $11.4B (+50%), ~39% operating margin, and the only profitable segment. Subscribers doubled YoY to 12.0M (30 Jun 2026) across ~160 markets. The economic step-change is the V3 satellite (Starship-launched, ~10× V2 capacity), which is what lets ARPU (~$66) stabilise as subs compound toward a modelled 20M+. Direct-to-cell rides ~65 MHz of EchoStar spectrum (~$17B, FCC-approved 12 May 2026). Impact Score: 9.4/10
🚀 Starship Block 3 + Full Reusability (the upgrade cycle)
Starship Block 3 infrastructure is building at Cape Canaveral; the first Florida flight and orbital booster-and-ship reuse are the prerequisite for Artemis lunar landing, point-to-point, V3 Starlink and larger Starshield/AI payloads. A structural ~$2,700–3,000/kg reusable-launch cost is the moat behind every other segment; sub-$100/kg Starship is the aspiration. Impact Score: 9.0/10
🤖 AI / xAI Cloud ARR Ramp (the second engine, and the optionality)
AI revenue +247% YoY to $2.6B in Q2, of which ~$1.6B was new cloud/compute-hosting revenue; adjusted EBITDA turned positive (+$1.1B) for the first time. Google (~$920M/mo) and Anthropic (~$1.25B/mo) cloud contracts run ~$26B/yr; CFO added $6.7B of new contracts and targets a $100B ARR run-rate by year-end 2026. Colossus scaled to 1.4 GW, targeting 10–20 GW by end-2027. The $60B Cursor (Anysphere) deal closed 15 Aug. Impact Score: 8.8/10
🛡️ Golden Dome / Starshield Defense Stack
~$6.45B of Golden Dome awards in May 2026 — $4.16B SB-AMTI + $2.29B SDN Backbone — plus an 18-mission SBST launch sweep (~$1.6B), together exceeding every rival's combined prototype awards. Near-vertically integrated (builds and launches), with a multi-award pipeline toward a ~600-satellite architecture and prototype milestones through end-2027. Impact Score: 8.3/10
📡 Direct-to-Cell + EchoStar Spectrum
650+ D2C satellites live, T-Mobile service since Oct 2025, and a large nationwide spectrum position. Large TAM against a global space economy projected to reach $1.8T by 2035 (WEF/McKinsey), tempered by the FCC's 23 Apr 2026 block of a separate spectrum bid and urban-coverage limits. Impact Score: 7.5/10
📈 Earnings Cadence & Estimate Revisions
Each of the first public prints is a high-conviction, high-volatility binary; Q2 confirmed +92% growth. Sell-side initiations cluster wide ($210 UBS, $235 Deutsche Bank, $250 Macquarie, $300/$600 Morgan Stanley) around a ~$223 mean, with revision momentum a flow driver. Impact Score: 7.2/10
💵 Capital-Markets / Structural (Index Inclusion + Institutional Accumulation)
Added to the Nasdaq-100 on 7 July 2026 (fast-entry rule; S&P 500 a 2027 candidate). Institutional base includes Alphabet (~$94.2B), Nvidia (~$21B), Fidelity, Saudi PIF, BlackRock, Ontario Teachers', Harvard; 1,500+ institutions disclosed. Impact Score: 7.0/10
🌘 Artemis / Lunar & Commercial Point-to-Point (long-dated optionality)
Human lunar landing (Artemis), commercial point-to-point Earth transport and "AI-in-space" data centres are large but distant, gated on Starship. Impact Score: 6.0/10
🔀 Tesla–SpaceX Merger Optionality
WSJ reported (11 Aug 2026) a clause in Musk's ~$1T Tesla pay package that could unlock on a Tesla-into-SpaceX merger; Musk denied it, prediction markets imply ~17.5% by year-end. Impact Score: 5.5/10
⚠️ Key Risks & Negative Drivers
🫧 Valuation & Multiple De-Rating
~$1.93T cap at ≈84× trailing sales with negative EPS (–$2.27) and no P/E or EV/EBITDA anchor. Roughly half the valuation rests on unproven AI. The stock already round-tripped from a $225.64 high to a $104.83 low; any guidance wobble → sharp de-rating toward Morningstar's ~$40–$62 core-business estimate. Risk Severity: 8.5/10
🔥 AI Cash Burn & Capital Needs (the SPCX "circular-financing" analog)
Capex was $18.37B in Q2 alone ($15.83B AI), >6× YoY; FY26E ~$65B outruns operating cash, with FCF deeply negative (~–$25B H1'26). KeyBanc flags ~$325B of raises over 18–24 months to fund AI compute — massive dilution risk. Risk Severity: 8.5/10
🔒 Lock-Up / Supply Overhang
Musk's ~6.4B-share June-2027 cliff equals ~4× the ~3–5% public float; ~1.7B more insider shares unlock through Dec 2026. The 6 Aug and index-inclusion days already showed "sell-the-news" behaviour. Risk Severity: 7.8/10
👑 Governance / Key-Man
Musk controls ~82.4% of votes via 10-vote super-voting stock; mandatory arbitration, a ~$52.5B derivative-suit threshold, and a Warren/SEC letter (9 Jun 2026) frame limited minority recourse. Headline/distraction risk spans his empire. Risk Severity: 7.5/10
🎯 Segment Profitability Concentration
Starlink is the only profitable leg; it subsidises Space (Starship R&D) and a loss-making AI segment. A Starlink stumble removes the group's earnings ballast. Risk Severity: 7.3/10
☁️ Cloud-Contract Cancellability
The Google and Anthropic cloud contracts (~$26B/yr) are cancellable on 90 days' notice after 31 Dec 2026 — a durability risk against which >half the AI valuation is underwritten. Risk Severity: 7.0/10
🥊 Competition & 🛰️ Execution
Launch: Rocket Lab (Neutron), Blue Origin (New Glenn), ULA (Vulcan). Starlink: Amazon Leo/Kuiper, Eutelsat-OneWeb, Chinese constellations. AI: Nvidia ecosystem, OpenAI, Anthropic, Google — where Grok holds <5% of the global assistant market. Starship remains in test (Flight 13 abort, 16 Jul); Block 3 unproven. Risk Severity: 6.5/10
📉 Macro / AI-Capex Cycle & Rates + 🔀 Earnings Volatility
Long-duration valuation is acutely rate- and sentiment-sensitive; a turn in the AI-capex cycle hits SPCX like the other mega-cap AI names. First prints have already sold off on capex shock. Risk Severity: 6.5/10
💰 Financial Scorecard (Q2 2026, ended Jun 30, 2026)
Each metric scored 0–10 on strength/quality relative to trajectory.
# Metric Latest Value Trend Strength
F1 Total revenue $7.81B +92% YoY; first public print, consensus beat 9.0
F2 Connectivity/Starlink revenue $4.29B +66% YoY; $1.66B op profit — only profitable segment 9.2
F3 Starlink subscribers 12.0M Doubled YoY; ~160 markets; ARPU ~$66 8.5
F4 Adjusted EBITDA $3.5B +191% YoY 8.0
F5 AI segment revenue $2.6B +247% YoY; adj. EBITDA +$1.1B (first positive) 7.0
F6 Cash & equivalents $93.5B vs $36.8B debt/leases post-IPO — strong liquidity 7.5
F7 Defense awards (2026 YTD) ~$6.45B Golden Dome SB-AMTI + SDN; multi-award pool 7.5
F8 Backlog / contracted cloud ~$47.5B / $14.1B Growing government + cloud commitments 7.0
F9 Net loss –$541M Narrowed from –$1.01B — improving but negative 4.5
F10 Capex $18.37B $15.83B AI; >6× YoY; ~$65B FY26E guide 2.5
F11 Free cash flow ~–$25B (H1'26) Deeply negative; implies dilutive raises 2.0
Financial composite (operating strength, avg of F1–F11): ~6.6/10 — elite top-line growth and a world-class Starlink franchise, offset by a loss-making AI leg, extreme capex intensity and negative free cash flow. (Distinct from the Desk's quality-and-trajectory scorecard of ~5.3/10, which also penalises dilution and sparse disclosure.)
🏆 Master Ranking — Catalysts & Financial Strengths Combined
Positive drivers ranked by score. Risks listed separately below.
Rank Driver Type Score (0–10)
1️⃣ 🛰️ Starlink franchise + V3 capacity unlock Catalyst 9.4
2️⃣ 🏢 Starlink revenue $4.29B (+66%, $1.66B op profit) Financial 9.2
3️⃣ 📊 Total revenue $7.81B (+92% YoY) Financial 9.0
3️⃣ 🤖 AI cloud ARR ramp toward $100B Catalyst 9.0
3️⃣ 🚀 Starship Block 3 + full reusability Catalyst 9.0
6️⃣ 📈 Starlink subscribers 12.0M (doubled YoY) Financial 8.5
7️⃣ 🛡️ Golden Dome / Starshield defense stack Catalyst 8.3
8️⃣ 💵 Adjusted EBITDA $3.5B (+191%) Financial 8.0
9️⃣ 🏦 Cash $93.5B vs $36.8B debt Financial 7.5
9️⃣ 🛡️ Defense awards ~$6.45B (2026) Financial 7.5
11️⃣ 📡 Direct-to-cell + EchoStar spectrum Catalyst 7.5
12️⃣ 📑 Earnings cadence & estimate revisions Catalyst 7.2
13️⃣ 📦 Backlog $47.5B + $14.1B contracted cloud Financial 7.0
13️⃣ 💵 Capital-markets: Nasdaq-100 + institutional accumulation Catalyst 7.0
15️⃣ 🌘 Artemis / lunar & point-to-point optionality Catalyst 6.0
⚠️ Risk Ledger (severity-ranked)
Rank Risk Severity (0–10)
1️⃣ 🫧 Valuation & multiple de-rating (~84× sales, neg. EPS) 8.5
1️⃣ 🔥 AI cash burn & ~$325B capital needs / dilution 8.5
3️⃣ 🔒 Lock-up / supply overhang (6.4B-sh Jun-2027 cliff) 7.8
4️⃣ 👑 Governance / key-man (Musk ~82% voting) 7.5
5️⃣ 🎯 Profit concentration (Starlink only profitable leg) 7.3
6️⃣ ☁️ Cloud-contract cancellability (Google/Anthropic 90-day) 7.0
7️⃣ 🥊 Competition + 🛰️ Starship execution / capex 6.5
7️⃣ 📉 Macro / AI-capex cycle & rate sensitivity 6.5
9️⃣ 📡 Regulatory / spectrum / orbital debris 5.8
🔟 🏛️ Policy / government dependence · 🔀 earnings volatility 5.5
📝 Summary Outlook (August 2026)
SpaceX enters H2 CY2026 as the most consequential public company in the space-and-AI buildout — record $7.81B quarterly revenue (+92%), a 12M-subscriber, ~39%-margin Starlink franchise that is the only profitable leg, an AI segment growing +247% with its first positive adjusted EBITDA, and ~$6.45B of Golden Dome defense wins layered on a structural launch monopoly. The Starlink V3 → Starship Block 3 cadence gives a built-in capacity upgrade cycle, and the Tesla merger is pure — and unconfirmed — optionality.
The bear case is not about demand — it's about how the growth is financed. Capex of $18.4B in a single quarter, deeply negative free cash flow, KeyBanc's ~$325B capital-need estimate, cancellable cloud contracts, and a ~6.4B-share June-2027 lock-up cliff sit against a ~$1.9T cap priced at ≈84× sales. Governance (~82% Musk voting control) leaves minority holders as passengers.
Bottom line: the core franchise is as strong as any in the buildout (operating-strength composite ~6.6/10), but the risk isn't operational execution — it's whether the AI-capex flywheel is self-sustaining or dilution-financed, and whether the June-2027 supply cliff is absorbed. We rate HOLD, $170 target: accumulate <$120, trim >$210. The next Q3 print (capex trajectory, AI ARR conversion, Starship timing) is the next decisive catalyst.
Sources: SpaceX S-1 (20 May 2026), 424B, Q2 2026 shareholder letter & transcript (4 Aug 2026); Musk 13G (30 Jun 2026); Space Systems Command award notices (SB-AMTI 29 May, SDN 26 May 2026); CNBC, Teslarati, BigGo, Yahoo Finance (earnings); Tech Times (SBST); stockanalysis.com, TipRanks (price/targets); UBS, Morgan Stanley, Deutsche Bank, Phillip Securities, KeyBanc, Morningstar (ratings); Reuters/Nvidia 13F (holders); Warren–SEC letter (9 Jun 2026); WSJ (11 Aug 2026, Tesla merger); FCC orders; Sensor Tower/Similarweb (Grok share); WEF/McKinsey ($1.8T space economy); Anysphere/Cursor close (15 Aug 2026). Long 
Short 
Long 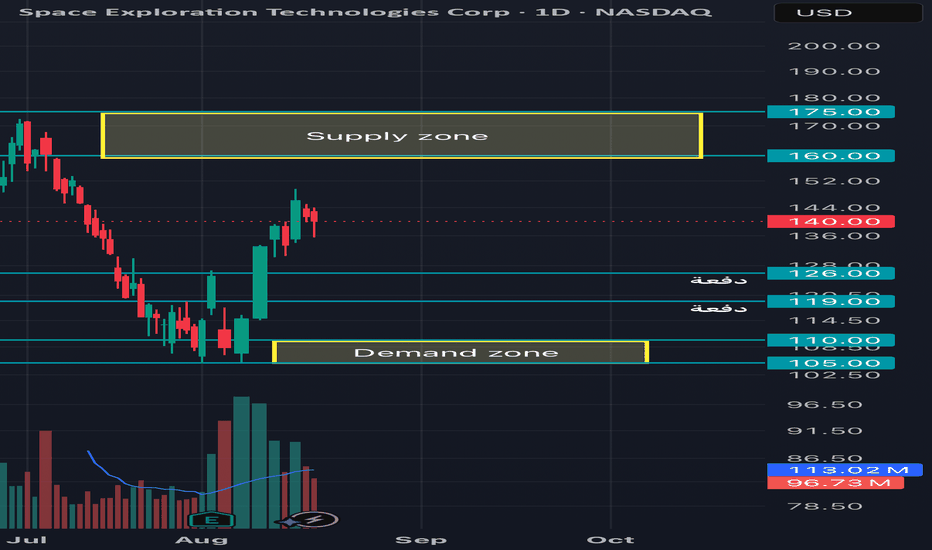
SpaceX carved a bottom. Is the markup real?🚀 The biggest IPO ever, then the hangover
SpaceX went public this June in the largest IPO in history, priced near 135 dollars a share at a valuation close to 1.8 trillion. Then came the hangover. The hype cooled, early buyers cashed out, and the price slid hard over the following weeks down into the low 100s. The contract on this chart, SPCX on Binance, is a perpetual that tracks SpaceX's share price and settles in stablecoin, so you never hold actual equity in the company. What it does give you is a clean view of a textbook pattern.
🛰️ Why buyers came back down low
The selloff did not happen in a vacuum, and neither did the bounce. SpaceX posted its first earnings as a public company in early August, and the business underneath the stock is strong.
Reports put Starlink, its satellite internet arm, near 12 million subscribers, roughly double a year earlier and the bulk of company revenue. The IPO left it holding a cash pile reported around 93 billion dollars. And it signed a deal to supply computing capacity to Google worth a reported 920 million a month. Those are the kind of hard numbers that give large buyers a reason to step in while the price is marked down.
📚 What accumulation looks like
This is a Wyckoff accumulation , a pattern named after the trader who mapped it, where big money quietly builds a position after a crash before the next leg up. It runs in a set sequence, and this chart hit every beat.
First the selling climax near 110, the panic low where heavy selling finally got soaked up. Then a bounce, then the spring , a last stab under support that shakes out the last nervous sellers and traps whoever is shorting the lows. Then a higher low, the last point of support around 118, which becomes the launchpad. Price is now above that range and marking up, which just means trending higher out of the base.
The fundamentals tell you why patient money would accumulate SpaceX down here. Wyckoff shows you the footprints they left doing it.
📊 The levels that matter now
Price is near 143 and climbing. Overhead, the first ceiling is 150, then the heavier band at 159 to 163 where old sellers and a shelf of prior volume sit stacked together, then the highs at 174 to 177 the projection is aimed at. Underneath, the markup stays healthy while 130 holds. Below that sits the 118 to 120 support, and then 110, the spring low.
⚖️ Two ways from here
The structure favors the upside: hold above 130 and grind the markup through 150 into the 159 to 163 band, where I would expect the first real fight, with 174 to 177 as the stretch target. The other side is simple. Lose 130 and price slips back into the range, and a close under 110 says that base was a trap, not accumulation. Between 130 and 150 it is still just doing the work.
Fresh off the biggest IPO ever and printing a classic accumulation. Where does this one run out of room, the 159 to 163 band or the old highs? Long 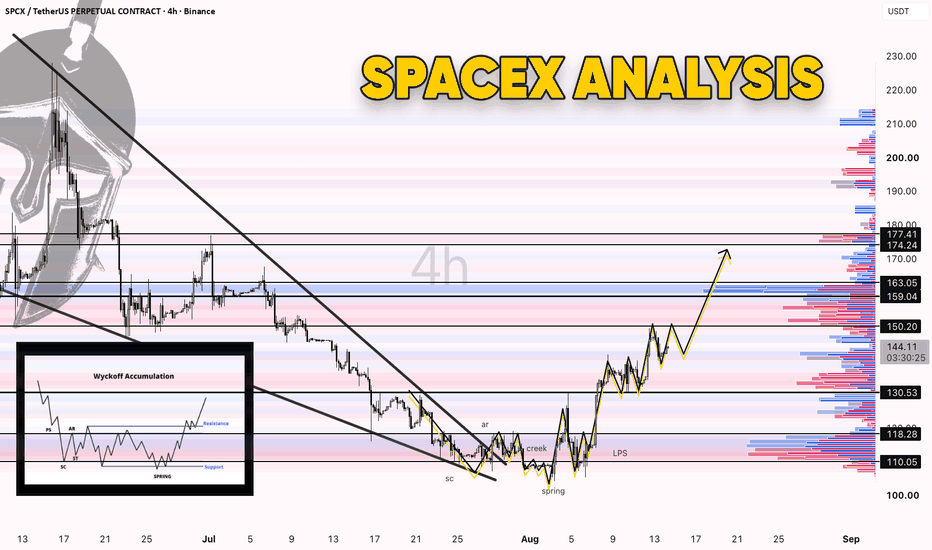
SpaceX: Why SPCX will hit $120-5/share Friday 8/14/26Here are 7 key reasons why SpaceX is likely to finish
Delayed supply from the Aug 6 unlock finally hitting
Transfers and settlement take time. Shares that became eligible on/around Aug 6 are only now (or tomorrow) freely tradable in volume for many holders. Early investors and employees who were waiting for clean settlement can start selling into any strength or simply into the open. That creates a real, if staggered, increase in available supply right as the market is digesting the prior rally.
Post-squeeze profit-taking and exhausted covering
The stock ran ~40%+ off the lows in a few sessions largely on short covering (34% → ~11%). That buying fuel is largely spent. Residual holders who bought the squeeze or institutions that rode it higher have an incentive to lock in gains, especially with another unlock (Aug 20) still hanging over the tape. Once covering slows, the path of least resistance can shift lower.
Put skew / richer put premiums as a signal of hedging demand
The elevated put premiums relative to calls (the $145 put mid notably higher than the call when the stock was near $145) show that institutions and others are paying up for downside protection. That demand does not guarantee a drop, but it means there is already capital positioned for, or willing to protect against, lower prices. If selling begins and the stock starts to slide, those put holders can become sellers of the underlying or of more puts, adding pressure. In a cascading scenario the hedging demand that created the skew can turn into actual selling flow.
Max pain and high call open interest around $140
For the Aug 14 weekly, max pain has been sitting meaningfully lower (around the mid-to-high $120s). Large call open interest clustered near $140 can act as resistance or a soft pin. If price opens softer or fails to hold above 140, dealer hedging of those calls can contribute selling. Once that level breaks, the next obvious technical and options reference is lower.
Gamma regime change if the flip breaks
Current net GEX is positive and the zero-gamma level is near ~$131.66. Above it, dealers dampen moves. If selling is strong enough to push price through that flip with volume, the regime flips: dealers become short gamma and start selling into the decline to re-hedge. That can accelerate the move toward the put wall (~$125) and, if momentum continues, toward $120. The put skew is consistent with the kind of positioning that can help fuel that acceleration once the flip is lost.
Upcoming Aug 20 unlock overhang
Even though the next large tranche is still a week away, markets often price the risk in advance. Some holders may sell ahead of it rather than wait. Combined with any residual Aug 6 shares still coming online, the supply narrative stays negative.
Valuation and lack of profitability as background pressure
The stock is still trading at extreme multiples with negative earnings. In a risk-off or “digestion” environment, that background can make downside moves sharper once they start, because there is less fundamental support to catch falling knives.
Short