Semiconductors Setting Up Base As Macro Fears CoolTaking a close look at the RIGHT chart, we can see a classic inverse head and shoulders base forming. What makes this structure especially interesting is the nesting. Inside the broader right shoulder of the main pattern, price action has carved out a smaller secondary inverse head and shoulders.
This type of pattern within a pattern often signals that buyers are stepping in early and absorbing selling pressure before the larger breakout unfolds. When the smaller structure resolves upward, it can provide the momentum needed to confirm the larger bottoming process.
The Macro Picture: Why Are Markets Not Spooked?!?!?!
On paper, the broader macro backdrop looks intimidating:
10 Yr Yield:
TVC:TNX is sitting at levels much higher than during the regional banking stress of 2023. However, instead of panicking, equities are absorbing this move. The market views current yield strength as a reflection of solid economic momentum rather than a sudden systemic crunch.
Japanese Yen:
The Yen has handed back about half of its massive run. While the initial spike caused widespread turbulence, the current retracement shows that global currency repositioning is unfolding in an orderly way without forced liquidation cascades.
Volatility Suppression:
Despite elevated bond yields and currency swings, fear gauges are not ripping higher. Heavy option premium selling and persistent dip buying continue to place a floor under pullbacks, keeping markets remarkably stable.
Key Takeaway
While macro headlines seem heavy, the underlying price action tells a calmer story. The nested inverse head and shoulders pattern highlights steady accumulation in semiconductors, while the market reaction to high yields and currency moves points to strong resilience.
Watch for the pattern neckline to clear to CONFIRM that the next upward leg is underway.
What is your take on this semiconductor setup?
Are we set for a breakout, or will macro pressure eventually weigh on equities?
TGtg! US 10 Yr Yield: The Final Squiggle and the TINA Tug of WarTake a look at the battle playing out between the 4 hour and the Daily charts on the 10 Yr Treasury.
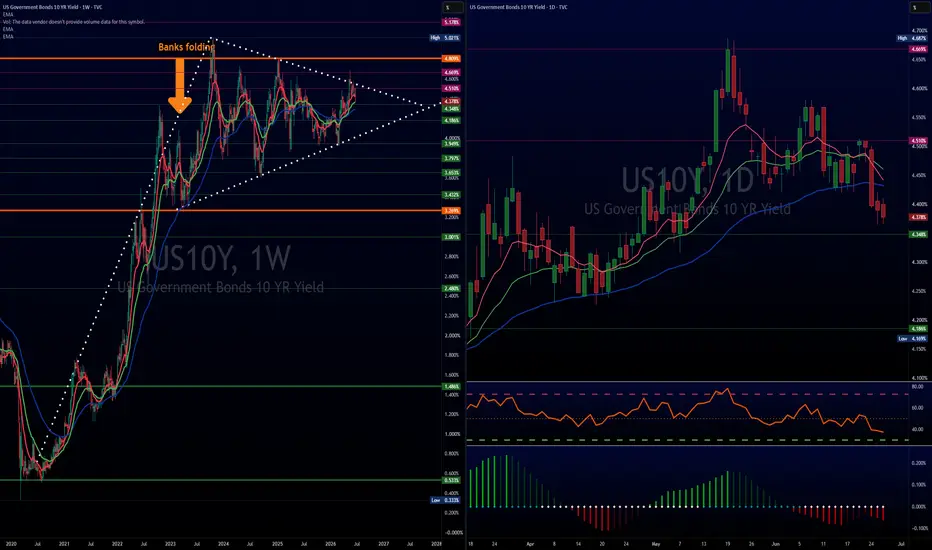
Daily, the chart saw a sudden blast of buying energy pushing yields right up against 4.80 percent. But when you zoom in to the 4Hr timeframe, the picture tells a different story.
Right now, the 4 hour chart is painting a bearish engulfing candle after tapping that 4.80 percent mark. Yields could pull back to test support or an EMA (one of the colored moving avgs), one last quick pop to trap late breakout buyers, and then roll over into the September and October window.
Daily momentum is exhausted, printing lower momentum peaks on both RSI and TTM while yields struggle to make a clean, sustained breakout through this multi month ceiling.
The Squiggle Roadmap: One Last Fakeout Pop?
Markets love to sweep liquidity and trap late traders before making their real move.
That timing lines up with the macro schedule. The Treasury ramps up its expanded debt buyback operations to absorb long bond supply, putting a natural lid on how far yields can climb heading into the Fed meeting.
Where Does TINA Fit In?
For years, the market lived by the TINA rule: There Is No Alternative to equities.
Some say TINA is gone because risk free paper yields near 5 percent. But is it really dead? If true inflation is running hotter than stated figures, a 5 percent bond still locks in negative real purchasing power. Under that view, money is eventually forced back into companies with real pricing power and hard cash flows because bonds cannot outrun true cost of living increases.
In the short term, however, nearly 5 percent on cash creates a real headwind for stock multiples because big funds can park capital safely while waiting out volatility.
The Bottom Line
TINA is not dead, but it is facing a major short term test. We are watching for that final squiggle on yields to exhaust itself against heavy overhead resistance. Once the daily chart confirms a real rejection, the stage is set for a rate pullback into autumn. The TINA Blueprint: The Squiggle RoadmapBad news dominates headlines, yet equities refuse to break. The core driver remains institutional capital flow. Big money keeps asking; "where else capital can realistically go?" That dynamic represents the classic TINA backdrop, where There Is No Alternative.
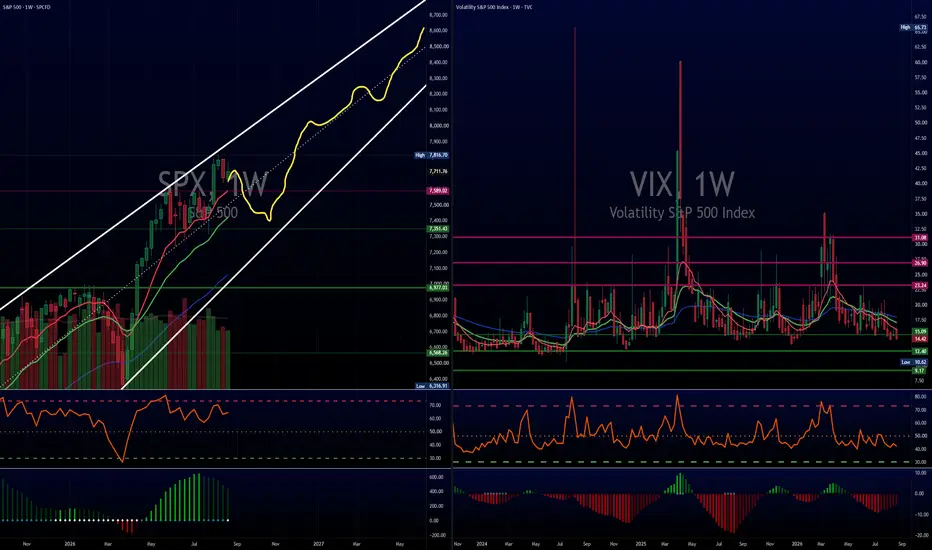
Near term headwinds are building to trigger the next move. A curling Dollar Index TVC:DXY relief bounce, firm crude oil, and stubborn bond yields TVC:TNX provide the exact catalyst needed for a seasonal shakeout.
The Squiggle Roadmap
The squiggle kicks off with a standard seasonal pullback, dropping price down into lower channel support around the 7200 to 7300 zone.
October historically marks the turning point where major market bottoms form, completing that initial downward squiggly sweep.
Volatility measures remain low while building a base. A brief pop in fear flushes out late longs and sets up the ideal bounce off the lower channel boundary.
Once that shakeout finishes and yields stabilize, the squiggle carves out a steady grind higher toward the upper channel boundary into year end and 2027.
Wide price ranges create great setups for active positioning. Respect the macro pressures, buy the structural dip on the squiggle, and let the broader TINA momentum do the rest.
Of course, these are opinions and have a great week!
TGtg! Update: The Rates Trap Springs as Yields Threaten a BreakThe macro script shifted today. The US 10 Yr yield was not running earlier in the morning, but it has suddenly caught a strong bid and is aggressively moving to retest its highs.
The front end 2 Yr yield bounced off support, and the 10 Yr RSI is hooking sharply upward. That move puts the multi month bearish momentum divergence in immediate danger of breaking to the upside. Keep in mind that this is intraday action, so the daily closing print will be critical since price action can always shift before the closing bell.
Mid Caps SP:MID : Fundamental Pressure and Weakening Momentum
Unlike previous pullbacks where institutional dip buyers stepped in rapidly, the daily RSI has dumped into the mid 30s with zero dynamic bounce.
Mid cap heavy cyclicals and capital goods manufacturers are the first to feel sticky borrowing costs eat into cash flows and profit margins.
With momentum bars rolling over, mid caps are showing clear signs of buyer exhaustion under the weight of higher rates.
Small Caps TVC:RUT : Living on Borrowed Time
Russell 2000 small caps are still hovering inside their ascending channel near 2,980, but underlying momentum is exhausted. AMEX:IWM
Small caps carry significant floating rate debt and higher refinancing vulnerability. Daily RSI has failed to expand into new high territory, signaling that the move is running on thin breadth.
With mid caps already weakening under rate pressures, small caps look vulnerable to following closely behind.
The Main Takeaway
Higher borrowing costs are no longer just background noise, they are actively forcing a repricing across cyclical assets. As long as the 10 Y yield threatens to punch through 4.75 percent, attempting to catch falling knives in equities or long duration bond plays carries high risk until a true daily rejection candle confirms at the close.
TGtg! Part 2: The Fiat Illusion and the Final EndgameWhy are stock markets still sitting near all time highs if yields are squeezing the economy?
The answer comes down to what measuring stick you are using.
When you look at SPCFD:SPX priced in nominal fiat dollars, the chart looks like an unstoppable powerhouse. But when you price AMEX:SPY in hard money like Gold, the entire illusion disappears.
At the 2k peak, one share of the SP 500 was worth roughly 5.4 ounces of gold. Today, even with the index trading above 6000, it buys under 2 ounces of gold. In real money terms, broad equities are down over 60 percent from their 2k highs and have traded sideways for two decades.
Much of the nominal equity rally is not pure productivity. It is denominator debasement. Stocks represent real assets with pricing power that mechanically rise as the currency devalues.
This connects directly to the Warsh vs Bessent standoff.
Treasury is funding long bond interventions by loading the front end with short paper. As the Fed holds short rates high, net interest on the national debt explodes. Deficits widen further, forcing even more debt issuance just to service existing obligations.
This is the fiscal dominance trap.
Either the Fed keeps rates high and breaks the debt rollover machine, or the system demands debt monetization. When private auctions get overwhelmed, the printing press becomes the only mathematical release valve left.
Watch the 2Y versus 10Y divergence closely. The front end is screaming that the policy tug of war is reaching its limit.
TGtg! Yield Ceiling and the Rates Trap: Will Stocks Truly Benefit?Instead of big institutions and foreign holders dumping their long term Treasury bonds onto the open market and spiking yields through the roof, they can now use collateral loan programs.
By borrowing cash against their bonds instead of selling them, the market avoids forced fire sales. That removes the massive supply shock and helps explain why the 10 Year yield is hitting a brick wall.
We called earlier that the Fed would not be raising rates, and the market structure is validating that more every day.
Here is what the charts are telling us on rates.
US 10 Year
That 4.75 percent level is acting as a concrete ceiling. The daily RSI shows clear momentum exhaustion making lower highs while yields pushed sideways to slightly up. On top of that, the momentum squeeze bars have completely flattened to baseline dots. The push higher ran out of gas. TVC:TNX
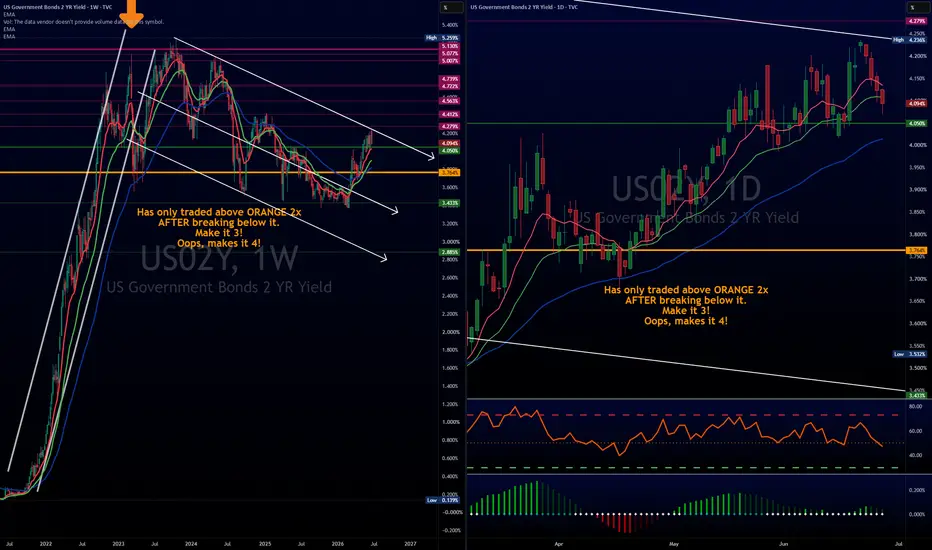
US 2 Year
The 2 Year broke its major downtrend from late 2023. However, it has formed a clean lower high recently. Front end yields are rolling into a steady downtrend, OPINION, as rate cut expectations solidify. A drop down to test the 4.06 percent zone looks like the next logical move.
The Big Question: Will stocks rise on falling yields?
Not automatically.
There are two kinds of yield drops. If yields drop because inflation is beaten and the financial system is calm, stocks celebrate. But if yields roll over because economic growth is cooling off rapidly, lower yields will not save stock earnings multiples right away.
Cyclical businesses notice slowdowns first. If yields fall while the economy cools and the Dollar Index catches a short squeeze bounce off its lows, stock dips will struggle to find aggressive buyers immediately. Yield relief is coming, but the economic backdrop will dictate whether it is a launchpad or a trap for equities.
TGtg! US Yields: Inflation Signals vs Technical Structure 2Yr 10YrWith incoming inflation prints coming in cooler than expected, macro narratives suggest yields should drop. However, the charts tell a much more nuanced story across timeframes. Let’s break down what the technical is actually signaling on the 2 and 10 Year yield.
Bullish Juice
1. RSI Trendline Breakouts
Across both the daily and weekly timeframes, RSI has decisively broken out of its long-term downtrend lines and reset into the key 50–58 equilibrium zone.
Rather than crashing below the 50 mid line (which would signal downside momentum), the indicators digested previous overbought levels through time rather than deep price decay. This is a classic trend continuation signature.
2. Multi Year Moving Average Alignment
The short and medium term EMAs (Red/Green) remain stacked above long term dynamic support (Blue) across both curves.
Daily Support (NOT SHOWN): Since March, the daily Red EMA line has repeatedly held as dynamic support for the 2Yr, proving buyers continue to defend pullbacks despite soft macro headline data.
3. Structural Break & Retest on the 10Y
The 10 Yr executed a clean breakout above its multi year descending trendline/pennant resistance and is currently in the process of a structural retest. Former overhead supply is attempting to flip into major structural demand.
The Divergence:
10Yr Yield reentering the pennant formation would be highly unusual and represent a major technical failure/fakeout. As long as a retest of support holds, the structural path of least resistance points upward toward the macro $5.17 supply ceiling.
2Yr Yield is highly sensitive to short term rate expectations. Given the cooler inflation narrative, the 2Y can easily pull back deeper into its multi-year bull flag structure without destroying the macro thesis. A retest on a support horizontal pivot remains a plausible scenario while still keeping the larger consolidation pattern intact.
Summary: Keep a close eye on Monthly candle closes. Daily/weekly breakouts are showing appetite, but until we see a decisive monthly close above the macro 5.13 / 5.17 ceilings, expect choppy retests inside these higher timeframe flags.
TGtg!
What's your take? Is the 10Y retest going to hold, or does soft macro data force a deeper pullback on the 2Y first? Drop your thoughts below! Yield Curve Twist: Why Short Rates Drop While Long Rates Surge1. Front End: Tied directly to Fed expectations
The 3 and 6 month yields are dropping because the ultra short end is anchored almost entirely to near term Fed policy.
The sharp drop on the 3 month chart shows the market aggressively pricing in Fed rate cuts or a pause in rate hikes over the immediate quarter or two. I know, CRAZY!
When traders expect short term official policy rates to come down or stay anchored, T bill yields plunge first.
2. Intermediate: The transition zone
The 1 and 2 Year charts are holding ground, hovering near their key moving average baselines.
The 2Y is often considered the barometer for the average Fed policy rate over a two year horizon. Because it sits right on the pivot line, it's torn between short term rate cut expectations and the longer term structural inflation/growth picture, causing it to trade sideways/consolidate rather than break down with the T-bills. These are usually the one uses to “manipulate” yields.
3. Long End: Driven by supply, inflation, and term premium
While short rates drop on Fed easing bets, the 10 and 30 year yields are ripping higher. This divergence happens for three main reasons:
Fiscal Supply Glut: Massive ongoing Treasury issuance forces the market to demand higher yields to absorb long term debt. TVC:TNX
Inflation Risk / "Un-anchoring": If the Fed eases policy while inflation or growth remains sticky, bondholders demand a higher term premium to offset long term inflation risk.
Uninverting the Yield Curve: After a prolonged period of yield curve inversion, curves naturally uninvert and steepen. When the long end rises faster than the short end falls, long duration bonds suffer while cash/bills rally.
The Takeaway:
The short end reflects near term policy expectations, while the long end reflects structural bond supply and macro inflation risks. Understanding this divergence keeps you from getting caught off guard when short term rates fall while long term yields continue their macro push higher.
TGTG BTC vs DXY: The Correlation TrapIt’s easy to treat the US Dollar Index TVC:DXY and Bitcoin as a strict 1:1 inverse relationship, but zooming out on the weekly chart shows it’s far less definitive on a real time basis.
Lead/Lag Mismatches & Decoupling
2025 Rollover: TVC:DXY broke down hard out of its range in early 2025, but Bitcoin didn’t immediately moon, sure it went higher but it lagged, topped out, and then followed TVC:DXY downward into a sharp multi month distribution.
2026 Bottoming: TVC:DXY carved out a structural floor zone in early 2026 and began grinding upward. Yet, Bitcoin hasn't shown the inverse elasticity traders expect; its recovery attempt stalled near $67k, leaving price structure looking heavy. There is more though.
Why BTC Remains Weak Right Now
When TVC:DXY puts in a macro bottom, it acts as a silent drain on risk assets, but the current weakness in BTC stems from a compounding liquidity squeeze:
Real Yield Pressure: With TVC:TNX (US10Y) pushing, capital is being lured toward risk free yield rather than speculative duration or crypto beta.
Loss of Independent Catalysts: During the 23 - 24 push, heavy ETF inflows and halving narratives overrode standard macro headwinds. With those flows neutralizing, BTC is exposed to broader macro tightening.
Conclusion:
The US Dollar and Yields are keeping a heavy lid on the CRYPTOCAP:BTC run. Legislature on the Crypto bill is not helping. With Bitcoin struggling hard the light at the end of the tunnel we mentioned is quickly dimming. Why Stocks Fall When Rates, Oil, and $DXY DropWhen you see a session where Rates, Oil, and DXY drop together, standard mechanical rules say stocks should rally because financial conditions are easing.
When equities fall anyway, the driver has shifted from monetary tightening to growth fears and earnings execution.
-------
1. Mega Cap Earnings and AI Capex Fatigue
After heavy volatility following mega cap tech reports like NASDAQ:TSLA and NASDAQ:GOOGL , the hangover is spilling over into broader market sentiment.
Lower yields are not boosting tech right now because investors are heavily scrutinizing Return on Invested Capital (ROIC).
When big tech signals massive infrastructure spending while profit margins shrink, multiple compression happens even if the 10 Year yield ticks down.
2. Bad News Is Bad News
When yields and the dollar drop at the exact same time equities fall, it reflects a pivot in the core market narrative:
Tightening Phase: Rates UP = Stocks DOWN (Fear of inflation and Fed).
Growth Fear Phase: Rates DOWN = Stocks DOWN (Fear of economic slowdown and earnings contraction).
If lower yields stem from softening economic indicators or profit taking after energy price spikes, the market treats lower rates as a sign of an aching economy rather than cheap money.
3. Positioning Before the Weekend
Recent sessions saw massive spikes in energy prices following Middle East tension headlines alongside equity sell offs.
Pullbacks in crude and slight drifts lower in Treasuries look like short term profit taking and weekend positioning rather than a real shift back to risk on mode.
Conclusion
When correlation flips and stocks fall with yields and the dollar, the market is no longer panicking about rate hikes. It is repricing corporate earnings growth, margin sustainability, and overall macro demand.
Short Term Gold Rally over?RSI and TTM are looking better while price continues to sag. This is a classic bullish divergence in a strong down trend. In other words, selling momentum is slowing down—the bears are running out of aggressive velocity.
But price requires capital inflows to actually turn. Until price breaks above that daily white descending trendline on Gold, momentum is just an early warning system, not a buy signal.
Do Interest Rates Have an Effect?
Opportunity Cost:
Neither Gold nor Silver pays a yield or dividend. When the 10 year Treasury yields climb toward 4.80% and potentially target 5.20%, institutional capital gets guaranteed nominal returns in Treasuries.
The "Real Rate" Clamp:
If nominal bond yields rise faster than inflation expectations, real yields rise. High real yields make holding non yielding metals expensive to hold on balance sheets, triggering fund outflows out of Gold and Silver.
The Double Whammy:
When both TVC:DXY $ and TVC:TNX break out simultaneously (as we mapped out on previous high timeframe charts), precious metals face a double barreled headwind:
1) A stronger dollar makes metals more expensive for foreign buyers.
2) Higher yields raise the opportunity cost of holding metals over cash/bonds.
The Takeaway
If TVC:DXY pushes cleanly above 101 and $ TVC:TNX breaks out above 4.80% toward 5.20%, precious metals will likely break down through these support zones, regardless of how nice the daily RSI divergence looks.
For the momentum divergence to turn into a real price bottom, we need to see either rates or the dollar hit their overhead macro resistance and turn lower. Until then, the trendline and macro headwinds remain in control. 10Y Weekly Mega Symmetrical Triangle Pt2I prefer charts, they can’t lie. Unless of course they start fudging data, but that is another topic for another day, maybe…
Here’s a breakdown of the macro thesis outside of technical jargon. Like Nacho Libre would say, “the nitty gritty”, where the logic holds firm, where the trade offs lie, and the counter forces at play.
Supply/Demand Imbalance in Treasuries
Issuance Problem
U.S. Treasury continues to issue MASSIVE volumes of debt to fund federal deficits. When foreign central banks and traditional institutional buyers reduce their net purchases, the primary dealers must absorb the excess supply.
Price Discovery
To entice domestic private capital (pension funds, money market funds, insurance firms) to step in and absorb that supply, yields must rise to offer a sufficient risk/term premium.
Fed’s Dilemma: Print or Suffer Tightening
If long term yields surge high enough to threaten market functioning or make government debt service unsustainable, the Fed faces two stark options:
Option A: Yield Curve Control / QE
Mechanism
Fed steps in as the buyer of last resort to peg yields or buy Treasuries via balance sheet expansion.
Outcome
Expanding the balance sheet (monetizing the debt) increases money supply velocity. If done while inflation is still elevated, real yields turn negative, degrading the purchasing power of the USD and driving capital into tangible assets, commodities, and hard currencies.
Option B: Let Rates Float High
Mechanism
Fed refrains from quantitative easing, allows market supply and demand to dictate yields.
Outcome
Borrowing costs jump across mortgages, corporate credit, and municipal debt. This aggressively tightens financial conditions, slowing economic activity and squeezing regional banking balance sheets holding lower yielding duration risk.
Counter Perspective
The Flypaper Effect of High Yields:
At 5%+, U.S. Treasuries begin to aggressively compete with equities and corporate bonds for yield. Risk averse institutional capital often rotates heavily into risk free Treasuries at those levels, naturally capping the yield spike without requiring immediate Fed intervention.
Economic Slowdown
Higher long term yields act as a self correcting brake on economic growth. As mortgage rates and corporate debt costs rise, demand cools, eventually lowering inflation expectations and pulling yields back down.
Key Takeaway
Healthier technical footprint on the 10 Yr vs the 2 Yr confirms that long term fiscal deficits, debt supply, and inflation risks are currently pushing yields up far more aggressively than short term Fed policy expectations alone.
Yields Squeezing, Dollar Running, and What It Means for GoldIf you look at the charts right now, a major technical and macroeconomic setup is unfolding across Treasury Yields, the US Dollar Index TVC:DXY , and Gold.
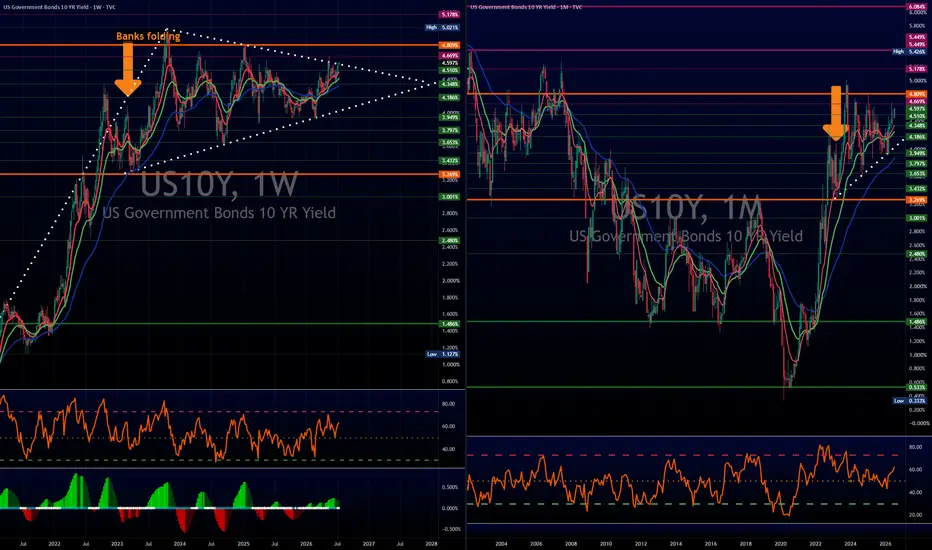
1. Weekly Squeeze on 10 Year Yields
The weekly chart for TVC:TNX shows price action is coiling tightly into the apex of a multi year pennant pattern. The moving averages (red and green lines) are stacked underneath price, curling upward, and providing dynamic support. At the same time, weekly momentum indicators like the TTM Squeeze are turning green. Everything points toward a potential upside breakout sooner rather than later.
2. Monthly Structural Floor
Zooming out to the monthly 10 Year Yield chart, we see that yields are respecting a long term upward trendline that started in 202 after the 2020 lows. Every time yields pull back to key support levels, buyers step in aggressively. Long term interest rates have established a clear higher floor.
3. Triple Threat: Yields, Dollar, and Paper Gold
When 10 Year Yields and the 2 Year Yield rise together, they pull the US Dollar Index up with them. This creates a short term liquidity crunch for precious metals.
Opportunity Cost: Treasury yields offer a guaranteed return. When nominal rates rise, traders dump non yielding paper Gold futures to grab paper yield.
Technical Pressure: On daily charts, this dollar and yield push keeps Gold trapped inside a downward sloping channel heading toward key support near $4k.
4. Macro Picture: Running Dollar vs Real Inflation
Why are yields staying high? Because real world inflation is sticky. Official government numbers use formulas like substitution and quality adjustments that smooth out true cost of living increases. But everyday essentials like food, insurance, utilities, and housing have increased significantly over the last few years.
While a surging Dollar and rising yields push paper Gold down in the short term, they also signal growing national debt burdens and loss of cash purchasing power. Over a longer horizon, short term paper pressure gives way to physical demand, and hard assets eventually decouple from dollar strength.
Conclusion:
Respect the short term daily trend while DXY and yields push higher, but keep your eye on the bigger macro picture as structural inflation remains real.