Session Killzones + Opening Range [verticetrading]SESSION KILLZONES + OPENING RANGE
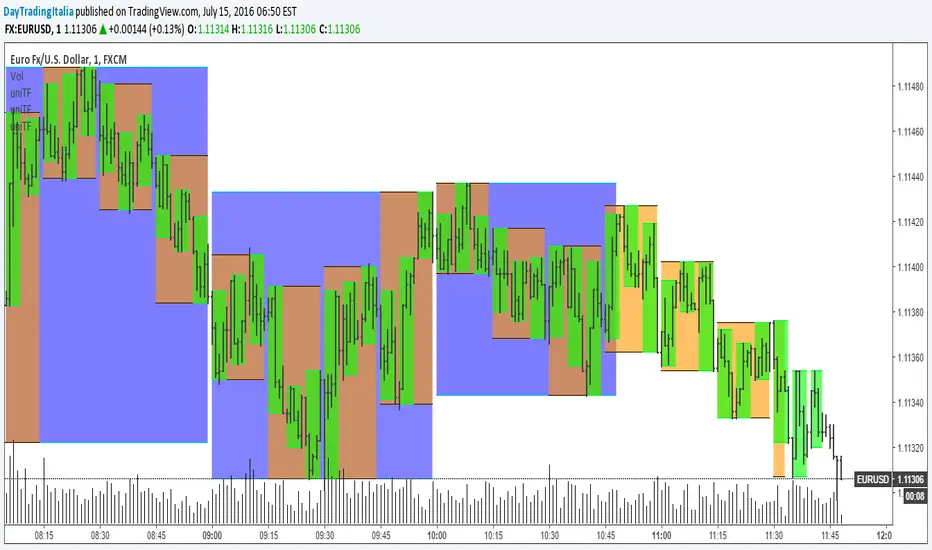
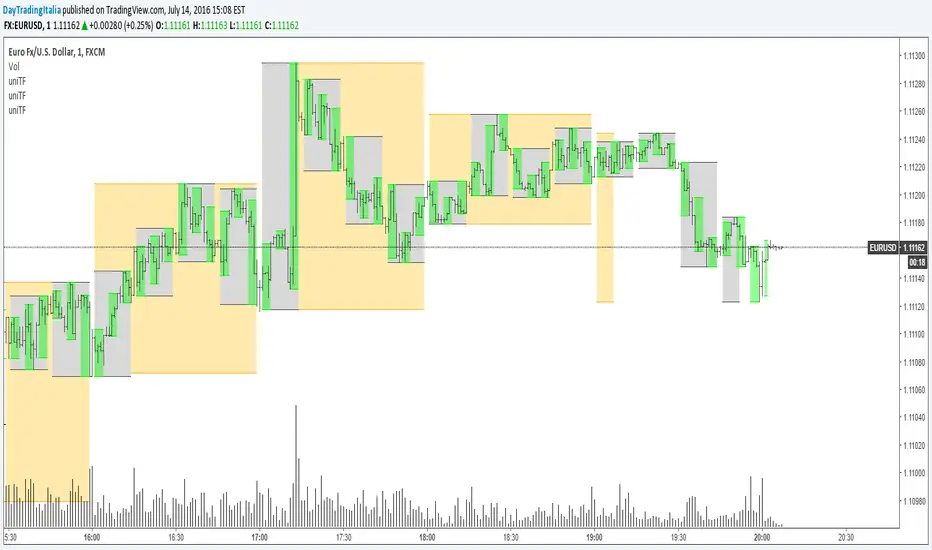
The Session Killzones + Opening Range indicator draws the Asia, London and New York sessions as live boxes on the chart, highlights each session's opening range, and adds a "fuel gauge" that compares the session's developing range with the symbol's own recent sessions.
🔶 USAGE
Add the indicator to an intraday chart of a market that trades across sessions (gold, forex, crypto, index futures). Each active session appears as a shaded box with its name; the first minutes of the session are shaded darker as the opening range. When price closes beyond that range, an alert can fire.
🔹 Reading the fuel gauge
* The session label shows the current range as a percentage of the typical range of that session's last 20 instances, e.g. "London — range at 137% of typical".
* Below roughly 60% late in the session: a quiet session; breakouts tend to have less follow-through.
* Around 60-110%: a normal session.
* Above roughly 120%: the session has already travelled more than usual; late entries face a statistically stretched move.
* The gauge measures amplitude, not direction: a 137% session can be a straight trend or a range that ends where it started — the candles inside the box tell you which.
🔹 Alerts
* Session opened.
* Opening range broken up / broken down (confirmed close only).
🔶 DETAILS
Sessions are evaluated in the timezone you choose (New York by default, the usual anchor for FX and metals). For every session the script stores the final range of its last 20 instances and divides today's developing range by that average; the label appears once a few sessions of history exist. Since a range can only grow, the percentage rises during the session and never falls, so the same 40% means "slow, still has room" mid-session and "a quiet day" at the close. Opening-range breakouts are detected on confirmed closes only, so nothing repaints. The statistics describe the loaded history of the chart only.
🔶 SETTINGS
🔹 General
* Language / Idioma: interface language (English by default, Spanish available). Every setting, tooltip and alert has an English label.
* Sessions timezone: the timezone the session hours refer to (Exchange, UTC, New York, London, Central America, Mexico City, Madrid/Paris/Berlin, Tokyo).
* Opening range (minutes): length of the opening range, 30 by default.
🔹 Session: Asia / London / New York
* Show: toggles the session.
* Hours: the session's time window in the selected timezone (defaults 18:00-03:00, 03:00-11:30 and 08:00-17:00 New York time).
* Color: box and label color.
Educational tool, not financial advice. A news day can print 200%; the gauge tells you when the context deserves attention, not where price will go. Trading involves risk. Indicator

Indicator

Session Volume Pulse [TSL]Session Volume Pulse shows whether the current bar's volume is unusual for this exact time of day — not just compared to the last 20 bars, but compared to the same minute across the last 14 trading sessions (configurable 5–60).
Most volume indicators give you raw volume and a moving average. The problem: the 9:30 AM open is always busy, and noon is always quiet. A 3x spike at 9:30 means nothing — that's just what 9:30 looks like. A 3x spike at noon is genuinely unusual. This indicator makes that distinction obvious.
═══ WHAT YOU SEE ═══
Two visual signals on the volume pane:
1. A subtle blue baseline line showing the typical volume for this exact minute of the trading day, averaged across the past 14 sessions. The line curves upward at the open, dips through lunch, rises into the close — because that's what the average session looks like.
2. A multiplier label drawn only on bars where volume is ≥ 2.5x the recent 12-bar average (e.g., "2.7"). Most bars don't get a label. The ones that do are the bars worth attention. Position and orientation are both configurable — see the settings reference below.
That's it. No divergence tints. No z-score overlay. No nine-row corner table. Two signals, both readable at a glance.
═══ HOW TO READ IT ═══
- Bar above baseline + no spike label = elevated participation, soft confirmation
- Bar at or below baseline + no spike label = normal session activity, ignore
- Spike label appears = conviction event worth attention
The combination matters most: a spike at the cash open is less meaningful than a spike at noon, because the baseline tells you what's typical for each minute.
═══ CRITICAL SETTING: BARS PER SESSION ═══
This is the only setting most users need to configure for non-default markets. The default of 0 auto-detects assuming 24h trading, which is correct for crypto/forex and close enough for ~23h futures (NQ, ES, MNQ, MES at 15m).
For US stocks during regular trading hours (6.5h), override to:
- 1m chart: 390
- 5m chart: 78
- 15m chart: 26
- 30m chart: 13
For futures across other timeframes:
- 1m: 1380
- 5m: 276
- 15m: 92 (or leave at 0)
- 30m: 46
- 1h: 23
On 4h and higher timeframes, disable "Show time-of-day baseline" — there aren't enough bars per session for the baseline math to be meaningful. The spike detection still works fine.
═══ TUNING THE LOOKBACK ═══
The "Baseline sessions to average" setting controls how many past sessions feed the time-of-day average. The default is 14, but the right choice depends on your style:
- 5–10 sessions: very responsive, adapts fast after regime shifts (vol expansion, holiday weeks). More spike-alert noise.
- 14 sessions: DEFAULT. Two trading weeks of context. Balances responsiveness with stability. Best for active intraday on 15m futures.
- 21 sessions: one calendar month. More stable baseline, fewer false-spike alerts. Slower to adapt to new regimes.
- 30–60 sessions: swing/positioning context. Very stable, very slow to update. Single high-impact event days (FOMC, CPI) linger in the average for weeks.
Rule of thumb: too many marginal spike alerts? Increase the lookback. Baseline feels stale after a vol regime change? Decrease it.
═══ ALERTS ═══
Two alert conditions, both useful:
1. "Volume spike" — fires when volume hits the spike threshold. Use for multi-symbol monitoring.
2. "Crossed session baseline" — fires when volume transitions from below to above the typical level (or vice versa). Quieter signal indicating regime change.
═══ HONEST LIMITATIONS ═══
- Does not predict direction. A spike with a green close is bullish confirmation; a spike with a red close is often capitulation or distribution. The indicator surfaces the conviction event; reading direction is on you.
- Does not work on symbols without volume. Most spot forex pairs on retail platforms report tick count, not volume. Use the equivalent futures contract (6E, 6J, 6B) for real volume analysis on forex.
- Needs history. On a fresh symbol with fewer sessions of historical bars than your lookback setting, the baseline averages whatever's available and may be choppy for the first few sessions.
- Not session-aware for time changes. DST transitions or holiday-shortened sessions in the lookback window will offset the baseline by a bar or two until they roll out of the average.
═══ WHY OPEN SOURCE ═══
Closed-source indicators in finance are a known yellow flag — they often do less than claimed or rely on lookahead bias to look better in backtests. Every line of this script is readable. Audit the math, fork it, modify it for your strategy. The math is straightforward by design.
═══ SETTINGS REFERENCE ═══
Acceleration lookback (bars): 12 default. How many recent bars feed spike detection. Use 20 for daily charts.
Spike threshold (× average): 2.5 default. How far above average a bar must be to get a label. Lower = more labels.
Baseline sessions to average: 14 default (range 5–60). See "Tuning the Lookback" above.
Bars per session: 0 (auto). See table above.
Spike label position: Four options.
- On bar (top) — text floats just inside the top of the orange bar
- On bar (middle) — text centered inside the bar
- On bar (bottom) — text sits at the base of the bar (DEFAULT)
- Below bar (pill) — legacy orange pill anchored below the bar
Spike label orientation: Two options.
- Vertical (stacked) — each character on its own line. Best for narrow bars on lower timeframes. DEFAULT.
- Horizontal — standard single-line text. Best for wider bars on higher timeframes or when bar width comfortably fits the ratio.
Position and orientation are independent — any of the four positions can use either orientation, giving you eight visual combinations.
Colors: Six configurable colors for bars, baseline, and labels.
═══════════════════════════════════════════════════════════════
Maintained by TrailingStopLoss.com — more free, open-source trading tools at trailingstoploss.com/tradingview-indicators
═══════════════════════════════════════════════════════════════
Disclaimer: This is an analytical tool that displays publicly available volume data with a time-of-day baseline overlay. It does not predict price direction or guarantee any trading outcome. Volume spikes can precede continuation, reversal, or no follow-through. Trading futures and equities involves substantial risk of loss. For educational purposes only. Indicator

Pro Levels & Zones [MTE]Pro Levels & Zones
An intraday futures overlay that combines pivot-based supply and demand zones with multi-session key levels and a confluence-based signal filter. The core idea is that zones alone generate too many potential entries — by requiring alignment across multiple independent factors before labeling a zone touch, the indicator filters out low-conviction setups and highlights where several references converge.
HOW IT WORKS
Supply & Demand Zone Detection
Zones are built from 60-minute pivot highs and pivot lows using a 3-bar left / 3-bar right pivot structure. When a pivot high is confirmed, the area between the candle's high and the top of its body becomes a supply zone (red). When a pivot low is confirmed, the area between the candle's low and the bottom of its body becomes a demand zone (green). Zones extend forward in real time and are automatically removed when price closes beyond the zone boundary or when the zone exceeds a configurable age limit (default: 500 bars). Only the 3 most recent zones per side are kept to avoid chart clutter.
Confluence Scoring (signal filter)
When price enters a fresh (unused) zone, the indicator checks up to 5 independent factors before printing a signal:
1. Volume delta direction — estimated from the bar's close position within its range. A buy signal requires positive delta; a sell signal requires negative delta.
2. VWAP proximity — whether price is near the session VWAP (within 0.15% of current price).
3. Key level proximity — whether price is near a relevant prior-session level (PDH, PDL, PMH, PML).
4. POC proximity — whether price is near the intraday volume Point of Control.
5. VWAP trend bias — whether price is on the "right side" of VWAP for the signal direction (buy below VWAP, sell above).
Each matching factor adds 1 to the score. The signal label displays the count (e.g., "Buy 4/5") so traders can see at a glance how many factors aligned. A configurable cooldown (default: 12 bars) prevents repeated signals in the same area. An additional filter requires bearish candle close for sells and bullish candle close for buys.
Note: The confluence score is simply a count of how many factors happen to align at the moment of zone contact. A higher count does not predict or guarantee a successful trade. It is a filtering tool, not a performance metric.
SESSION LEVELS & KEY LEVELS
The indicator tracks and displays levels from multiple sessions:
- London session high/low — plotted as live-updating steplines during the session, then held after session close.
- Asia session high/low — same behavior, off by default.
- Key levels drawn as dashed horizontal lines: Previous Day High/Low/Close (PDH/PDL/PDC), Pre-Market High/Low (PMH/PML), Previous Week High/Low (PWH/PWL), Overnight High/Low (ONH/ONL), and the RTH Opening Print. All are off by default and individually toggleable.
Previous day and week values use request.security() with a offset and lookahead_on, which is the standard method to reference the prior completed period without future data leakage.
ADDITIONAL TOOLS (all off by default)
- VWAP — standard session-anchored VWAP using ohlc4 as source.
- POC — intraday volume Point of Control calculated by distributing each bar's volume into a 100-bin histogram across the RTH price range, then finding the bin with the highest accumulated volume. Resets daily.
- Fair Value Gaps — bullish and bearish imbalances detected when a gap exists between bar 's low and bar 's high (or vice versa), filtered by a minimum percentage size (default: 0.15%). FVGs auto-expire after 40 bars. Maximum 6 active FVGs.
- Opening Range — plots the RTH opening range as a box (15 or 30 minute, configurable). Extends through the session.
WHY THIS COMBINATION
Most zone-based approaches generate signals every time price touches a zone, regardless of context. This indicator addresses that by requiring zone contact AND directional volume AND candle confirmation before printing anything, then layering additional context (VWAP, key levels, POC) as a visible confluence count. The result is fewer signals that occur only at zones where multiple independent references happen to converge.
The session levels (London, Asia, pre-market, overnight) are included because futures often react at session boundaries, and having them as toggleable overlays avoids needing separate indicators cluttering the chart.
HOW TO USE
1. Apply to a 1-15 minute intraday futures chart (defaults tuned for NQ on 5 min).
2. Adjust "Min Zone Size" for your instrument (NQ: 20-50 pts, ES: 5-15 pts).
3. Watch for Buy/Sell labels at zone touches. Higher confluence counts (4/5, 5/5) mean more factors aligned — use your own judgment on whether the context supports a trade.
4. Toggle key levels on/off depending on which session references matter to your trading approach.
5. All features are independently toggleable. Start with zones + signals, then add levels as needed.
DEFAULT SETTINGS
- Zones: ON, min size 20 pts, max age 500 bars
- Signals: ON, cooldown 12 bars, volume delta confirmation ON
- London session levels: ON
- All other levels and tools: OFF
LIMITATIONS
- Volume delta is estimated from bar close position within range — it is not true order flow data.
- POC uses a 100-bin histogram which is an approximation, not tick-level volume profile.
- Confluence scoring counts factor alignment but does not predict outcomes. Past confluence patterns do not guarantee future results.
- Zone detection has a 3-bar lag due to pivot confirmation.
- Designed for futures instruments. Adjust zone size settings for other markets.
Indicator

Indicator

ADR**Overview**
This indicator displays the **Average Daily Range (ADR)** and **ADR Percentage** in a customizable table on your chart.
While the standard ATR (Average True Range) is a popular metric for volatility, it accounts for price gaps (e.g., overnight moves). **ADR**, on the other hand, strictly measures the average distance between the **High** and **Low** of price bars, completely ignoring gaps.
**Why use ADR instead of ATR?**
* **Day Trading:** For intraday traders (Forex, Crypto, Futures), ADR is often preferred because it calculates the "tradable" range of the day. It answers the question: *"On average, how much does this asset move from High to Low?"*
* **Target Setting:** ADR is excellent for projecting daily highs and lows. If price has already moved 100% of its ADR, the statistical probability of further extension decreases.
* **Pure Volatility:** It filters out the noise of overnight gaps to show pure intraday volatility.
**Calculation Logic**
* **ADR:** Calculated using a Simple Moving Average (SMA) of the `High - Low` range over the specified length.
* Formula: `SMA(High - Low, Length)`
* **ADR%:** Shows the ADR relative to the current price.
* Formula: `(ADR / Current Close) * 100`
**Features**
* **Clean Dashboard:** A minimalist table displays the ADR value and the ADR %.
* **Customizable:** You can change the calculation length (default is 14) and move the table to any corner of the chart (Top/Bottom, Left/Right) to fit your workspace.
**Settings**
* **ADR Length:** The lookback period for the average (Default: 14).
* **Display Position:** Choose where the table appears on your screen. Indicator

Indicator

Indicator

Indicator

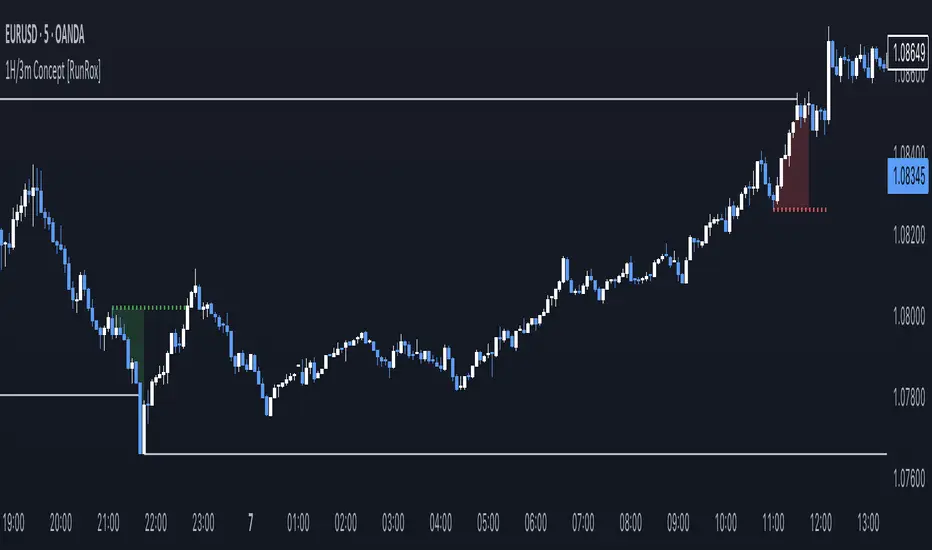
1H/3m Concept [RunRox]🕘 1H/3m Concept is a versatile trading methodology based on liquidity sweeps from fractal points identified on higher timeframes, followed by price reversals at these key moments.
Below, I will explain this concept in detail and provide clear examples demonstrating its practical application.
⁉️ WHAT IS A FRACTALS?
In trading, a fractal is a technical analysis pattern composed of five consecutive candles, typically highlighting local market turning points. Specifically, a fractal high is formed when a candle’s high is higher than the highs of the two candles on either side, whereas a fractal low occurs when a candle’s low is lower than the lows of the two adjacent candles on both sides.
Traders use fractals as reference points for identifying significant support and resistance levels, potential reversal areas, and liquidity zones within price action analysis. Below is a screenshot illustrating clearly formed fractals on the chart.
📌 ABOUT THE CONCEPT
The 1H/3m Concept involves marking Higher Timeframe (HTF) fractals directly onto a Lower Timeframe (LTF) chart. When a liquidity sweep occurs at an HTF fractal level, we remain on the same LTF chart (since all HTF fractals are already plotted on this lower timeframe) and wait for a clear Market Structure Shift (MSS) to identify our potential entry point.
Below is a schematic illustration clearly demonstrating how this concept works in practice.
Below is another 💡 real-chart example , showing liquidity in the form of a 1H fractal, swept by a rapid impulse move. Immediately afterward, a clear Market Structure Shift (MSS) occurs, signaling a potential entry point into the trade.
Another example is shown below, where we see our hourly fractal, from which price clearly reacts, providing an opportunity to search for an entry point.
As illustrated on the chart, the fractal levels from the higher timeframe are clearly displayed, but we’re working directly on the 5-minute chart. This allows us to remain on one timeframe without needing to switch back and forth between charts to spot such trading setups.
🔍 MTF FRACTALS
This concept can be applied across various HTF-LTF timeframe combinations. Although our examples illustrate 1H fractals used on a 5-minute chart, you can effectively utilize many other timeframe combinations, such as:
30m HTF fractals on 1m chart
1H HTF fractals on 3m chart
4H HTF fractals on 15m chart
1D HTF fractals on 1H chart
The key idea behind this concept is always the same: identify liquidity at fractal levels on the higher timeframe (HTF), then wait for a clear Market Structure Shift (MSS) on the lower timeframe (LTF) to enter trades.
⚙️ SETTINGS
🔷 Trade Direction – Select the preferred trading direction (Long, Short, or Both).
🔷 HTF – Choose the higher timeframe from which fractals will be displayed on the current chart.
🔷 HTF Period – Number of candles required on both sides of a fractal candle (before and after) to confirm fractal formation on the HTF.
🔷 Current TF Period – Sensitivity to the impulse that sweeps liquidity, used for identifying and forming the MSS line.
🔷 Show HTF – Enable or disable displaying HTF fractal lines on your chart. You can also customize line style and color.
🔷 Max Age (Bars) – Number of recent bars within which fractals from the selected HTF will be displayed.
🔷 Show Entry – Enable or disable displaying the MSS line on the chart.
🔷 Enable Alert – Activates TradingView alerts whenever the MSS line is crossed.
You can also enable 🔔 alerts, which notify you whenever price crosses the MSS line. This significantly simplifies the process of identifying these setups on your charts. Simply configure your preferred timeframes and wait for notifications when the MSS line is crossed.
🔶 We greatly appreciate your feedback and suggestions for improving the indicator! Indicator

Indicator

Indicator

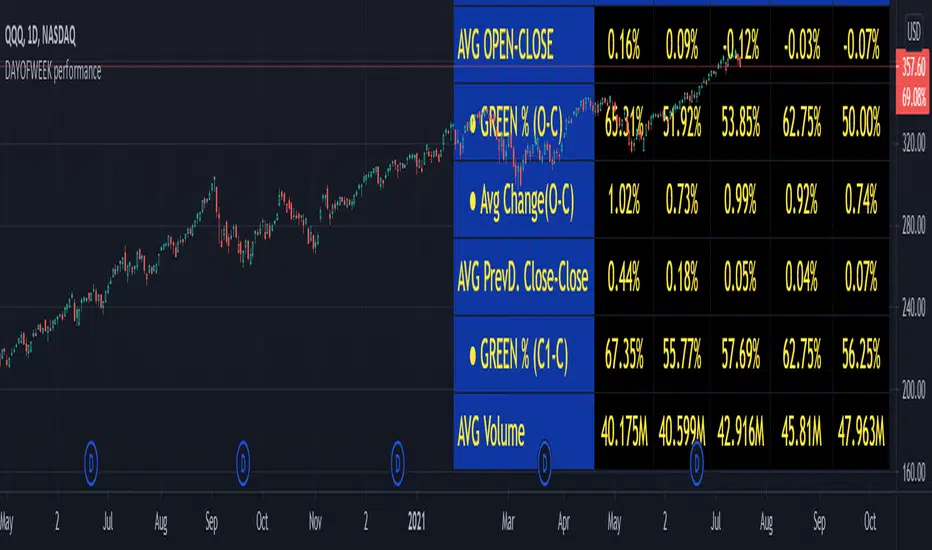
DAYOFWEEK performance1 -Objective
"What is the ''best'' day to trade .. Monday, Tuesday...."
This script aims to determine if there are different results depending on the day of the week.
The way it works is by dividing data by day of the week (Monday, Tuesday, Wednesday ... ) and perform calculations for each day of the week.
1 - Objective
2 - Features
3 - How to use (Examples)
4 - Inputs
5 - Limitations
6 - Notes
7 - Final Tooughs
2 - Features
AVG OPEN-CLOSE
Calculate de Percentage change from day open to close
Green % (O-C)
Percentage of days green (open to close)
Average Change
Absolute day change (O-C)
AVG PrevD. Close-Close
Percentage change from the previous day close to the day of the week close
(Example: Monday (C-C) = Friday Close to Monday close
Tuesday (C-C) = Monday C. to Tuesday C.
Green % (C1-C)
Percentage of days green (open to close)
AVG Volume
Day of the week Average Volume
Notes:
*Mon(Nº) - Nº = Number days is currently calculated
Example: Monday (12) calculation based on the last 12 Mondays. Note: Discrepancies in numbers example Monday (12) - Friday (11) depend on the initial/end date or the market was closed (Holidays).
3 - How to use (Examples)
For the following example, NASDAQ:AAPL from 1 Jan 21 to 1 Jul 21 the results are following.
The highest probability of a Close being higher than the Open is Monday with 52.17 % and the Lowest Tuesday with 38.46 %. Meaning that there's a higher chance (for NASDAQ:AAPL ) of closing at a higher value on Monday while the highest chance of closing is lower is Tuesday. With an average gain on Tuesday of 0.21%
Long - The best day to buy (long) at open (on average) is Monday with a 52.2% probability of closing higher
Short - The best day to sell (short) at open (on average) is Tuesday with a 38.5% probability of closing higher (better chance of closing lower)
Since the values change from ticker to ticker, there is a substantial change in the percentages and days of the week. For example let's compare the previous example ( NASDAQ:AAPL ) to NYSE:GM (same settings)
For the same period, there is a substantial difference where there is a 62.5% probability Friday to close higher than the open, while Tuesday there is only a 28% probability.
With an average gain of 0.59% on Friday and an average loss of -0.34%
Also, the size of the table (number of days ) depends if the ticker is traded or not on that day as an example COINBASE:BTCUSD
4 - Inputs
DATE RANGE
Initial Date - Date from which the script will start the calculation.
End Date - Date to which the script will calculate.
TABLE SETTINGS
Text Color - Color of the displayed text
Cell Color - Background color of table cells
Header Color - Color of the column and row names
Table Location - Change the position where the table is located.
Table Size - Changes text size and by consequence the size of the table
5 - LIMITATIONS
The code determines average values based on the stored data, therefore, the range (Initial data) is limited to the first bar time.
As a consequence the lower the timeframe the shorter the initial date can be and fewer weeks can be calculated. To warn about this limitation there's a warning text that appears in case the initial date exceeds the bar limit.
Example with initial date 1 Jan 2021 and end date 18 Jul 2021 in 5m and 10 m timeframe:
6 - Notes and Disclosers
The script can be moved around to a new pane if need. -> Object Tree > Right Click Script > Move To > New pane
The code has not been tested in higher subscriptions tiers that allow for more bars and as a consequence more data, but as far I can tell, it should work without problems and should be in fact better at lower timeframes since it allows more weeks.
The values displayed represent previous data and at no point is guaranteed future values
7 - Final Tooughs
This script was quite fun to work on since it analysis behavioral patterns (since from an abstract point a Tuesday is no different than a Thursday), but after analyzing multiple tickers there are some days that tend to close higher than the open.
PS: If you find any mistake ex: code/misspelling please comment.
Indicator

Indicator

Indicator

Indicator