Squeeze Regime Map [BSL]Squeeze Regime Map classifies volatility contraction, confirmed release and
directional expansion as explicit states. It answers “what volatility regime
is the current chart in?”, not “what trade should I take?”
This is an original BarState Labs implementation built from an independent
written specification. It does not reproduce another publication's formula,
defaults, interface, chart grammar or source code.
HOW IT WORKS
Normalized volatility is Wilder ATR divided by close and expressed as a
percentage:
`nATR = RMA(True Range, ATR length) / close × 100`
The current nATR is ranked inside the latest complete rolling window using an
inclusive percentile:
`VOL PCTL = 100 × count(window values <= current nATR) / window size`
Inclusive ties are deliberate. The implementation uses this explicit bounded
definition rather than relying on an opaque rank function.
Directional impulse is displacement over the selected momentum length,
normalized by current ATR and then EMA-smoothed:
`impulse = EMA((close - close ) / ATR, smoothing)`
Impulse labels the direction of a confirmed release only when its magnitude is
at least the configured minimum. A weak release is recorded as unresolved
instead of being forced up or down.
STATE MACHINE
- Compression begins when VOL PCTL is at or below the compression-entry level.
- Compression persists until the separate release threshold is reached. This
hysteresis prevents repeated threshold chatter.
- The first qualified exit is a one-bar Release Up or Release Down state and a
one-bar +1 or -1 machine-readable pulse.
- A weak exit returns to Neutral and increments the unresolved ledger.
- On the next bar, a directional release becomes Expansion only when volatility
reaches the expansion threshold and impulse keeps the same qualified
direction.
- Expansion persists while volatility remains above the release threshold and
direction agrees. Otherwise the state returns to Neutral.
- A new compression always takes transition precedence.
The default thresholds are 20 / 40 / 70 percentile. They must satisfy
`compression < release <= expansion`; an invalid order renders `CONFIG ERROR`
and freezes committed output until corrected.
CONFIRMED-BAR BEHAVIOR
State, duration, release plots, diagnostics and alert pulses commit only on
confirmed bars. On an open realtime bar, the panel says `OPEN BAR — HELD` and
retains the previous confirmed values. Historical, elapsed realtime and Bar
Replay bars use the same transition order.
This does not prevent upstream exchange or broker feed corrections from
changing rebuilt history after reload. The script makes no external data
requests and uses only the current chart symbol and timeframe.
OUTPUTS
The pane contains:
- volatility percentile and declared threshold guides;
- a visually clipped impulse histogram;
- optional confirmed regime backgrounds;
- optional confirmed release markers;
- Compact and Full evidence panels with state, duration, normalized metrics,
release counts, unresolved events and readiness.
Hidden machine-readable plots expose:
- Regime code: -3, -2, 0, 1, 2 or 3;
- Compression score: 100 minus VOL PCTL;
- Confirmed release: +1, -1 or 0.
The Confirmed release plot can be selected directly as Signal Audit Lab's
Event source with the Signed pulse decoder. In the validation run, BSL-002's
18 up and 19 down releases matched BSL-001's 18 long and 19 short accepted
events exactly.
ALERTS
Four alert conditions are provided:
- Confirmed volatility release up;
- Confirmed volatility release down;
- Confirmed directional expansion up;
- Confirmed directional expansion down.
Release alerts use the same one-bar booleans as the exported pulse. Expansion
alerts fire only on entry into expansion.
LIMITATIONS
- This is a regime classifier, not a forecast, entry/exit system or strategy.
- A release direction is a normalized momentum label, not evidence of future
return.
- Percentile and state depend on the loaded symbol, timeframe, feed, history
and settings.
- Warm-up requires a complete percentile window and valid momentum history.
- The maximum 500-value percentile window is bounded but intentionally more
expensive than the default 126-value window.
- No optimization, multi-symbol scan, multi-timeframe request, order model,
position sizing or profitability claim is included.
VALIDATION
The release candidate passed 14 deterministic reference tests, a 14/14 live
Pine harness, BTCUSDT/AAPL × 1D/1H runtime checks, exact reload parity,
realtime and replay gates, valid/invalid threshold boundaries, four alert
conditions, 390 px rendering, BSL-001 signed-source integration and a 32,137
execution Profiler run at the maximum 500-bar window.
ORIGINALITY AND SOURCE
Category demand was selected from a dated metadata corpus. No protected,
invite-only or closed source was accessed, and no source from a compared open
publication was imported. The script uses standard true-range, Wilder RMA,
percentile-count and EMA calculations and is released under MPL 2.0.
CHANGELOG
v1.0.0
- Initial open-source release candidate.
- Explicit compression, release and expansion state machine with hysteresis.
- Inclusive rolling volatility percentile and normalized directional impulse.
- Confirmed +1 / -1 release export for Signal Audit Lab.
- Compact/Full evidence panels, four alerts and visible limitations.
Indicator

Volatility Regime Trend Ribbon [Pineify]Volatility Regime Trend Ribbon
Overview
This overlay adapts smoothing as markets change. It ranks ATR, selects a regime, and adjusts trend speed and ribbon width.
Key Features
Three ATR percentile regimes.
Regime-specific trend lengths and band scales.
Optional colors, confirmed markers, and alerts.
How It Works
ATR is ranked over a rolling window. Low ranks select low volatility, high ranks select high volatility, and middle ranks select normal volatility. Warm-up uses the normal state.
The selected length drives a recursive EMA-style center. Ribbon edges equal the center plus or minus ATR times the base multiplier and regime scale. This is a price boundary, not a statistical confidence interval. Direction turns bullish after a confirmed close above the upper edge, bearish below the lower edge, and otherwise retains its prior state.
Trading Ideas and Insights
Colors separate quiet, ordinary, and elevated ranges. A band exit can frame a direction change; movement inside stays unresolved. Gaps or thin trading can add lag and false transitions. No output is an automatic trade.
How Multiple Indicators Work Together
ATR measures range, percentile rank adds context, adaptive smoothing changes speed, and the band supplies the direction threshold. They form one engine without external data.
Unique Aspects
The original design links volatility to smoothing speed and band scale, not just color. Retained direction inside the band adds hysteresis; alerts distinguish regime and direction changes.
How to Use
Apply it to a liquid market and let the percentile window warm up.
Tune lengths and band scales for the symbol and timeframe.
Read center color as direction and ribbon color as regime.
Use confirmed alerts with independent risk controls.
Customization
ATR Length controls range sensitivity; Percentile Lookback controls context. Thresholds define states, lengths set speed, and band inputs set transition distance. Display layers are optional. Current values can change intrabar; markers and alerts require a confirmed close.
Conclusion
This ribbon organizes volatility regime and ATR percentile context for 15-minute to daily charts. It uses past and present data, remains lagging and parameter-sensitive, and makes no performance claim.
Indicator

Advanced Realized Volatility (Crypto Stocks Indices Forex)**Advanced Realized Volatility — Detailed Guide**
### What This Indicator Does
Advanced Realized Volatility (Crypto) measures the actual historical price fluctuation of an asset over a user-defined calendar-day window and expresses it as an annualized percentage. Unlike simple standard-deviation tools, it offers six statistically grounded estimators (Close-to-Close, Parkinson, Garman-Klass, Yang-Zhang, Rogers-Satchell, and EWMA), automatically converts a calendar-day lookback into the correct number of bars for any timeframe, and applies the proper annualization factor (√365 for crypto by default, √252 for traditional assets).
The indicator places the current volatility reading in historical context through percentile rank, classifies the market into four regimes (Low / Normal / High / Extreme), calculates Expected Moves for 1-, 7-, and 30-day horizons, and allows direct visual comparison with up to three other symbols. All key metrics appear in a compact on-chart table.
### Core Concepts Explained Simply
- **Realized Volatility (RV)** shows how much the asset has actually moved in the recent past, scaled to a one-year basis. Higher RV means larger typical price swings.
- **Percentile Rank** answers the question: “Is the current volatility high or low relative to its own history?” A reading of 15 means the present volatility is lower than 85 % of the readings in the chosen historical window.
- **Volatility regimes** translate the percentile into actionable categories:
- Low (compression) — percentile below 20
- Normal — 20 to 80
- High — above 80
- Extreme — above 95
- **Expected Move** converts the current annualized RV into an approximate price range the market is statistically likely to traverse over the next 1, 7, or 30 days.
- **Relative Volatility** and multi-asset lines show whether the current instrument is quieter or more turbulent than its peers or its own longer-term average.
### How to Set Up and Read the Indicator
1. Apply the script to any chart (crypto, stocks, indices, and forex work correctly).
2. Choose the volatility method. Yang-Zhang is the recommended default because it efficiently incorporates overnight gaps, open-to-close drift, and the high-low range.
3. Select a lookback in calendar days (30 days is a balanced starting point; shorter windows react faster, longer windows are smoother).
4. Leave annualization on Auto unless you have a specific reason to force 365 or 252.
5. Optionally enable one to three comparison symbols (e.g., BTC vs ETH, SOL, or QQQ) using the same method and period.
6. Turn on background regime coloring and the information table for at-a-glance context.
7. Observe three primary visual elements:
- The main RV line and any comparison lines
- Horizontal reference levels (mean, 20th and 80th percentiles)
- Background color that changes with the regime
The table always displays the current annualized RV, percentile rank with regime label, relative volatility, Expected Moves, and the values of any enabled comparison assets.
### Practical Trading Applications and Patterns
**1. Volatility Compression → Expansion (Breakout Preparation)**
When the percentile rank falls below 20 and the background turns to the Low-volatility color, the market is in a compressed state. Historically, prolonged low-volatility periods are frequently followed by a sharp expansion in range. Traders watch for price to break a well-defined consolidation, range, or chart pattern while RV is still low or just beginning to rise. The Expected Move values help set realistic profit targets once the expansion starts.
**2. High / Extreme Volatility Regime (Risk Management & Mean-Reversion Bias)**
A percentile above 80 (especially above 95) signals elevated or extreme turbulence. In these conditions:
- Position sizes are typically reduced.
- Stops are widened or switched to volatility-based (ATR or Expected Move multiples).
- Mean-reversion or fade strategies become more attractive after a climax move, because extreme readings often revert toward the mean.
- Trend-following systems may stay in the market but with tighter risk controls.
**3. Regime Shifts as Timing Filters**
A cross of the RV line above its longer-term mean or a move of the percentile from Low into Normal/High can confirm that a new directional move has volatility support. Conversely, a drop back into the Low regime after an expansion often marks the end of a volatile phase and the start of a quieter consolidation.
**4. Cross-Asset Relative Volatility**
When the main asset’s RV line sits significantly above or below the comparison lines, relative volatility strength or weakness appears. Example patterns:
- BTC RV rising while ETH RV stays flat or declines → possible BTC leadership or capital rotation into Bitcoin.
- An altcoin showing persistently higher RV than BTC → higher-risk, higher-reward environment that may require stricter position sizing.
- Equity index (QQQ or SPX) RV rising together with crypto → broader risk-off or risk-on regime alignment.
**5. Expected Move for Targets and Option Structures**
The 1-day, 7-day, and 30-day Expected Move figures provide statistically derived price ranges. Common uses:
- Setting take-profit levels at approximately 1× or 1.5× the Expected Move.
- Judging whether an options premium is rich or cheap relative to recent realized movement.
- Sizing positions so that a 1–2 Expected Move adverse excursion remains within acceptable risk.
**6. Volatility of Volatility (VoV)**
When enabled, VoV highlights periods when volatility itself is unstable. Rising VoV often accompanies regime transitions and can serve as an early warning that the current quiet or elevated state is about to change.
### Typical Workflow for Discretionary Traders
1. Note the current regime and percentile rank.
2. Check whether RV is rising or falling and how it compares with the chosen benchmark assets.
3. Read the Expected Move numbers to gauge the probable size of the next swing.
4. Align the volatility picture with classical price action (breakouts from compression, exhaustion after extreme readings, relative strength between assets).
5. Adjust position size, stop distance, and profit targets accordingly.
6. Use the built-in alerts for regime changes, RV crosses of its mean, or sharp expansions so that monitoring can be partly automated.
### Recommended Starting Settings
- Method: Yang-Zhang
- Lookback: 30 calendar days
- Annualization: Auto
- Percentile lookback: 365 days
- Background coloring and table: enabled
- One or two comparison symbols relevant to the traded asset
These settings provide a balanced, responsive view on most crypto pairs while remaining stable enough for higher-timeframe analysis.
The indicator does not generate buy or sell signals by itself. It supplies a quantitative volatility context that improves timing, risk management, and cross-market comparison. When combined with price structure, volume, and a clear trading plan, the regimes, percentile extremes, and Expected Moves become reliable filters for identifying high-probability compression-to-expansion setups, managing risk during turbulent periods, and comparing the relative “temperature” of different assets.
⚠️ Disclaimer
This indicator is for *educational and informational purposes only*. It does not constitute financial advice. Always do your own research before making investment decisions.
*Indicator by:* iCD_creator
*Version:* 1.0
*Pine Script™ Version:* 6
---
Updates & Support
For questions, suggestions, or bug reports, please comment below or message the author.
*Like this indicator? Leave a 👍 and share your feedback!* Indicator

Volatility Pressure & Regime AnalyzerVolatility Pressure & Regime Analyzer
## What this script does
VPRA estimates **when a market is loading energy for an outsized move, how large that move could be, and whether the current regime favors chasing or fading the breakout**. It condenses this into one on-chart verdict panel, directional signal markers, a regime ribbon, and a forecast of the expected move in ATR and points.
It works on **any symbol, any market, any timeframe**. A related volatility index and a companion symbol (the underlying if you chart a derivative, or vice versa) are optional inputs that sharpen the analysis; both can be disabled and the model renormalizes to price-only mode automatically.
## Why these components are combined (mashup justification)
Each module answers a question the others cannot, and the signal only fires when their answers agree. None of them is a stock indicator pasted alongside another — they are inputs to a single pressure model:
1. **Compression (ATR percentile)** answers *"is energy being stored?"* Quiet ranges precede expansion, but compression alone says nothing about direction or timing.
2. **Implied-vs-realized volatility dislocation** (optional vol index) answers *"is the options market mispricing the calm?"* A large gap between implied and realized volatility marks complacency or stress that compression alone cannot see.
3. **Basis tension** (optional companion symbol) answers *"is positioning leaning?"* Momentum in the derivative-to-underlying spread, and outright backwardation, reveal funding pressure and de-risking invisible in a single price series.
4. **Convexity and trend inefficiency** (return acceleration, efficiency ratio) answer *"is price behavior becoming unstable?"*
These four are blended into one **Pressure score (0–100)**, percent-ranked against its own history so thresholds adapt to every symbol and timeframe.
5. **A variance-ratio regime filter** answers *"will the break run or get faded?"* The ratio of k-bar to 1-bar return variance classifies the tape as mean-reverting (pinning) or trending (amplifying). Breakouts in a pinning regime are statistically more likely to fail, so the script can label or skip them.
6. **A multi-timeframe trend filter (Ichimoku cloud bias on the chart TF + three higher TFs)** answers *"is the release direction supported by structure?"* It grades signals rather than generating them. Higher-timeframe values are taken from **closed bars by default, so the confluence grade does not repaint**.
7. **Session, expiry, gap and event context** scale the expected-move forecast: an expiry-afternoon release during a volatility spike forecasts a larger move than a sleepy mid-session one.
Removing any module degrades a specific, named capability — that is the test the combination was built to pass.
## How a signal is generated
A marker prints only when **all** of the following align: pressure has reached a high percentile of its own history within a short lookback ("loaded"), the current bar shows a genuine range expansion ("release"), the condition persists for a confirmation bar count, a debounce gap has passed, and (optionally) the regime and trend filters pass. Direction is scored from **trigger-break** (close beyond the prior N-bar extreme), **close location** within the bar, and short momentum.
Marker color encodes the inferred event type: expiry-session releases, volatility-co-movement squeezes (price and vol index moving together — a short-covering tell), or plain expansions. The glow ring encodes how many higher timeframes agree. An ⓘ label stores a full diagnostic snapshot (pressure, regime, instability, basis, energy, session, expected move) in its tooltip for every signal.
## How to use it
- Apply to a liquid symbol; set "This chart is" to Derivative or Underlying, point the companion and volatility-index inputs at your market's related symbols (or disable them), and set your session hours and expiry weekday.
- Read the panel top-down: **Regime** (chase vs fade), **Pressure/Energy** (how loaded), **Move size** (forecast), **Trend align / HTF** (structure), **Triggers** (the price levels that confirm).
- Use the "Filter" modes to suppress signals against regime or higher-timeframe structure, or leave them as badges and judge manually.
- The advanced rows show per-type follow-through statistics (hit rate, average favorable and adverse excursion in ATR) and an early-vs-late history split as a coarse robustness check. **These are in-sample descriptive statistics, not a backtest.** A companion strategy script with identical logic is available for proper backtesting with costs.
- Alerts: per-signal dynamic alert with all values (webhook-ready), plus static conditions for expiry signals, releases, critical pressure, and vol shocks.
## Originality
The pressure blend (compression x vol-dislocation x basis tension x convexity x inefficiency, percent-rank normalized), the variance-ratio regime gate applied to breakout qualification, the compression-energy budget, and the per-type MFE/MAE statistics with an early/late split are original constructions written from first principles for this script. The only classical components used are public-domain building blocks (ATR, Bollinger/Keltner-style compression logic via ATR percentile, Ichimoku cloud bias as a trend filter, Kaufman efficiency ratio), each justified above.
## Limitations (please read)
- Dealer-positioning effects (often discussed as gamma/vanna/charm) are **inferred from price, volatility and basis behavior**. This script does not and cannot read option-chain open interest. Labels such as "gamma blast" describe an expiry-session release pattern, not a measured dealer position.
- All on-panel statistics are computed on the loaded chart history and will differ across symbols, timeframes and history length.
- Higher-timeframe confluence uses closed HTF bars by default (no repaint); the current chart bar still forms in real time, as with any script.
- Expected-move figures are model estimates, not guarantees.
This script is for education and analysis. It is **not financial advice**; trade at your own risk and test before use.
Indicator

Volatility Regime Dashboard## Overview
Volatility Regime Dashboard is a context and visualization tool that classifies the
current volatility state of any symbol as **Compressed**, **Normal**, or **Expanded**.
Instead of plotting a single raw volatility line, it combines two independent
normalized measures and only changes the displayed state when both of them agree.
A compact table reports the underlying numbers and how many bars the current regime
has lasted.
This script is a visualization and context tool. It does not generate buy or sell
signals. It does not provide financial advice and makes no performance, accuracy,
or future-result claims.
## What it visualizes
- A line in its own pane showing the **percentile rank of price-normalized ATR**
(0-100), with dashed guides at the compressed and expanded thresholds and a
dotted midline.
- A **regime background shade** (optional) coloring the pane by the current state.
- A **context table** with the regime name, the ATR percentile value, the
Fast/Slow ATR compression ratio, whether the two measures currently agree, the
regime persistence in bars, and the ATR length in use.
## How it works
Two measures are computed independently:
1. **Price-normalized ATR percentile.** ATR is divided by price (so the measure is
comparable across symbols and price levels), then ranked as a percentile over a
user-defined lookback (default 252 bars). A high percentile means current ATR is
large relative to its own recent history; a low percentile means it is small.
2. **Fast/Slow ATR compression ratio.** A fast-window ATR is divided by a
slow-window ATR. A ratio above 1 means range is expanding relative to its
baseline; below 1 means it is compressing.
Each measure is classified into Compressed (-1), Normal (0), or Expanded (+1) using
its own thresholds. The displayed regime uses **hysteresis**: it flips to Expanded
or Compressed only when **both** measures agree on that direction, returns to Normal
only when both measures sit in their middle bands, and otherwise **holds** the prior
regime while the two measures disagree. This reduces flicker compared with reacting
to either measure alone. A persistence counter tracks how many consecutive bars the
current regime has held.
## How to use it
- Read the regime as **situational context** about how active the market currently
is relative to its own recent behavior, not as an instruction to act.
- Watch the percentile line approach the dashed thresholds to anticipate when a
regime change may be confirmed by both measures.
- Use the persistence counter to gauge whether a regime is freshly established or
well established.
- Adjust the lookback and thresholds to match the symbol and timeframe you study;
the defaults suit daily charts and are a starting point, not an optimized set.
## What makes it original
Most volatility tools plot a single raw or smoothed value. This dashboard derives a
**single discrete regime from the agreement of two structurally different measures**
- a within-history percentile rank and a fast-versus-slow ratio - and gates state
changes with hysteresis so the regime persists through brief disagreement. It then
surfaces the **persistence duration** of the current regime. The combination of
cross-measure agreement, hysteresis, and persistence reporting is the contribution;
it is not a re-skin of a built-in ATR, Bollinger, or standard-deviation indicator.
## What it does not do
- Does not generate buy/sell signals.
- Does not give entry/exit, target-level, or position-sizing instructions.
- Does not predict price or forecast performance.
- Does not run a strategy or backtest.
- Does not place or manage orders for you.
## Limitations
- Volatility regime is **descriptive context**, not a forecast; an Expanded or
Compressed state can persist or reverse at any time.
- The percentile rank depends on the lookback window; very small lookbacks make the
state noisy and very large ones make it slow to update.
- On symbols or timeframes with sparse history, the percentile may be unstable until
enough bars are available.
- ATR divided by price assumes price is positive and non-zero; exotic data feeds may
behave unexpectedly.
- Default thresholds are reasonable starting values, not values tuned for any
particular market.
## Suggested chart setup
- Use a liquid, recognizable symbol on a daily timeframe so the percentile lookback
has enough history.
- Keep the chart clean: this indicator opens in its own pane, so remove unrelated
indicators and let the percentile line, threshold guides, regime background, and
table be clearly visible.
- Make sure the indicator name, symbol, and timeframe are visible in any published
screenshot.
---
## Japanese notes / 日本語補足
このスクリプトはボラティリティの状態を「Compressed(収縮)」「Normal(通常)」
「Expanded(拡大)」として表示する、コンテキスト把握用の可視化ツールです。価格で
正規化したATRのパーセンタイル順位と、ファスト/スロー期間のATR比率という2つの独立
した指標を用い、両者が一致したときだけ状態を変更するヒステリシス方式を採用していま
す。表には各指標の数値と、現在の状態が何本のバー継続しているかを表示します。
これは相場の状況を把握するための可視化ツールであり、売買の指示は行いません。投資
助言ではなく、将来の値動きや運用成績に関する主張も一切行いません。新規の建玉や手
仕舞い、ポジションサイズの提案も行いません。しきい値やルックバックは銘柄や時間足に
合わせて調整してください(初期値は最適化されたものではありません)。
Indicator

Concordance Allocation Strategy [JOAT]Concordance Allocation Strategy
Introduction
Concordance Allocation Strategy is an open-source TradingView strategy that integrates regime detection, directional bias, momentum alignment, value-location filtering, and ATR-based risk management into one non-repainting framework. It is designed to trade only when multiple independent layers agree on bar close.
The problem this strategy solves is isolated signal bias. A single good-looking signal can fail quickly if it appears in the wrong market regime, against the wrong directional structure, or in the wrong part of value. Concordance requires those layers to align before it enters a trade, then manages risk with fixed ATR targets and adaptive exits.
Core Concepts
1. Regime filter
The strategy uses a probability-based trend-versus-range classifier. Trades are only considered when the directional regime is confirmed on a closed bar.
2. Directional bias engine
An ATR-based bias band adapts to noisy conditions and recovery stress so long and short bias are not driven by a simple moving average cross.
3. Momentum confirmation
A centered adaptive stochastic spread must align with the directional side. This prevents entries based on trend context alone.
4. Value-location filter
The strategy requires price to be properly aligned with percentile-derived value rails before entries are allowed. This helps avoid chasing direction in poor location.
5. Structured risk management
Every position uses:
ATR stop loss
ATR take profit
Adaptive trailing behavior once price extends far enough
Context exits when regime or momentum deteriorates
Features
Multi-layer entry filter: Regime, bias, momentum, and value must agree
Bar-close confirmation: Entries are evaluated using confirmed-bar logic
ATR stop loss and take profit: Risk is defined from volatility, not fixed ticks
Adaptive exit behavior: Bias band can tighten once the move extends
No higher-timeframe dependency: Uses current-timeframe calculations only
Institutional dashboard: Shows exposure state, regime, momentum, bias band, and value rails
Non-repainting framework: No future references and no lookahead logic
Input Parameters
Regime Layer:
Return Lookback
Volatility Lookback
Efficiency Length
Regime Learning
Trend Gate
Directional Bias:
ATR Length
ATR Base Multiplier
Avoidance Expansion
Recovery Pull
Noise Threshold ATR
Momentum Layer:
Stochastic Length
Stochastic Smoothing
Price Presmoothing
Adaptive Attenuation
Momentum Spread Gate
Value Layer:
Value Lookback
Lower Rail Percentile
Upper Rail Percentile
Rail Smoothing
Risk Layer:
Stop ATR
Take Profit ATR
Trail Activation ATR
Trail Buffer ATR
How to Use This Strategy
Step 1: Read the regime
The strategy only acts when the directional regime is confirmed. If the regime is rotational, it stands down.
Step 2: Confirm directional bias
The ATR bias band must agree with the side of the trade. This avoids taking long momentum setups under bearish structure or the reverse.
Step 3: Check momentum and value together
Momentum must align with the side and price must be operating in the correct value location. Both filters are required.
Step 4: Review risk settings before use
Stop and target multiples should be adjusted to the market and timeframe being tested. The defaults are intended to be realistic rather than aggressively optimized.
Strategy Limitations
No strategy can eliminate false regime transitions or rapid reversals
Percentile value rails adapt to the sample window and may lag sudden structural changes
The strategy is designed for realism and context alignment, not maximum trade frequency
Originality Statement
Concordance Allocation Strategy is original in how it requires regime confirmation, directional bias, momentum agreement, and value-location agreement before allowing entries. It is published because:
The strategy avoids isolated indicator triggers and instead uses a layered confirmation model
Its risk logic combines fixed ATR objectives with adaptive context exits
The design is intentionally current-timeframe, bar-close confirmed, and non-repainting
Disclaimer
This strategy is provided for educational and informational purposes only. It is not financial advice, and backtest results do not guarantee future performance. Trading involves risk of loss, and any strategy can underperform or fail in changing market conditions. Always evaluate settings carefully and use proper risk management.
Strategy

Helix Trend Ensemble [JOAT]Helix Trend Ensemble
Introduction
Helix Trend Ensemble is an open-source trend overlay built around a three-member weighted ensemble. Instead of relying on one moving average or one crossover, Helix evaluates multiple configurable members, normalizes slope behavior, and produces a consensus trend state only when enough internal agreement is present.
The problem Helix solves is false certainty. Single-line trend tools are easy to read but easy to break. Multi-line tools often create clutter without resolving disagreement. Helix is designed to preserve a clean chart while still exposing the quality of alignment between fast, intermediate, and structural trend engines.
Core Concepts
1. Multi-Member Trend Architecture
Three independent members can each use different MA types, smoothing methods, lengths, and weights. This allows the ensemble to mix responsiveness with structural stability.
2. Weighted Consensus
The final state is not a simple majority vote. Each member contributes according to its configured weight, and the ensemble requires sufficient agreement before it promotes a directional state.
3. Slope Normalization
Raw slope values are normalized so the dashboard can express trend energy in a stable way across different length combinations.
4. Filter Layer
ATR and ADX filters help suppress weak trend states and reduce low-quality directional transitions.
5. Confirmed Regime Transitions
Directional state changes are only recognized on confirmed bars, which keeps the ensemble consistent with real-time use.
Features
Three fully configurable members: Each member supports multiple MA and smoothing combinations
Weighted consensus engine: Final state depends on internal agreement quality, not one crossover
Normalized slope score: Slope behavior is translated into a stable strength readout
Ribbon and cloud system: Trend geometry is expressed through layered fills instead of cluttered markers
Optional candle coloring: Price bars can reflect the ensemble state without altering logic
Top-right dashboard: Regime, consensus, strength, slope, agreement, filters, and last flip are summarized continuously
How to Use This Indicator
Step 1: Read regime and consensus together
A bullish or bearish state is more meaningful when consensus is high and filters are passing.
Step 2: Watch slope and strength
An aligned ensemble with weakening slope often signals late-trend conditions rather than fresh expansion.
Step 3: Use Helix as a bias filter
Helix works well as a directional framework for execution models that need a clean trend gate.
Indicator Limitations
Longer member lengths will intentionally delay reversals
High responsiveness settings can increase whipsaws
Consensus does not eliminate all false trends; it only improves structural filtering
The script is a trend-classification tool, not a full strategy
Originality Statement
Helix Trend Ensemble is original in the way it combines configurable member diversity, weighted consensus, slope normalization, and clean institutional visualization into one open-source trend framework.
Disclaimer
This indicator is provided for educational and informational purposes only. It is not financial advice. Trend-state tools can fail during rapid reversals, compressed markets, or structurally irregular conditions. Use proper risk control at all times.
Indicator

Volatility Regime Cycle [AGPro Series]Volatility Regime Cycle
🌀 Overview
Volatility Regime Cycle classifies every bar on your chart into one of four distinct volatility phases: Contraction, Expansion, Climax, and Reset. Unlike traditional trend or regime indicators that focus on price direction, this tool maps the cyclical behavior of volatility itself — helping traders recognize whether the market is coiling, releasing, climaxing, or resetting. Each phase is detected through a multi-factor confluence engine and displayed with gradient background shading, transition markers, and S/R-style climax reaction zones. The framework is asset- and timeframe-agnostic: it adapts to crypto, forex, indices, stocks, and commodities on any timeframe.
💎 Unique Edge
Most volatility tools present a single metric (ATR, Bollinger Width, VIX proxy). Volatility Regime Cycle differs in structure and intent:
🔸 Phase-based classification, not just a reading — every bar is assigned to a named regime with a trader-actionable bias.
🔸 Multi-factor confluence scoring — five independent volatility inputs (ATR level, BB Width level, BB/KC squeeze, volume z-score, ATR rate-of-change) vote on the active phase. No single factor can dominate.
🔸 Winsorized normalization — outlier events (single extreme bars) do not compress the scale and hide current readings, a common flaw in simple percentile-based tools.
🔸 Climax Reaction Zones — each Climax event is preserved as an S/R-style rectangle with mid-pivot line, creating a memory of past volatility exhaustion levels that often act as future reaction areas.
🔸 Cycle-aware analytics — tracks historical phase durations and estimates current cycle progress based on rolling averages of past phases of the same type.
🔸 Phase-specific Trader Bias — panel translates the current regime into a plain-language bias (Breakout-watch, Momentum-favor, Reversal-risk, Cooldown).
This is not a Wyckoff phase tool, an Elliott counter, or a Dow-theory classifier. It is a pure volatility-cycle mapper, engineered from the ground up to stand apart from both classical cycle indicators and single-metric volatility meters.
🧠 Methodology
The engine runs three layers:
🔹 Factor Layer
• ATR Level — 14-period ATR, winsorized min-max normalized (5%-95% range) over a configurable lookback window.
• BB Width Level — Bollinger Band width as percent of basis, normalized identically.
• Squeeze State — true when Bollinger Bands are contained inside Keltner Channels (classic volatility compression).
• Volume Z-Score — standardized volume relative to its rolling mean and standard deviation.
• ATR Rate-of-Change — momentum of volatility itself.
🔹 Scoring Layer
Each of the four phases has its own scoring formula that weights the five factors differently. For each bar, all four phase scores are calculated in parallel, and the phase with the highest score is the candidate regime for that bar.
🔹 Confirmation Layer
To suppress whipsaw, the candidate phase must persist for a configurable number of bars (default 3) before replacing the active phase. A minimum phase duration lock additionally prevents rapid flips. Climax events include a de-duplication cooldown so that clustered climax bars produce a single marker rather than a cluster of overlapping labels.
Phase transitions are classified as major (Contraction→Expansion breakouts and Climax entries) or minor (all other routine changes). Only major transitions receive labels; minor changes are shown as subtle dotted lines to keep the chart clean.
🔔 Signals & Alerts
The script exposes alerts for every phase transition as well as two high-value composite events:
🔸 Any Phase Transition — fires whenever the active phase changes.
🔸 Entered Contraction / Expansion / Climax / Reset — fires for specific phase entries.
🔸 Contraction → Expansion (Breakout) — coil release event; of interest to breakout traders.
🔸 Climax Entry (Exhaustion Warning) — volatility peak event; of interest to mean-reversion and risk-management traders.
All alerts fire only on confirmed bar close to prevent intra-bar flip-flop.
⚙️ Key Inputs
🔹 Engine Settings — normalization lookback, ATR length, Bollinger/Keltner length and multipliers, volume z-score length, ATR rate-of-change length, confirmation bars, minimum phase duration.
🔹 Phase Thresholds — low volatility level, high volatility level, climax volatility gate, climax volume z-score threshold, climax de-dup cooldown.
🔹 Visuals — toggles for background shading, major transition labels, minor transition lines, volatility ribbon, current phase label.
🔹 S/R Zones — climax zones toggle, breakout zones toggle, maximum active zones, zone initial length, zone range lookback.
🔹 Panel — show/hide, location, Dark/Light theme, font size.
🔹 Label Sizing — font size for on-chart labels.
🔹 Alerts — per-event toggles.
📘 How to Use
🔸 Breakout traders: watch for Contraction phase on the panel with Trader Bias showing Breakout-watch. When the phase transitions to Expansion, a coil release is underway and a Breakout label is printed. Optional Breakout Zones can be enabled to preserve the breakout level as a retest reference.
🔸 Momentum / trend traders: ride the Expansion phase while Trader Bias reads Momentum-favor. Phase Duration and Cycle Progress on the panel give a sense of where the current momentum leg sits relative to historical averages.
🔸 Mean-reversion / exhaustion traders: a Climax label with Trader Bias Reversal-risk highlights volatility exhaustion. The Climax Reaction Zone drawn at each climax often behaves as a future reaction level and can be used as confluence with other reversal tools.
🔸 Risk managers: the Reset phase with Trader Bias Cooldown typically signals reduced market conviction and can be used to scale down position size until a new Contraction builds up.
🔸 Multi-timeframe reading: run the script on the higher timeframe for regime context and on the lower timeframe for entry timing.
Hover the panel header to see a statistics tooltip with average durations of each phase over the last completed cycles.
⚠️ Limitations & Transparency
🔹 The script does not predict future prices or issue buy/sell recommendations. It is a classification and context tool.
🔹 Phase detection is inherently lagging because it requires the confirmation window and minimum duration lock. This is a deliberate design choice to suppress whipsaw at the cost of some responsiveness.
🔹 Normalization uses a rolling lookback window; the first lookback bars after loading the script may show compressed or unstable readings while the window fills.
🔹 Cycle Progress is an estimate based on historical phase averages and may exceed 100% when the current phase runs longer than past cycles.
🔹 Climax and Reset scores rely partly on volume; on instruments with unreliable or missing volume feeds, volume-dependent factors will contribute less.
🔹 All visual elements are cosmetic and toggleable; they do not alter the underlying phase logic.
🛡️ Risk Disclosure
This indicator is a technical analysis tool. It is not a trading system, not a signal service, not financial advice, and not a guarantee of future results. Trading involves substantial risk of loss. Past market behavior does not predict future market behavior. Users are solely responsible for their own trading decisions, risk management, and position sizing. Always test any tool on your preferred instruments and timeframes with appropriate historical review before using it as part of a live decision-making process. Indicator

Regime Transition Intelligence [AGPro Series]Regime Transition Intelligence
Most regime scripts answer a single question: "what regime are we in right now?". Regime Transition Intelligence is designed to answer a different, more actionable set of questions: how long does this regime usually last, how close to its typical end is it, how likely is it to flip within the next N bars, and where does it historically go when it does flip. Instead of treating the current regime as a standalone snapshot, it builds a living, self-calibrating statistical profile of the symbol's own regime behavior and presents it in a compact on-chart dashboard.
The engine runs on three independent axes — Trend Strength (Kaufman Efficiency Ratio + ADX), Chop Risk (Choppiness Index + inverse trend), and Volatility (ATR% normalized over a user-defined lookback). Each axis is classified as LOW / MID / HIGH, either with fixed 33/67 thresholds or with an adaptive percentile rank engine that learns the symbol's own statistical envelope over a rolling window. The three axes are then combined into a discrete regime state: TREND, MIXED, or RANGE / CHOP.
🟦 Overview / What it does
Regime Transition Intelligence is a single-pane overlay indicator that continuously classifies the market into one of three regimes and then layers a full transition intelligence stack on top of that classification:
- A per-regime dwell-time distribution learned from the chart's own completed regime blocks
- A Bayesian-style flip probability that answers "how likely is a regime change within the next N bars, given the current age"
- A 3x3 transition matrix that ranks the most likely next regime with a secondary fallback
- A fatigue score comparing the current regime's age to its historical mean (FRESH / MATURE / EXTENDED)
- A confidence decay tracker that shows whether conviction is BUILDING, STABLE, or FADING within the current regime block
- A compact history ribbon showing the last completed regime blocks with their durations
- Higher-timeframe alignment with a SYNC / DIV indicator and a live beacon at the right edge of the chart
All of this is delivered inside a single configurable dashboard, a directional transition marker layer on the chart, optional regime tint and candle coloring, and a right-edge beacon summarizing the current state.
🟣 Unique Edge / Why it is not a basic mashup
Standard regime indicators report the current state and stop there. Regime Transition Intelligence adds six distinct statistical layers that together form a transition-aware view:
1. Dwell Time Statistics — the script stores every completed regime block in a rolling array (configurable depth) and continuously updates running mean, running variance, running max, and running count per regime code. Statistics are only shown after a minimum number of blocks per regime have been collected, so the user always knows when the sample size is still too small.
2. Exponential Hazard Flip Probability — the baseline flip probability uses P(flip within H bars) = 1 - exp(-H / mean), a standard survival-analysis construction assuming constant hazard. The result is then fatigue-adjusted: if the current age is far above the historical mean, the probability is boosted; if the regime has just started, the probability is damped. The final value is capped at 95% to avoid certainty claims.
3. Transition Matrix — a 3x3 counter records every observed regime transition and is read as a conditional distribution: "given the current regime ends, which regime is it most likely to move to, and what is the runner-up". Both the top candidate and the secondary candidate are displayed with their percentages.
4. Fatigue Score — the ratio of the current age to the historical mean is bucketed into three zones (FRESH, MATURE, EXTENDED) using user-configurable thresholds. It tells the user whether the current regime is still in its early lifecycle or already past its typical end.
5. Confidence Decay Tracker — conviction in the current regime is sampled at the start of each new block and compared to the current conviction. The delta is classified as BUILDING, STABLE, or FADING, which gives an early read on whether the regime is strengthening or losing its grip.
6. History Ribbon — the last N completed regime blocks are compressed into a single compact line such as "C2·M4·C8·M1·M7*", where letters are regime codes and numbers are bar counts, with the current block marked by an asterisk. It gives immediate context on recent regime rhythm at a single glance.
None of these layers is a repackaged classic indicator. They are built on top of a trend / chop / volatility engine but deliver information that is categorically different from a simple "regime yes / no" readout.
🟢 Methodology / Conceptual data flow
1. Feature extraction. Kaufman Efficiency Ratio (net move over lookback divided by summed absolute moves) and normalized ADX are combined into a trend score. The Choppiness Index is normalized against its operating range and blended with inverse trend to produce a chop score. ATR as a percentage of price is normalized against its own lookback min/max to produce a volatility score.
2. Classification. Each score is mapped to LOW / MID / HIGH using either fixed thresholds (Static mode) or percentile rank over an adaptive lookback (Adaptive mode). The three bands are combined into a discrete regime state: TREND when trend is HIGH and chop is LOW, RANGE / CHOP when chop is HIGH, and MIXED otherwise.
3. Block tracking. Every time the regime state changes on a confirmed bar, the previous block is closed: its duration is pushed to a rolling history array and added to the running sum / sum-of-squares / count / max for its regime code. When the history array exceeds its configured depth, the oldest block is popped and its contribution is subtracted from the running totals, which keeps the statistics adaptive and non-expanding.
4. Transition matrix update. When a block closes into a new regime, the 3x3 counter is incremented at the corresponding cell, and the row total is incremented. The conditional distribution for the current regime is read from its row at display time.
5. Statistical outputs. Mean dwell, fatigue ratio, exponential-hazard flip probability, fatigue-adjusted flip probability, top and secondary next regimes, and confidence delta are all derived from the running state and rendered into the dashboard.
6. Higher-timeframe alignment. The same three-axis engine is run on a user-selected higher timeframe via request.security and compared against the current-timeframe regime; the result appears as SYNC or DIV in the header and as an optional HTF row in the dashboard.
🔔 Signals & Alerts / Interpretation
Regime Transition Intelligence is a state-mapping and statistical context tool rather than a directional buy / sell engine. The main on-chart events are:
- Regime Shift — fires when the regime state changes on a confirmed bar
- High Flip Probability — fires when the fatigue-adjusted flip probability crosses a high threshold
- Regime Fatigue Extended — fires on the transition into the EXTENDED fatigue zone
- Confidence Fading — fires on the transition into the FADING confidence zone
How to read the panel:
- Summary + Age tells the user which regime is active and how long it has been active.
- Dwell Context compares the current age to the historical mean in the form "age / mean · % of typical lifespan".
- Fatigue summarizes that comparison as FRESH, MATURE, or EXTENDED.
- Flip Probability reports the statistical odds of a regime change within the user-defined horizon.
- Next Likely names the most probable next regime with its percentage and a secondary fallback.
- Confidence and Conf Decay together tell the user whether the current read is reliable and whether conviction is rising or fading.
- History gives quick situational awareness of recent regime rhythm.
None of these rows should be interpreted as a trade instruction. They are a context layer meant to be combined with the user's own structure and entry framework.
🎛️ Key Inputs
Regime Engine Core — Trend Persistence Length, DMI/ADX Length, Chop Length, ATR Length, Volatility Normalize Lookback.
Adaptive Boundaries — Band Classification Mode (Adaptive / Static), Adaptive Lookback, Adaptive Low / High Percentile.
Transition Intelligence — Regime History Depth, Flip Probability Horizon, Min Blocks Before Stats Activate, Fatigue Fresh / Extended thresholds.
HUD — Display Mode (PRO / MINIMAL), HUD Position, Text Size, transparency controls, individual row toggles, history ribbon length.
Add-ons — Chart Regime Tint, Regime Candle Coloring (Soft / Strong), HTF Peek Timeframe, Transition Markers (location, cooldown, stagger, size, ATR offset), Live Regime Beacon (position, size, stats toggle).
🧭 How to use
1. Add the script to any chart and timeframe. The engine is tuned to work from 15m up to Daily; very low timeframes on illiquid instruments can produce unstable regime blocks and are not the intended use case.
2. Give the script time to collect blocks. Statistics stay in N/A until the configured minimum number of completed blocks per regime has accumulated. On a fresh chart or an illiquid instrument this is expected behavior, not a bug.
3. Read the dashboard top-down. Start with the three axis rows to understand the current market shape, then move to Summary and Age to see what is active and for how long, then use Dwell / Fatigue / Flip / Next Likely to place the current regime inside its historical distribution, and finally use Conf Decay and HTF to sanity-check reliability and alignment.
4. Treat EXTENDED fatigue and high flip probability as context, not as a reversal signal. Regimes can remain in the EXTENDED zone for a while before actually flipping; the statistical profile is descriptive, not deterministic.
5. Combine with structural context. The script does not know about support / resistance, order blocks, or news. It only knows about the symbol's own regime rhythm. Use it as a regime-aware filter on top of the user's existing framework.
⚠️ Limitations & Transparency
This is not a strategy and not a complete trading system. It does not predict price direction and does not generate buy or sell signals. All statistics are estimated from a rolling history of the chart's own regime blocks, so they are sensitive to the chosen engine parameters, the timeframe, and the symbol; different timeframes and different instruments will produce different statistical profiles, and that is by design.
The exponential-hazard flip probability assumes a constant hazard within the current regime, which is a simplification. Real-world regime durations are not perfectly memoryless and the fatigue multiplier is a heuristic correction, not a formal model. The probability is capped at 95% on purpose, because even a heavily aged regime cannot be considered a certainty and the script deliberately avoids certainty language.
The transition matrix is read as a conditional frequency over completed blocks; it is informative about the symbol's own past behavior and should not be interpreted as a forward-looking forecast. Very small samples produce unstable conditional probabilities, which is why stats stay in N/A until a minimum number of blocks is collected.
Regime classification itself reacts to confirmed bars and can change as new data arrives, which is expected for any regime filter. Users who prefer fully non-repainting alerts should rely on the barstate.isconfirmed-gated alert conditions provided.
📜 Risk Disclosure
Trading involves substantial risk of loss and is not suitable for every investor. Past performance is not indicative of future results. This indicator is provided for educational and analytical purposes only and should not be interpreted as financial advice, an investment recommendation or a solicitation to trade. Always combine multiple forms of analysis, manage position size responsibly, and never risk capital you cannot afford to lose. Indicator

Volatility Shape Classifier [AGPro Series]Volatility Shape Classifier
🔹 Overview
Volatility Shape Classifier is a context and diagnostics tool that does not stop at telling you whether volatility is high or low. Instead it classifies the SHAPE of that volatility on every bar — Smooth, Chaotic, Choppy, Drift, or Dead — using three independent dimensions combined into a single regime read. The result is a continuous visual narrative made of a subtle background tint, throttled transition badges, and a compact metrics panel.
It is designed to sit on your chart as a pure awareness layer. It does not generate buy or sell signals and it is not a trading strategy.
🔷 Unique Edge
Most volatility tools compress the market into one axis — high vs low (ATR, Bollinger Band Width), or trend vs range (Choppiness Index, ADX). They answer half of the question.
This script asks three questions at once and fuses the answers:
1. Magnitude — is ATR above or below its own long baseline?
2. Smoothness — are bar-to-bar moves consistent in size, or erratic?
3. Directional Consistency — do bars point the same way, or cancel each other?
Only the combination of these three can distinguish a controlled trend run (Smooth) from a violent whipsaw (Chaotic) from a wide directionless thrash (Choppy) — all three of which can show identical ATR readings. That shape distinction is the core value this script adds, and it is the gap left by standard volatility and chop indicators.
🔶 Methodology
Engine layer (per bar):
• Volatility Level = ATR(volLen) / SMA(ATR, volLen * 3)
• Smoothness = StDev(|close − close |) / SMA(|close − close |) over volLen
• Direction = |sum(close − close )| / sum(|close − close |) over volLen
Classification layer maps the three readings into six mutually exclusive codes:
0 — Forming (warm-up / in-between space, no tint)
1 — Expansion · Smooth (high vol, low CV, directional)
2 — Expansion · Chaotic (high vol, high CV)
3 — Expansion · Choppy (high vol, low direction)
4 — Low-Vol · Drift (low vol, low CV, mild direction)
5 — Low-Vol · Dead (low vol, low CV, no direction)
Stability layer applies a configurable Confirmation Bars window so a new shape must persist for N consecutive bars before the chart commits to it. This prevents single-bar flicker. Between-state readings do not reset the current shape, they hold it — avoiding the classic "blink to neutral" problem of switch-based classifiers.
🔸 Signals & Alerts
Four alert conditions are published:
• Shape Shifted to Smooth Expansion
• Shape Shifted to Chaotic Expansion
• Shape Shifted to Choppy Expansion
• Shape Collapsed (any expansion state falling into low-vol Drift or Dead)
Alerts fire only on confirmed shape transitions and only on bar close, so repaint on the signal bar is not a concern.
🔹 Key Inputs
• Volatility Length — window for ATR, smoothness, and direction (default 20)
• Confirmation Bars — persistence requirement before committing to a new shape (default 3)
• Badge Cooldown — minimum bars between visible badges (default 15; tint updates continuously regardless)
• Panel Position / Size — six anchor points, four size presets
• Badge Font Size — four size presets
🔷 How to Use
• Use the SHAPE read as a setup filter, not as the signal itself. Smooth Expansion is where trend-following tools tend to perform well. Chaotic and Choppy Expansion are where they tend to fail even when the raw volatility reading looks attractive.
• The Drift state often precedes an expansion in the direction of the drift.
• The Dead state is a compression warning — a shape collapse alert from Expansion into Dead is a common precursor to a fresh expansion move in either direction.
• Pair with your own entry logic (structure, moving averages, volume). This tool answers "what kind of market am I in right now?" — it does not answer "where do I enter?"
🔶 Limitations & Transparency
• Thresholds (1.15x / 0.70x / 0.80 / 1.10 / 0.18) were tuned on crypto and FX data across 15m to 1D timeframes. Very illiquid instruments and very low timeframes (< 5m) may require a longer Volatility Length.
• Shape classification is inherently backward-looking (it reads the last volLen bars). It describes the character of recent volatility, not future volatility.
• The script is a context layer. It is not a strategy and should not be used in isolation for trade decisions.
• Past behavior of a shape does not guarantee future behavior.
🔸 Risk Disclosure
This indicator is an educational and analytical tool. It does not constitute financial advice, trade recommendations, or a signal service. All trading involves risk. You are solely responsible for your own trading decisions. Indicator

Delivery Regime Map [AGPro Series]Delivery Regime Map
🔹 Overview
Delivery Regime Map classifies the market's delivery character into four distinct regimes — Balanced, Directional, Fragmented, and Exhausted — giving traders instant context on whether the tape is trending with conviction, consolidating, breaking into volatile chop, or fading after an extended move. Rather than asking "is this bullish or bearish?", DRM answers a more useful question: "what kind of market am I in, and what kind of setup is appropriate here?"
The indicator overlays a soft state ribbon across the chart, prints confirmed regime shift labels at the moment of transition, and maintains a compact status panel with the active regime, a composite conviction score, regime duration, and time since the last shift. All outputs are confirmed on bar close with dwell-based hysteresis to suppress noise.
🎯 Unique Edge
Most regime or trend-strength tools collapse the market into a single linear axis (strong ↔ weak, bullish ↔ bearish). Delivery Regime Map is categorical, not linear — it identifies the qualitative character of price delivery by fusing four independent dimensions:
• Displacement quality (how much of each bar's range is body vs. wick)
• Directional persistence (close-to-close consistency + EMA slope alignment)
• Continuity (same-side runs penalized by gap noise)
• Range expansion (current range normalized by ATR baseline)
These dimensions combine into a composite score, but the regime classification uses banded thresholds with hysteresis — meaning a Directional tape must decisively lose its edge before flipping to Fragmented or Exhausted. This produces sparse, high-conviction transitions rather than the constant flipping typical of single-value strength meters.
⚙️ Methodology
The engine computes five rolling metrics across a user-defined window (default 20 bars):
1. Displacement Quality — |close − open| / range, smoothed. High values mean strong, decisive bars with minimal wick rejection.
2. Directional Persistence — average signed close direction plus an EMA slope-alignment check. Rewards tapes that move one way without reversing.
3. Continuity — the proportion of consecutive same-side candles, penalized by an average gap-size term (opens far from prior closes indicate fractured delivery).
4. Range Expansion — current range vs. ATR baseline, clipped to . High expansion combined with low continuity flags Fragmented tapes.
5. Exhaustion Proxy — the decay rate of displacement quality after a period of high persistence. Triggers near trend terminations where bars shrink while direction lingers.
A classifier selects the active regime by priority (Directional → Exhausted → Fragmented → Balanced), and a dwell-bar confirmation (default 5 bars, or 8 under Strict mode) plus a minimum-gap filter (default 10 bars) prevent whipsaw transitions.
🚦 Signals & Alerts
Four alert conditions are built in, each firing only on a confirmed regime shift:
• Regime shifted to Directional — conviction is rising; the tape is trending
• Regime shifted to Fragmented — wide, disconnected bars; chop risk elevated
• Regime shifted to Exhausted — prior trend is losing steam; mean-reversion risk
• Regime shifted to Balanced — low-conviction state; breakout potential building
All alerts include the ticker and interval in the message payload.
🎛️ Key Inputs
• Regime Window (8–60) — length of the measurement window
• Regime Sensitivity (Low / Normal / High) — hysteresis band width
• Strict Classifier — extends dwell requirement from 5 to 8 bars
• Minimum Bars Between Shifts — anti-chop spacing filter
• Show State Ribbon / Regime Shift Labels — visual toggles
• Panel Position + Font Size — 6 anchor positions, 5 size options
• Label Font Size — matches user's chart density preference
Every input carries an inline tooltip explaining its behavior and tradeoffs.
📚 How to Use
• Use Directional regimes to favor trend-following entries and trailing stops
• Use Balanced regimes to prepare for breakouts; volatility compression often precedes expansion
• Use Fragmented regimes as a caution flag — reduce size, widen stops, or stand aside
• Use Exhausted regimes to tighten trailing stops on open trend positions; the edge may be fading
DRM is designed to be asset-agnostic and timeframe-agnostic. On lower timeframes (1m–15m), consider Strict mode and a larger minimum-gap value. On daily charts, defaults typically work well. Combine with any entry framework — order blocks, breakout levels, VWAP reclaims — as a regime filter that answers "should I even be looking for a setup here?"
⚠️ Limitations & Transparency
• The classifier is reactive, not predictive — it confirms regime changes on close, so a Directional label appears a few bars after the trend has begun. This is by design: dwell confirmation is the primary noise filter.
• Regime definitions are categorical interpretations of price statistics. They are not forecasts.
• The composite score reflects regime conviction, not directional bias. A high score in Fragmented means "confidently choppy", not "confidently bullish".
• This indicator is not a strategy. It produces no entry signals, no take-profit targets, and no stop-loss levels. It is a market-context tool intended to be combined with a trader's existing framework.
• Past regime behavior does not guarantee future regime behavior. Market character can change abruptly on news or macro events.
📜 Risk Disclosure
This indicator is published for educational and analytical purposes only. It does not constitute financial advice, a trading recommendation, or an offer to buy or sell any instrument. Trading and investing carry risk of loss, and past performance does not guarantee future results. Users are solely responsible for their own decisions and should consult qualified professionals before committing capital. Indicator

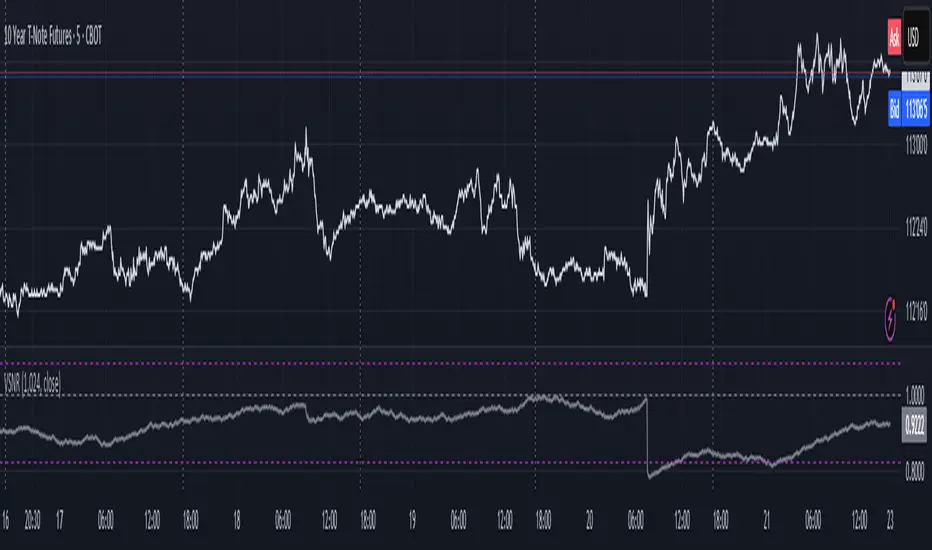
Volatility Signal-to-Noise Ratio🙏🏻 this is VSNR: the most effective and simple volatility regime detector & automatic volatility threshold scaler that somehow no1 ever talks about.
This is simply an inverse of the coefficient of variation of absolute returns, but properly constructed taking into account temporal information, and made online via recursive math with algocomplexity O(1) both in expanding and moving windows modes.
How do the available alternatives differ (while some’re just worse)?
Mainstream quant stat tests like Durbin-Watson, Dickey-Fuller etc: default implementations are ALL not time aware. They measure different kinds of regime, which is less (if at all) relevant for actual trading context. Mix of different math, high algocomplexity.
The closest one is MMI by financialhacker, but his approach is also not time aware, and has a higher algocomplexity anyways. Best alternative to mine, but pls modify it to use a time-weighted median.
Fractal dimension & its derivatives by John Ehlers: again not time aware, very low info gain, relies on bar sizes (high and lows), which don’t always exist unlike changes between datapoints. But it’s a geometric tool in essence, so this is fundamental. Let it watch your back if you already use it.
Hurst exponent: much higher algocomplexity, mix of parametric and non-parametric math inside. An invention, not a math entity. Again, not time aware. Also measures different kinds of regime.
How to set it up:
Given my other tools, I choose length so that it will match the amount of data that your trading method or study uses multiplied by ~ 4-5. E.g if you use some kind of bands to trade volatility and you calculate them over moving window 64, put VSNR on 256.
However it depends mathematically on many things, so for your methods you may instead need multipliers of 1 or ~ 16.
Additionally if you wanna use all data to estimate SNR, put 0 into length input.
How to use for regime detection:
First we define:
MR bias: mean reversion bias meaning volatility shorts would work better, fading levels would work better
Momo bias: momentum bias meaning volatility longs would work better, trading breakouts of levels would work better.
The study plots 3 horizontal thresholds for VSNR, just check its location:
Above upper level: significant Momo bias
Above 1 : Momo bias
Below 1 : MR bias
Below lower level: significant MR bias
Take a look at the screenshots, 2 completely different volatility regimes are spotted by VSNR, while an ADF does not show different regime:
^^ CBOT:ZN1!
^^ INDEX:BTCUSD
How to use as automatic volatility threshold scaler
Copy the code from the script, and use VSNR as a multiplier for your volatility threshold.
E.g you use a regression channel and fade/push upper and lower thresholds which are RMSEs multiples. Inside the code, multiply RMSE by VSNR, now you’re adaptive.
^^ The same logic as when MM bots widen spreads with vola goes wild.
How it works:
Returns follow Laplace distro -> logically abs returns follow exponential distro , cuz laplace = double exponential.
Exponential distro has a natural coefficient of variation = 1 -> signal to noise ratio defined as mean/stdev = 1 as well. The same can be said for Student t distro with parameter v = 4. So 1 is our main threshold.
We can add additional thresholds by discovering SNRs of Student t with v = 3 and v = 5 (+- 1 from baseline v = 4). These have lighter & heavier tails each favoring mean reversion or momentum more. I computed the SNR values you see in the code with mpmath python module, with precision 256 decimals, so you can trust it I put it on my momma.
Then I use exponential smoothing with properly defined alphas (one matches cumulative WMA and another minimizes error with WMA in moving window mode) to estimate SNR of abs returns.
…
Lightweight huh?
∞ Indicator

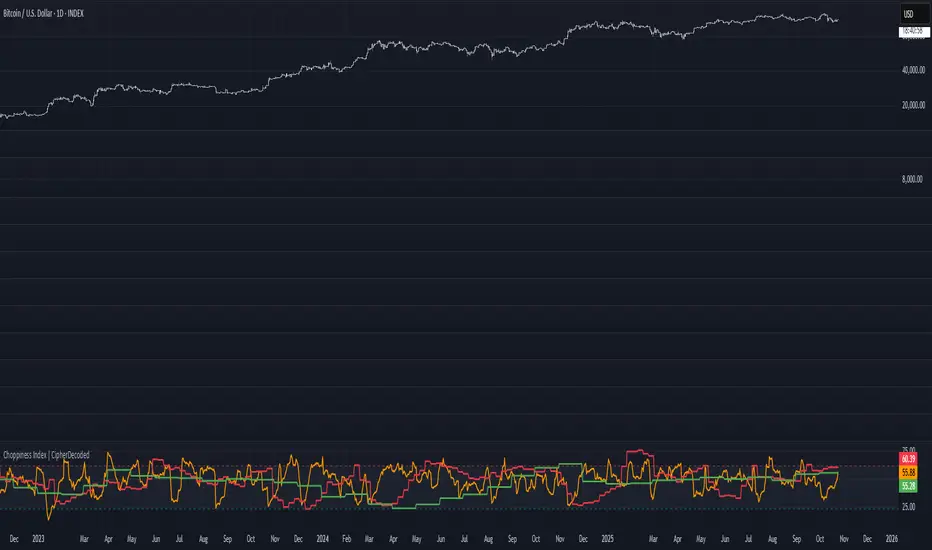
Choppiness Index | CipherDecodedThe Choppiness Index is a multi-timeframe regime indicator that measures whether price action is trending or consolidating.
This recreation was inspired by the Choppiness Index chart from Checkonchain, with full credit to their team for the idea.
🔹 How It Works
CI = 100 * log10( SUM(ATR(1), n) / (highest(high, n) – lowest(low, n)) ) / log10(n)
Where:
n – lookback length (e.g. 14 days / 10 weeks / 10 months)
ATR(1) – true-range of each bar
SUM(ATR(1), n) – total true-range over n bars
highest(high, n) and lowest(low, n) – price range over n bars
Low values → strong trend
High values → sideways consolidation
Below is a simplified function used in the script for computing CI on any timeframe:
f_ci(_n) =>
_tr = ta.tr(true)
_sum = math.sum(_tr, _n)
_hh = ta.highest(high, _n)
_ll = ta.lowest(low, _n)
_rng = _hh - _ll
_rng > 0 ? 100 * math.log10(_sum / _rng) / math.log10(_n) : na
Consolidation Threshold — 50.0
Trend Threshold — 38.2
When Weekly CI < Trend Threshold, a trending zone (yellow) appears.
When Weekly CI > Consolidation Threshold, a consolidation zone (purple) appears.
Users can toggle either background independently.
🔹 Example Background Logic
bgcolor(isTrend and Trend ? color.new(#f3e459, 50) : na, title = "Trending", force_overlay = true)
bgcolor(isConsol and Cons ? color.new(#974aa5, 50) : na, title = "Consolidation", force_overlay = true)
🔹 Usage Tips
Observe the Weekly CI for regime context.
Combine with price structure or trend filters for signal confirmation.
Low CI values (< 38) indicate strong trend activity — the market may soon consolidate to reset.
High CI values (> 60) reflect sideways or range-bound conditions — the market is recharging before a potential new trend.
🔹 Disclaimer
This indicator is provided for educational purposes.
No trading outcomes are guaranteed.
This tool does not guarantee market turns or performance; it should be used as part of a broader system.
Use responsibly and perform your own testing.
🔹 Credits
Concept origin — Checkonchain Choppiness Index Indicator