Long
ALLO: When Cell Therapy Moves from the Hospital to the ClinicNASDAQ:ALLO
Allogene Therapeutics develops allogeneic CAR-T products - ready-made, frozen cell therapies that can be administered to patients in an outpatient setting, without weeks of individual manufacturing. This is a fundamentally different approach to treating oncological and autoimmune diseases. The company trades on NASDAQ.
Q2 2026
Results released today, August 12. Collaboration revenue of $4.64 million - a one-time payment from the termination of a licensing agreement with Overland Therapeutics, not reflective of commercial sales. Net loss $42.7 million, improved from $50.9 million a year ago. EPS of -$0.13 versus analyst consensus of -$0.17, a 23.5% beat. R&D expenses $30.7 million, G&A $20.8 million. Cash and short-term investments reached $423.6 million, up from $258.3 million at year-end 2025. Management confirmed funding of operations into 2029. Full-year operating expense guidance: approximately $165 million non-GAAP, approximately $225 million GAAP including $35 million in stock-based compensation.
Key Event - July 29, 2026
The FDA granted cema-cel both RMAT and Fast Track designations for first-line consolidation therapy in large B-cell lymphoma patients with positive minimal residual disease status. The basis: interim ALPHA3 analysis showing 58.3% MRD negativity in the cema-cel arm versus 16.7% in the observation arm (a difference of 41.6 percentage points), with a median ctDNA reduction of 97.7%. At the data cutoff, covering 12 patients in the treatment arm, no CRS, ICANS, GvHD, treatment-related serious adverse events or treatment-related hospitalizations were observed. Most patients were treated entirely in the outpatient setting, including centers with no prior CAR-T experience. RMAT status enables more frequent FDA engagement, rolling review, and potential eligibility for accelerated approval.
Pipeline
ALLO-329 for autoimmune diseases - systemic lupus erythematosus, scleroderma, and inflammatory myositis is actively enrolling patients in the Phase 1 RESOLUTION trial. A clinical data update is expected in Q4 2026. ALLO-316 for metastatic renal cell carcinoma demonstrated a 31% confirmed response rate in Phase 1. Full results were published in the Journal of Clinical Oncology on July 15, 2026.
Key Dates
Approximately 100 clinical sites expected to be active by year-end 2026 across the US, Canada, Australia and South Korea - the site activation target was reached six months ahead of schedule. ALPHA3 enrollment expected to complete by year-end 2027. Interim event-free survival (EFS) analysis expected mid-2027.
Capital Structure and Valuation
Cash and investments of $423.6 million. Total liabilities $113.9 million, no direct long-term debt. At current market capitalization, the market is pricing the operating business at a deep discount to the cash and investment position on the balance sheet. Analyst consensus of 9 firms: average target $9.00, range $4–14, Outperform status. No dividends or buyback program.
What the Market Is Missing?
The market views ALLO as an ordinary clinical-stage biotech. In doing so, it overlooks two facts. First: RMAT and Fast Track were granted not on promises but on real interim data showing 58.3% MRD negativity with no serious toxicity at the time of the analysis. Second: if the efficacy and safety profile is confirmed in a larger cohort, the outpatient model could potentially expand CAR-T applicability well beyond specialized inpatient centers. One third of infusions have already been administered at community cancer centers with no prior CAR-T experience.
Risks
The mid-2027 EFS interim analysis will require demonstration of overwhelming efficacy a strict statistical threshold set by the regulator. Safety data are based on a cohort of 12 patients and will expand as enrollment continues. In April 2026, the company completed a public offering of 100.2 million shares at $2.00, significantly increasing shares outstanding. Competition from classical autologous CAR-T therapies and the emerging in vivo gene therapy sector remains a genuine threat.
Technicals
The weekly chart is forming a bullish technical configuration with signs of a potential long-term trend reversal. An extended base in the form of a rounded bottom concluded with an impulsive breakout above the multi-year descending trendline on elevated volume. A golden cross pattern is forming as MA50 crosses MA100 from below. The current pullback is creating a confluence zone in the $1.63–$1.83 range, where the 78.6% Fibonacci retracement level, the dynamic MA50, and the mirror level of the prior accumulation structure all converge. First target $3.79, second intermediate target $5.78.
This publication is for analytical purposes only and does not constitute individual investment advice. Share your thoughts in the comments and support the idea with a like if the analysis was useful.  Long

 Long
Elevance Health | ELV | Long at $286.00What are seeing in the healthcare and health insurance provider industry right now is destruction before a once-in-a-lifetime boom. The baby boomer generation is between 60 and 79 right now and the amount of healthcare service that will be needed to serve that population is staggering. Institutions are crushing them to get in - it's just near-term noise, in my opinion. My personal strategy is buy and hold every healthcare opportunity (i.e. NYSE:CNC , NYSE:UNH , NYSE:HUM etc).
Elevance Health NYSE:ELV just dropped heavily due to lower-than-expected Q2 2025 earnings, a cut in full-year profit guidance from $34.15-$34.85 to ~$30 EPS, and elevated medical costs in Medicaid and ACA plans. It's near-term pain (may last 1-2 years) which will highly likely lead to long-term growth. The price has touched my historical simple moving average "crash" band. I would not be shocked to see the price drop further into the $260s before a rise. However, the near-term doom could go further into the year. I am anticipating another drop to the "major crash" simple moving average band into the $190s and $220s to close out the remaining price gaps on the daily chart that occurred during the COVID crash. Not to say it will absolutely reach that area, but it's locations on the chart I have for additional buys.
Thus, at $286.00, NYSE:ELV is in a personal buy zone (starter position) with more opportunities to gather shares likely near $260 before a bounce. However, if the market or healthcare industry really turns, additional buys planned for $245 and $212 for a long-term hold.
Targets into 2028:
$335.00 (+17.1%)
$386.00 (+35.0%)
 Long

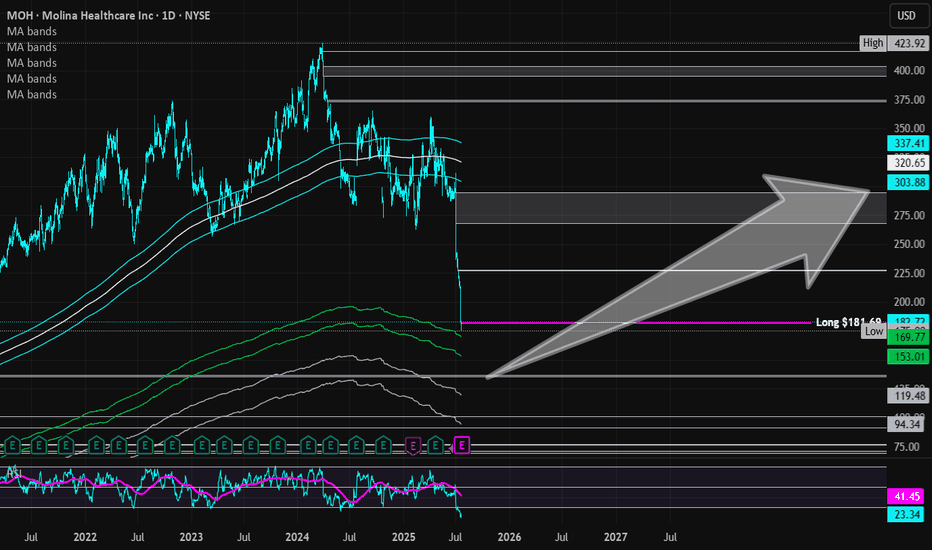
Molina Healthcare | MOH | Long at $181.69Healthcare providers and services are at a major discount right now: and may be discounted even more this year. I am personally buying and long-term holding the fear, knowing the baby boom generation is going to utilize our healthcare system at a rate unseen in modern times. While the price discounts are valid "right now" given the current political administration's cuts, long-term it is far from valid... The strategy I am using with healthcare stocks ( NYSE:MOH , NYSE:CNC , NYSE:UNH , NYSE:ELV , etc) is cost averaging: not buying one single large position in an effort to predict bottom but buying smaller positions over time to create a cost average "near" bottom. If you are a day trader or want a quick swing in healthcare, I don't think it's going to happen for a bit. But those not entering in the coming months / year will likely miss out on a very large healthcare boom - especially when AI truly enters the picture in this sector...
Fundamentally, Molina Healthcare NYSE:MOH is a very strong company. Low debt-to-equity (.9x), P/E of 8.8x, quick ratio of 1.7x, $41 billion in revenue in 2024. Yes, there will be issues in the near-term due to Medicaid and other funding cuts. But long-term, this sector is primed to benefit from an aging population.
So, while NYSE:MOH is in a personal buy zone at $181.69, I don't think this is necessarily bottom. I anticipate this stock to drop even further, eventually closing the daily price gap at $135.00. My next buys are in the $150's and $130's, thus cost averaging into a larger position. For true value investors, those prices and anything below is a steal. Today's negative healthcare sector noise is loud, but it does not represent the future.
Targets into 2028:
$226.00 (+24.3%)
$290.00 (+59.6%)
 Long
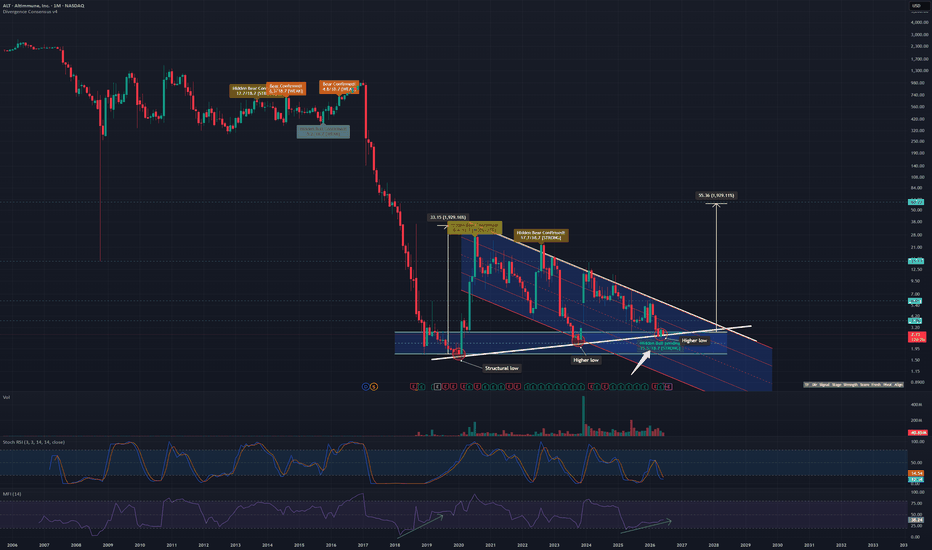
$0.5b in cash, "FDA Breakthrough" designation, a monster chartINTRODUCTION:
This is a bio with over $500m cash on hand that's also riding the FDA fast-track train for it's main pipeline. The $0.5b purse funds them till at least 2029. I'm not gonna elaborate on the details of what they're working on. Suffice to say, this combination of very high funding and a compound candidate that has received the "FDA Breakthrough" designation usually signals high confidence in the thing being effective ( NASDAQ:QURE being a recent example of this dynamic).
THE TA:
The 1M chart provides a solid basis for presentation of the following logic.
1. Price action remains in a correction/distribution downtrend after a breakthrough to the upside following a collapse in 2017.
2. Following the structural low that printed before the breakthrough, the subsequent downtrend has printed two higher lows that together with the structural form a horizontal channel of support/resistance.
3. The ceiling of the current downtrend combined with a trendline drawn through the structural local higher lows produces a wedging continuation pattern.
4. The wedge extension forecasts price action going to $60 (exactly where a resistance horizontal lurks), a 2000% move.
5. The previous 2000% move happened after the reverse stock splits (last split was 8 years ago). Therefore the historic move wasn't distorted by the splits. It was organic. This ticker is proven capable of such action despite the price scale being skewed by the splits. It's also a bio so moves like that are really not that special in this sector.
6. The 1M MFI currently exhibits behavior similar to that preceding the previous 2000% move — an over one year-long bullish divergence against the price action (MFI is rising while price action is falling). This suggests ongoing accumulation.
7. The Divergence Consensus tool prints a strong pending divergence on current candles or on neighboring ones across a plethora of higher timeframes: 1M, 4W, 5W, 6W, 19D-26D (moderate divergences print on many neighboring timeframes with the ones listed).
8. 1M Stochastic RSI is already in oversold territory, right as the new higher low is printing. In my opinion, it will print successfully.
SUPPLEMENTAL TA:
1. The 10W sRSI is pretty much at rock bottom. This has happened only once before — during the collapse in 2017. The 2000% move followed as the 10W sRSI crossed up 20. Since the company is in a completely different position now, the 10W sRSI should spend a lot less time in the basement. The move up once the 10W sRSI starts crossing up 20 should be just as energetic as the one that took price action to $35 in 2020.
2. On the 1W, price action is currently below a red Gaussian Channel. Historically, whenever ALT's price action printed below a red Gaussian Channel, it always exploded or climbed back in, and then punched through the ceiling. ALT has a 100% hit rate on this. No reason to think this time will be different.
FINAL WORDS:
A confirmation of support at circa $2.9 will be an important signal. It can happen slowly (over several candles), or violently (by just punching through it to the upside). A meaningful close below $1.7 on 1W at least invalidates the idea. If/when the breakout starts, expect resistance at the horizonal dashed-lines on the chart.
***
The above was written by hand.
The above is not investment advice.
I am not a professional trader or analyst.  Long
GoHealth | GOCO | Long at $6.05GoHealth NASDAQ:GOCO is a health insurance marketplace and Medicare-focused digital health company that uses a technology platform with machine-learning algorithms to match consumers with Medicare plans (Advantage, Supplement, Part D) and individual health insurance. Understandably, a lot of investors aren't bullish on this stock given all of the healthcare provider and services headwinds. However, if the company can overcome some of their financial issues and bankruptcy risk (debt-to-equity: 1.6x; quick ration of 1.1x, Altman's Z score of .3x), it may dominate the health insurance marketplace (but do not hold my word to that...). This is a purely speculative play at this point - those who are risk averse should absolutely stay away.
What truly caught my eye with this stock is that it is consolidating nicely within my historical simple moving average area. Often, but not always, this leads to a future change in momentum and propels the stock higher. It doesn't signal a bottom and there may be more room for it to plummet, but it is a bullish (overall) sign that shares are likely being accumulated by investors. Given the need for health insurance, particularly Medicare as the US / baby boom population ages, this is a company that may prosper IF it can get its financials in order.
Thus, at $6.05, NASDAQ:GOCO is in a personal buy zone (but very risky). Further declines may be ahead before a stronger move up.
Targets into 2028:
$10.00 (+64.5%)
$12.00 (+97.4%)
 Long

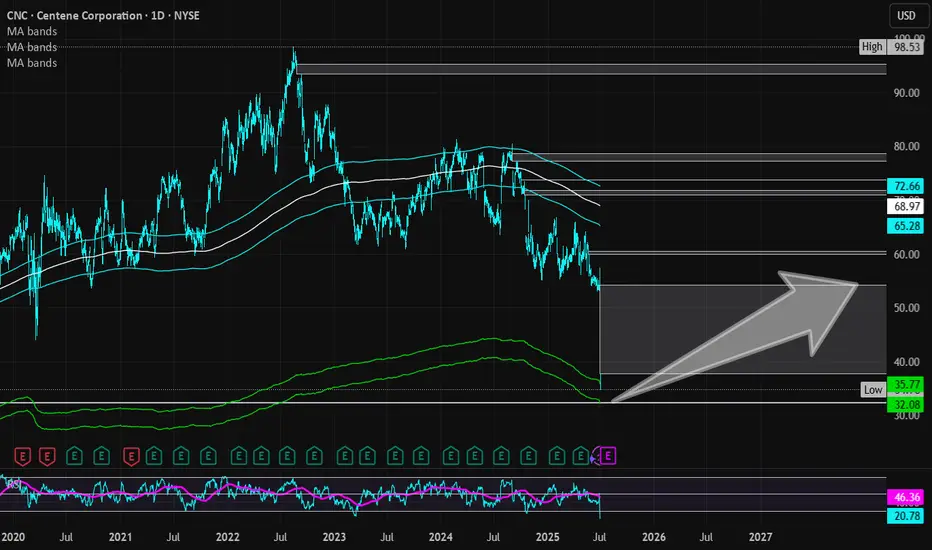
Centene Corp | CNC | Long at $35.00Centene Corp NYSE:CNC is a healthcare enterprise providing programs and services to under-insured and uninsured families, commercial organizations, and military families in the U.S. through Medicaid, Medicare, Commercial, and other segments. The stock dropped almost 40% this morning due to recent challenges, such as a $1.8B reduction in 2025 risk adjustment revenue and rising Medicaid costs (leading to withdrawal of 2025 earnings guidance). However, the company has a book value near $56, debt-to-equity of 0.7x (healthy), a current P/E of 5x, and a forward P/E of 9x.
It may be a few years before this stock recovers. But the price has entered my "crash" simple moving average area (currently between $32 and $36) and there is a price gap on the daily chart between $32 and $33 that will likely be closed before a move higher. Long-term, and potentially a new political administration, new life may enter this stock once again as the baby boom generation requires more healthcare services. But holding is not for the faint of heart...
Thus, at $35.00, NYSE:CNC is in a personal buy zone with a likely continued dip into the low $30s or high $20s before a slow move higher (where I will be accumulating more shares). Full disclosure: I am also a position holder in the $60s and cost averaging down.
Targets into 2028:
$45.00 (+28.6%)
$54.00 (+54.3%)
 Long

WEEKLY MARKET OUTLOOK – BULLS SLOWLY TAKING CONTROLNIFTY 50 – WEEKLY STRUCTURE TURNING POSITIVE
Nifty closed at 24,176, up around 180 points from the previous week.
Weekly High: 24,482 | Weekly Low: 23,882
Last week, I highlighted 23,796 as the key support, and once again price respected that zone perfectly.
While the monthly timeframe is still not fully bullish, the good news for bulls is that the weekly structure is now gradually turning positive.
MARKET REGIME
Short-term: Bullish consolidation
Medium-term: Transition toward bullish structure
Monthly timeframe: Still awaiting confirmation
This suggests markets are slowly shifting from consolidation → expansion phase.
NIFTY – LEVEL MAP
Key Resistance
👉 24,400
Sustaining above 24,400
→ opens path toward:
24,600 → 24,800
Key Support
👉 23,800
Only a consecutive day close below 23,800 can bring bears back into action
For now, it appears the bears had their opportunity, and the market may now gradually start making space for bulls.
BANK NIFTY – THE REAL DRIVER
Bank Nifty closed at 55,310, up ~450 points week-on-week.
Interestingly, both Nifty & Bank Nifty charts are looking structurally similar, which means:
👉 Bank Nifty will likely decide the next directional move for Nifty
And right now, the setup looks ripe for expansion.
Expected Range:
👉 56,800 – 53,800
If Bank Nifty sustains strength, broader market momentum can improve significantly.
S&P 500 – BULLISH MOMENTUM CONTINUES
S&P 500 closed at 7,398, almost 200 points higher and near the weekly highs.
Most importantly:
👉 The index successfully achieved the first target of 7,334, mentioned earlier.
Now the focus shifts toward:
7,465
7,485
7,530
7,564
As long as momentum remains intact, global markets may continue supporting risk-on sentiment.
SECTORAL FOCUS (IMPORTANT)
From 11th May onwards, keep close watch on:
👉 Pharma
👉 Healthcare
👉 Auto
👉 Infrastructure
These sectors may start showing relative strength and leadership in the coming phase.
FINAL VIEW
Nifty: Weekly structure improving
Bank Nifty: Key index to watch
S&P500: Momentum remains bullish
Market structure: Slowly shifting toward bullish expansion
Expect range-bound to bullish movement with stock-specific opportunities improving.
CLOSING INSIGHT
Markets rarely ring a bell at the bottom.
By the time higher timeframes fully turn bullish, a large part of the move is often already over.
The key is to observe structure, not emotions. NVO: Quality Stock, Broken Trend — The Reversal MapNovo Nordisk is a clean example of why quality alone is not an entry.
Fundamentally, this is not a weak business.
But technically, the chart is still under pressure.
On the daily timeframe, NVO remains trapped inside a broad bearish channel after a major decline from its highs. The first bearish ABC target has already been reached, but the larger bearish sequence still leaves room for a deeper capitulation move if buyers fail to reclaim structure.
The key detail here is the rejected BC zone .
Price pushed into the upper BC area, tested it, and sellers defended it. That keeps the bearish lower-high structure alive. So I am not treating the current price as a confirmed reversal yet.
This is the map I’m watching:
Bearish case:
As long as price stays below the descending structure and fails to reclaim the BC zone, the larger bearish C target remains open. That lower pink target area could become the real panic zone where weak hands get forced out.
Bullish case:
If price drives lower into that target area, then starts showing real displacement, market structure shift, and strong reclaim behavior, NVO becomes very interesting. Not because it “looks cheap,” but because the downside sequence would be mature and buyers would finally be proving themselves.
For me, the clean reversal confirmation would be:
Price sweeps deeper liquidity or taps the larger bearish C target zone
Buyers step in with displacement, not weak sideways candles
Daily structure shifts bullish
Price reclaims the bearish channel
BC zone turns from resistance into support
Only then does the upside map open.
First major upside objective would be the rejected BC region around the mid-$60s.
After that, the old bearish target / supply area near the $80–$90 region becomes the next logical magnet.
My read:
NVO is a quality company inside a damaged chart.
That combination can create major opportunity, but only after structure confirms.
Buying just because the stock is down is emotional.
Waiting for capitulation, reclaim, and structure shift is disciplined.
The chart is not saying “buy now.”
It is saying: prepare, mark the levels, and wait for proof.
Not financial advice.  Long

HIMS 1W: Subscription growth meets corrective mathHims & Hers Health operates a direct-to-consumer telehealth platform built on a recurring subscription model. The company scales digital consultations and pharmacy services, making it a high-beta growth stock sensitive to expansion and contraction cycles.
On the weekly chart, the prior impulsive move to 70+ has completed, and the market is developing an ABC corrective structure. Wave A declined toward 24, wave B retraced back toward 70, and wave C is currently unfolding.
Using a 1.272 projection of the AB move, the calculated completion zone for wave C is approximately 11.41. Current price at 16.30 indicates C remains in progress. The 11–12 region also aligns with the long-term rising diagonal support, strengthening the technical significance of that zone.
Indicators show momentum deceleration rather than reversal. ADX is declining, signaling weakening trend strength. DI− remains dominant but without acceleration. RSI is approaching oversold territory, and Stochastic is positioned in the lower range. This reflects exhaustion of downside impulse, not confirmed accumulation.
The structural focus is clear: potential completion of wave C near 11–12. Confirmation requires a local higher low and a recovery above 25–26 to shift structure back into expansion.
Before growth resumes, markets often reset excess.
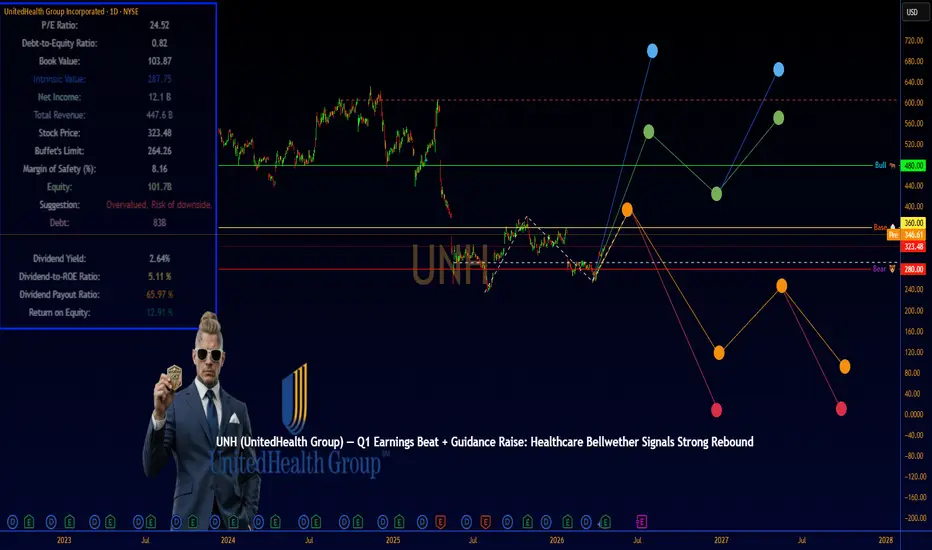
UNH (UnitedHealth Group) — Q1 Earnings Beat + Guidance Raise**💡 UNH (UnitedHealth Group) — Q1 Earnings Beat + Guidance Raise: Healthcare Bellwether Signals Strong Rebound**
**SECTION 1 — Executive Summary** 💼
UnitedHealth Group delivered a decisive Q1 2026 earnings beat with adjusted EPS of $7.23 (versus ~$6.57 consensus) and revenue of $111.7 billion (+2% YoY), while raising full-year 2026 adjusted EPS guidance to >$18.25 amid disciplined pricing, cost controls, and Optum optimization. This mega-cap healthcare leader offers compelling value as it navigates medical cost pressures and regulatory scrutiny with a clear path to margin recovery and diversified growth. Overall rating: Buy. 12-month price target: $360 (blended DCF/comps methodology using normalized medical loss ratios and Optum contribution). The single biggest reason to own this stock right now is UnitedHealth’s unmatched scale across insurance and services (Optum), positioning it to capture long-term healthcare spending tailwinds while executing a proven turnaround plan. The single biggest risk remains elevated medical costs and Medicare Advantage reimbursement dynamics.
**SECTION 2 — Business Overview** 🏢
UnitedHealth Group is the largest healthcare company in the United States, operating through two primary platforms: UnitedHealthcare (insurance and benefits) and Optum (health services, pharmacy care, and technology). Revenue breakdown (FY 2025): UnitedHealthcare ~77% (insurance premiums and fees), Optum ~23% but with higher margins and faster growth in value-based care, PBM, and data/analytics (sourced from company FY 2025 results released Jan 27 2026). Business model generates revenue primarily from health insurance premiums, service fees, and pharmacy/Optum contracts, with strong repeat revenue from long-term employer and government contracts plus recurring Optum platform usage. Competitive moat derives from massive scale (serving ~50 million via UnitedHealthcare and 123+ million via Optum in 2025), proprietary data assets, integrated care delivery, and network effects that are extremely difficult for competitors to replicate at similar efficiency.
**SECTION 3 — Financial Deep Dive** 📈
Key metrics (Q1 2026 reported April 21 2026; FY 2025 from Jan 27 2026 release; TTM derived from quarterly data):
Revenue: $111.7 billion (Q1 2026, +2% YoY); FY 2025 $447.6 billion (+12% YoY).
Net income: Implied from EPS; Q1 GAAP EPS $6.90.
EPS (adjusted): $7.23 (Q1 2026, beat by ~66 cents).
Margins: Medical care ratio pressured but stabilizing; operating margin recovering.
Free cash flow: Strong at $8.9 billion in Q1 2026 (1.4x net income).
YoY growth rates: Revenue +2% (Q1); FY 2025 revenue +12%.
Balance sheet health: Debt-to-capital ratio 42.9% (March 31 2026); cash flow supportive of leverage targets.
Cash flow quality: Operating cash flow consistently exceeds net income (1.4-1.5x ratio).
Capital allocation: Focus on R&D/AI investments (~$1.5 billion planned 2026), debt reduction to ~40% target, dividends, and selective M&A while resuming buybacks in H2 2026.
**SECTION 4 — Growth Analysis** 🚀
Total addressable market (TAM): U.S. healthcare spending projected to exceed $6 trillion by 2030 (CMS estimates via industry reports). Current market share: Leading position in Medicare Advantage and commercial insurance; Optum dominant in PBM and value-based care. Key growth drivers next 3-5 years: Optum expansion in AI-enabled care, pharmacy services, and data analytics; UnitedHealthcare focus on employer and government segments with pricing discipline. Management raised 2026 guidance post-Q1 beat, signaling more bullish outlook than prior consensus; growth increasingly organic through technology leverage and portfolio optimization rather than acquisition-dependent.
**SECTION 5 — Valuation** 📊
DCF analysis: Base case assumes mid-single-digit revenue CAGR, expanding operating margins to 5.5%+, WACC ~9%, terminal growth 3% . Implied value supports $360 target. Comparable company analysis (peers as of April 2026): CI ~12-14x forward P/E; ELV, HUM, CNC at 10-13x; UNH trades at premium but justified by scale. Historical valuation range (5-year): Forward P/E 18-25x. Bull target $420 (accelerated Optum AI gains); Base $360; Bear $280 (prolonged cost pressures). Current price ~$280-300 offers 20-30% upside to base target.
**SECTION 6 — Risk Analysis** ⚠️
1. Medical cost trend escalation (high probability/medium impact): Triggered by utilization spikes; watch quarterly medical loss ratio updates.
2. Regulatory changes in Medicare Advantage (medium-high): Reimbursement cuts or policy shifts; monitor CMS announcements.
3. Optum contract losses or margin compression (medium): Strategic exits noted; track segment earnings.
4. Cyber or operational disruptions (medium): Legacy from 2024-2025 events; monitor investment disclosures.
5. Macro healthcare spending slowdown (low-medium): Economic factors; watch employment data.
Short interest low; insider activity shows typical patterns with no major red flags. No new accounting quality flags noted in latest filings.
**SECTION 7 — Catalyst Calendar** 📅
Next earnings date: Already reported Q1 on April 21 2026 (conference call today at 8:00 AM ET). Upcoming events: Optum AI and technology updates throughout 2026; potential Medicare bid outcomes. Macro events: Federal budget/health policy decisions impacting reimbursement. 12-month timeline: Q2 earnings July 2026, continued membership adjustments, and leverage reduction milestones.
**SECTION 8 — Technical Analysis** 📈
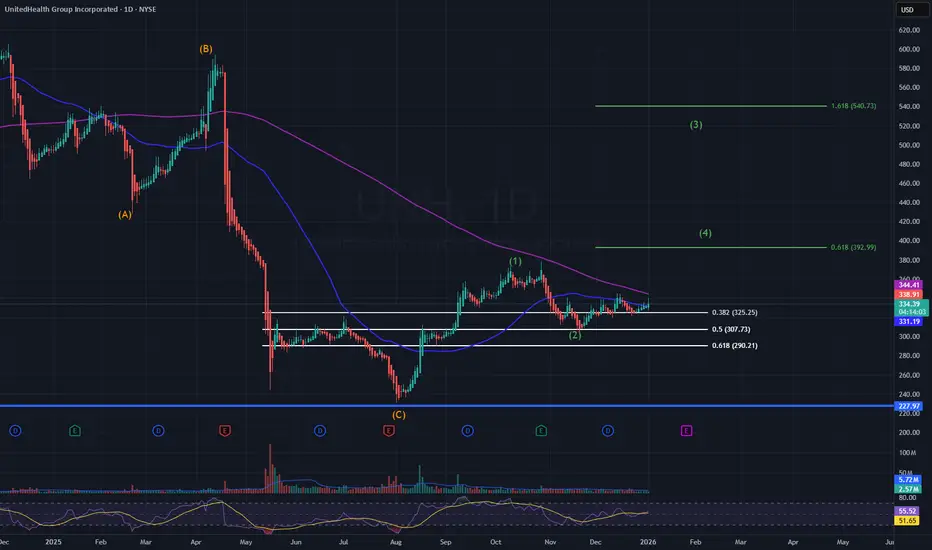
Primary Chart: Daily timeframe, 1-year view shows UNH consolidating in the $270-300 zone after 2025-2026 volatility, with today’s post-earnings reaction pushing toward recent highs. Price action recently crossed above the 50-day moving average while holding above key support; RSI (14) moving out of oversold territory with bullish MACD crossover and expanding volume. Major support zone $260-270, resistance $310-320. Visible setup: Potential inverse head-and-shoulders base with higher lows since February. Technical implication: Bullish bias confirmed by earnings catalyst with room for near-term continuation if volume sustains.
**SECTION 9 — The Verdict** 🏆
Bull case ($420 target, 30 percent probability): Faster-than-expected margin recovery and Optum AI acceleration drive re-rating.
Base case ($360 target, 50 percent probability): Steady execution on guidance with controlled medical costs.
Bear case ($280 target, 20 percent probability): Persistent cost pressures or regulatory headwinds cap upside.
Expected value calculation: Probability-weighted price target = $366. Final recommendation: Buy with High conviction. The 30-second elevator pitch: UnitedHealth just proved it can deliver despite industry challenges — with a Q1 beat, raised guidance, and unmatched scale across insurance and services, the stock offers attractive risk/reward as healthcare spending grows and margins normalize.
**Sources**
UnitedHealth Group press release April 21 2026 (Q1 2026 results); company FY 2025 results Jan 27 2026; Reuters/Seeking Alpha/Zacks earnings coverage April 21 2026; Yahoo Finance/TradingView charts and data as of April 21 2026; CMS healthcare spending projections.
What are your thoughts on UNH? Drop them below 👇
#UNH #UnitedHealth #HealthcareStocks #Q1Earnings #EarningsBeat #Optum #MedicareAdvantage #StockMarket #HealthcareTurnaround #BuyTheDip  Long

Acadia Healthcare Company | ACHC | Long at $21.98Acadia Healthcare's NASDAQ:ACHC stock has fallen nearly -76% in a year, primarily due to weak 2024 results, missed revenue and EPS expectations, and a soft 2025 revenue guidance. Ongoing federal investigations into billing practices and lawsuits have further eroded investor confidence. However, it is currently trading at a price-to-earnings ratio of 7.42x and earnings are forecast to grow 7.07% per year. The profitable company is trading at a good value compared to other healthcare companies. Debt-to-equity is relatively low (0.64x), but legal risks (DOJ probe, lawsuits) strain margins.
The stock has entered my "major crash" simple moving average territory and there is a lot of downward / selling pressure. But, more often than not, this area (which... I caution... still extends down near $16) can often signal a temporary or longer-term bottom. Personally, this is a buy area ($16-$21) even if it turns into a short-term bounce in 2025. But I believe the overall market moves in the S&P 500, etc. will guide this stock more than anything at this point (unless more bad news about the company emerges).
One thing to note is that there are open price gaps on the daily chart near $17, $10, and $8. These gaps, which often (but not always) get closed in the lifetime of a stock, are a potential signal for further declines - at least at some point. There could be a drop near $16, then a $10-$20 bullish price increase after that, followed by more declines (trapping investors). Time will tell, but NASDAQ:ACHC is currently attractively valued. From a technical analysis standpoint, it is in a personal "buy zone", even if purely for a swing trade.
Targets:
$27.00
$33.00
$39.00
 Long

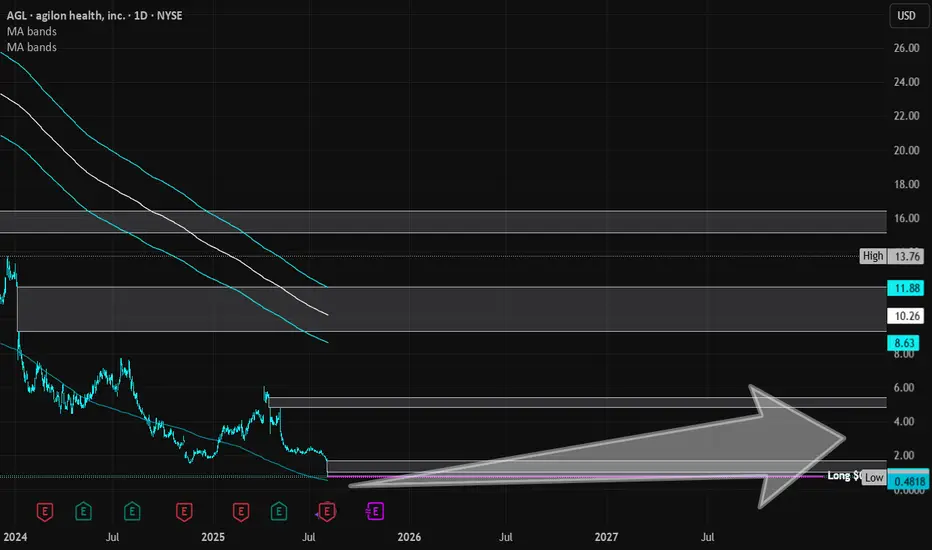
Agilon Health (Revised) | AGL | Long at $0.76This is a revised analysis of Agilon Health NYSE:AGL as seen here:
-------
Full disclosure: I am a holder of shares at $2.36, $0.76, and $0.79. Last entry planned near $0.50 if it reaches that level. Current cost average is near $1.11.
Let me be clear: This is a ***highly risky*** trade given the recent news regarding the CEO, securities fraud investigation, suspension of FY guidance. Do your own due diligence.
-------
The link above/previous writeup details some of the basic fundamentals of Agilon Health NYSE:AGL . As predicted, the price fell below $1 after the most recent earnings call. This was due to:
Revenue down 6% to $1.4B, Medicare Advantage membership at 498,000.
CEO Steve Sell resigning, Ron Williams appointed Executive Chairman.
2025 guidance suspended due to market challenges.
New securities fraud investigations.
I think the challenges NYSE:AGL is going through will extend through 2025 in into early 2026. If you look at the healthcare sector, it has taken a beating mostly due to Medicare and Medicaid cuts / rising healthcare costs. NYSE:AGL is not profitable and wasn't expected to become profitable until 2028 - but that may get revised....
However, the company focuses on senior patients, primarily through Medicare Advantage and ACO REACH programs, targeting value-based care for older adults across 31+ communities in 12 states. The need for services targeting the Baby Boom population is going to rapidly increase in the next few years. NYSE:AGL may become a leader in this area, but the company needs to regroup and focus on a model that returns money to investors - a dirty game. So, while the near-term is doom and gloom, the future could be very, very bright with NYSE:AGL if they are able to turn things around with this new leadership shakeup. Time will tell. It's a gamble. One I am, personally, willing to take.
Revised Targets into 2028:
$1.60 (+110.5%)
$3.00 (+294.7%)
 Long

Long 
Just In: Community Health Systems ($CYH) Gearing for A BreakoutAlbeit surging 16% on Friday's market open, Community Health Systems, Inc. (NYSE: NYSE:CYH ) stock is set for a 200% surge breaking out from the ceiling of a bullish symmetrical triangle.
The $6 resistant is acting as the structure, a small thrust or buying pressure will lead to a BOS further solidifying the bullish thesis on the health stock.
In another news, Community Health Systems, Inc. (NYSE: CYH) yesterday announced financial and operating results for the three and nine months ended September 30, 2025.
About CYH
Community Health Systems, Inc. owns, leases, and operates general acute care hospitals in the United States. The company offers general acute care, emergency room, general and specialty surgery, critical care, internal medicine, obstetrics, diagnostic, psychiatric, and rehabilitation services, as well as skilled nursing and home care services.  Long

Just In: Rani Therapeutics Holdings ($RANI) Surge 168% TodayThe price of Rani Therapeutics Holdings, Inc. ( NASDAQ:RANI ) saw a noteworthy uptick of 168% today after market open.
while the asset is still overbought as seen by the RSI at 93, technical metrics shows that should the stock break the ceiling of the 50% Fib level, NASDAQ:RANI will break new highs today.
In recent news, which could be possible catalyst to the recent spike, Rani Therapeutics (NASDAQ: NASDAQ:RANI ), on Friday announced a licensing deal to develop and sell an oral version of Chugai Pharmaceutical's (4519.T), opens new tab experimental antibody, with options to expand to five additional drugs, potentially valuing the deal at $1.09 billion.
About RANI
Rani Therapeutics Holdings, Inc. operates as a clinical stage biotherapeutics company, focusing on technologies to enable the administration of biologics and drugs orally for patients, physicians, and healthcare systems with a alternative to painful injections in the United States. The company develops the RaniPill capsule, a drug-agnostic oral delivery platform to deliver a variety of drug substances, including oligonucleotides, peptides, proteins, and antibodies.
 Long

Breaking: Praxis Precision Medicine (PRAX) Is Set for 400% SurgeThe price of Praxis Precision Medicines, Inc. (NASDAQ: NASDAQ:PRAX ) Is set for a bullish continuation pattern amidst breaking out of a falling wedge pattern spiking 183% yesterday.
The biopharmaceutical company is set to reclaim the $900 resistant zone this last quarter amidst rising interest in the biopharmaceutical company.
NASDAQ:PRAX is already up 3.56% in Friday's premarket session, even with the RSI at 85- which is clearly overbought.
In another news, Praxis Precision Medicines, Inc. (NASDAQ: NASDAQ:PRAX ) announced the pricing of its underwritten public offering of 3,025,480 shares of its common stock at a public offering price per share of $157.00 and, in lieu of shares of common stock, pre-funded warrants to purchase up to an aggregate of 318,470 shares of common stock at a purchase price of $156.9999 per pre-funded warrant, which equals the public offering price per share of the common stock less the $0.0001 per share exercise price of each pre-funded warrant.
The gross proceeds from the offering are expected to be approximately $525 million, before deducting underwriting discounts and commissions and estimated offering expenses payable by Praxis.
About PRAX
Praxis Precision Medicines, Inc., a clinical-stage biopharmaceutical company, engages in the development of therapies for central nervous system (CNS) disorders characterized by neuronal excitation-inhibition imbalance. The company’s platforms include cerebrum, a small molecule platform for CNS small molecule therapies to develop orally available precision therapies; and solidus to discover and develop antisense oligonucleotide.  Long