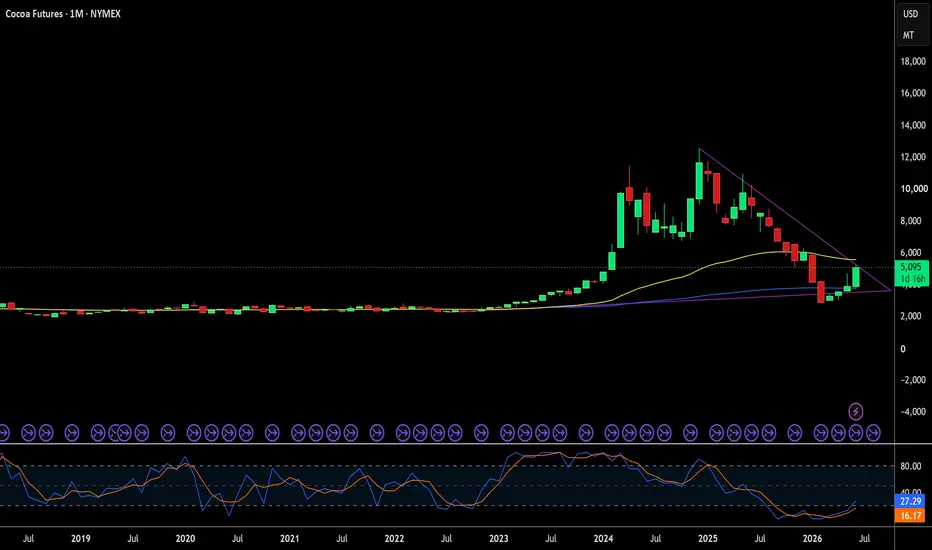
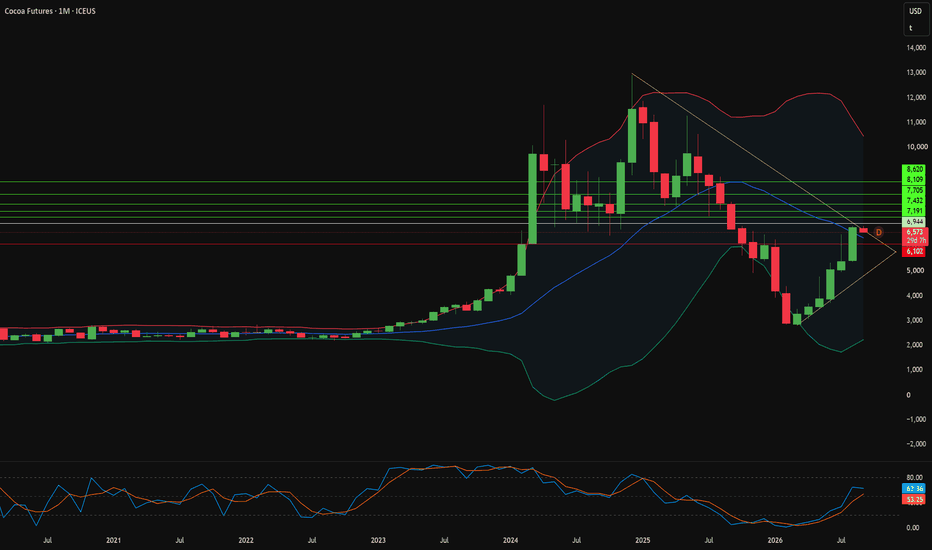
Why Is Cocoa Breaking Out While Demand Weakens?Cocoa futures reclaimed $6,500 per metric ton and closed near $6,771 on the December ICE contract. The move followed a base near $3,000 built in early 2026. Institutional funds entered the rally holding heavy short positions, and deteriorating crop reports forced rapid covering across exchanges. Forecasters cut their numbers hard. StoneX reduced its global surplus estimate from 149,000 MT to 25,000 MT. Transgraph now projects world output falling from 5.11 MMT to 4.87 MMT.
The supply story remains concentrated and fragile. West Africa still controls roughly 96% of bulk export volume. Ghana's Cocoa Board revised its crop to 650,000 MT and warned of 450,000 MT under severe weather. Côte d'Ivoire expects an 18% decline to 1.8 MMT. Swollen shoot virus, aging trees, and an intensifying El Niño pattern all compound the damage. Moving the harvest calendar forward to September 1st changed the paperwork, not the physical beans. Demand tells a split story. European grindings fell 4.6% to a six-year low while North America rose 7.7% and Asian processing expanded 25%.
Technology is now the industry's structural answer. The European Union funded the €5.5M Coco-AI project to advance cell-cultured cocoa platforms. Farms deploy XGBoost yield models achieving R² accuracy of 0.9399, and Papua New Guinea is rolling out 125 solar drying units in East Sepik. Leibniz Institute researchers also proved that overfermentation, not smoke, generates key smoky phenolic compounds. That finding lets buyers separate genuine processing defects from drying contamination, which changes how premium beans get priced.
Verification is the weak link. The EU Deforestation Regulation demands plot-level geolocation proof, yet audit integrity looks poor. Research from ETH Zurich and Cambridge found 25% of audited program entries manipulated. Manipulation dropped to 11% when target metrics were hidden from auditors, and 33% of failed checks triggered retroactive edits. Firms are turning to blockchain ledgers and AI verification because the compliance risk now carries a hard financial cost. Technically, acceptance above $6,500 opens targets at $7,250 and $8,050, with the structural deficit favoring elevated prices.  Long
Can Wheat Futures Trigger a Global Crisis?Geopolitics, Geostrategy, and Macroeconomics
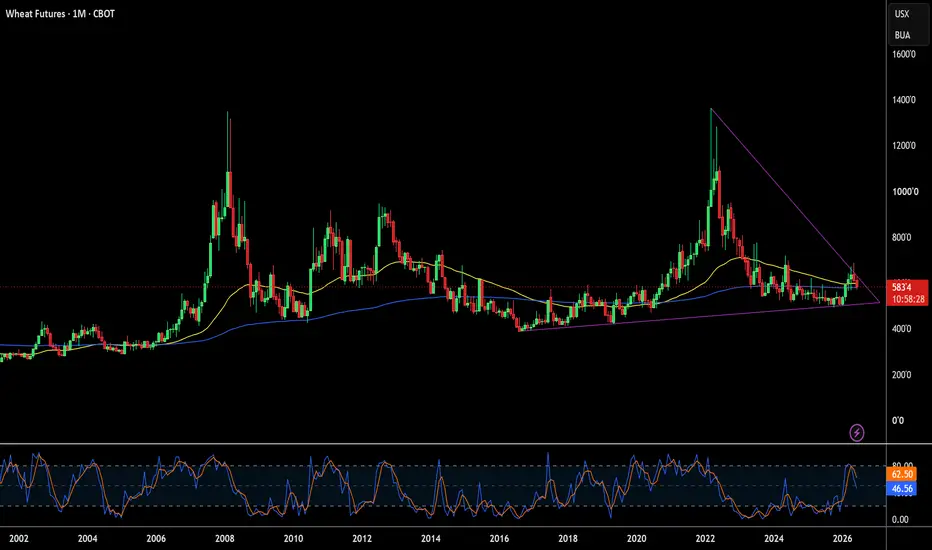
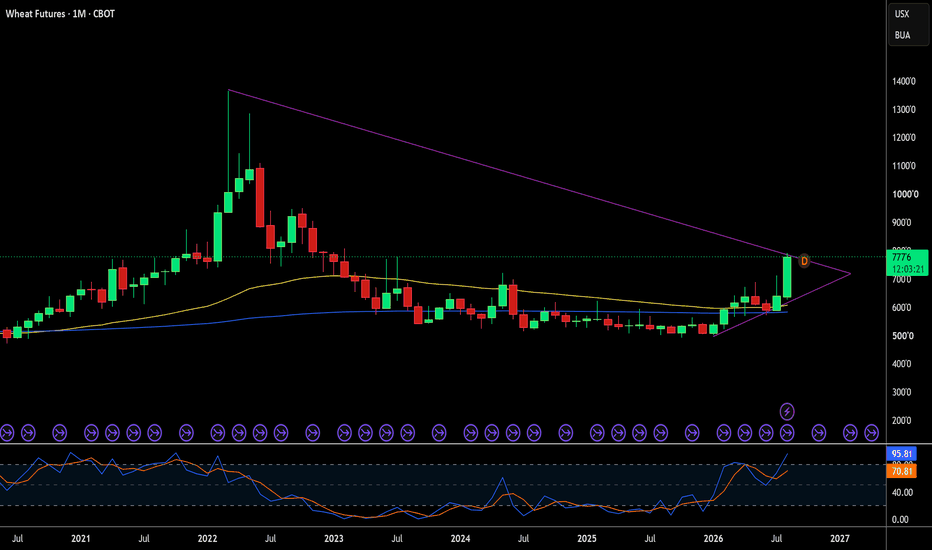
Chicago wheat futures recently surged to three-year highs near $7.70 per bushel. Intensifying warfare in the Black Sea region directly threatens critical grain export terminals. Russia and Ukraine historically supply over twenty-five percent of global wheat exports. Port disruptions force nations across the Middle East and Africa to seek expensive alternative supplies. Macroeconomic food inflation now looms heavily over developing nations facing high import costs. Sovereign food security rapidly becomes a central geopolitical weapon in modern conflict zones.
Importers like Egypt now divert contracts toward European and American grain suppliers. Longer maritime shipping routes sharply elevate freight rates and overall import expenditures worldwide. Governments actively build strategic grain reserves to cushion against prospective supply chain collapses. Geostrategic alliances increasingly dictate international trade agreements and cross-border grain allocation strategies.
Industry Trends, Economics, and Business Models
Commodity trading houses adapt their business models to navigate extreme price volatility continuously. Firms like Cargill, Bunge, and ADM restructure physical supply lines across continents. Surging corn futures exacerbate the rally as feed compounders substitute grain inputs dynamically. Tightening European inventories further compress global supply balances across major export markets. Market participants leverage complex derivative contracts to lock in operational profit margins.
Physical grain cash markets reflect historical premiums over paper derivative contracts today. Regional elevators adjust cash basis levels to incentivize domestic farmer grain movement. High capital requirements force smaller agricultural intermediaries to consolidate under mega-cap conglomerates. Financial institutions structure dynamic hedging portfolios to manage systemic agricultural commodity risks.
High-Tech Innovation, Science, and Patent Analysis
Modern agribusiness relies heavily on artificial intelligence and satellite remote sensing tools. Computational climate models evaluate soil moisture levels and crop condition ratings daily. Scientists pioneer gene-edited wheat varieties to resist severe drought and emerging pathogens. Patent analysis reveals accelerated filings for climate-resilient seed traits globally. Major ag-tech corporations aggressively defend proprietary genetic codes to secure future market dominance.
Autonomous harvesting equipment and field sensors optimize crop yields at minimal operational cost. High-tech biotechnology platforms accelerate the development of stress-tolerant crop varieties rapidly. Precision agriculture tools allow farmers to apply fertilizer with micro-level targeting efficiency. Science continuously redefines global yield potential despite escalating climate challenges.
Cybersecurity, Leadership, and Pharma Parallels
Agricultural supply networks face growing cybersecurity threats from sophisticated nation-state hackers. Digital grain trading platforms and automated port operations represent primary targets for disruption. Corporate leadership mandates stringent cyber defenses to protect critical supply chain data infrastructure. Executive management teams prioritize risk mitigation while maintaining seamless physical logistics operations. Strong leadership aligns operational resilience directly with enterprise risk management goals.
Interestingly, wheat starch plays a vital role within the modern pharmaceutical industry. Drug manufacturers utilize specialized wheat derivatives as essential binders in oral pill production. Supply disruptions in agricultural markets directly impact pharmaceutical manufacturing costs worldwide. Cross-industry dependencies highlight the far-reaching economic consequences of agricultural market shocks.  Long
 Long
 Long

 Long
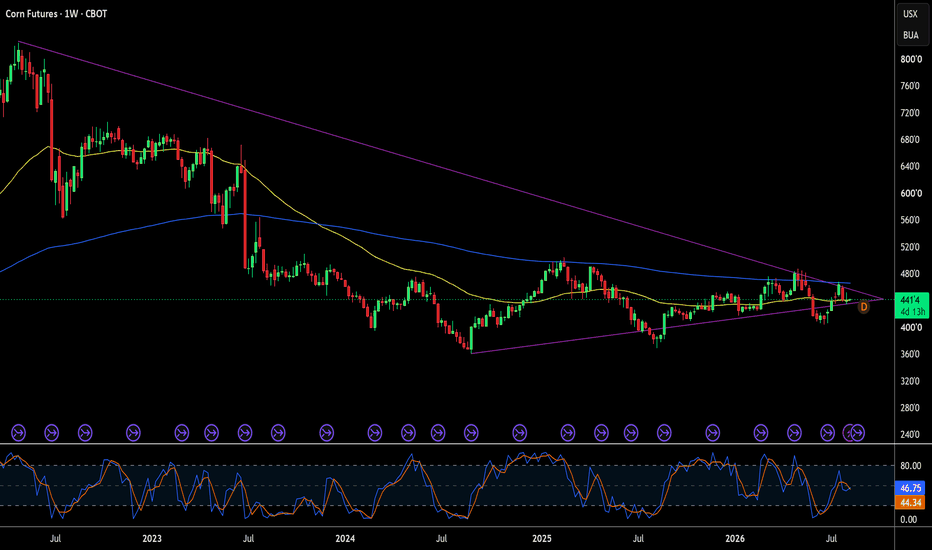
Why Is Corn Soaring in Europe But Not the US?Corn is having two completely different years depending on which side of the Atlantic you trade it. Euronext corn futures in Paris just hit record highs above €250 a ton. Chicago corn, the world's benchmark, sits in a comparatively calm $4.40 to $4.50 a bushel range. Both markets are pricing the same crop. They are pricing two entirely different realities.
Macroeconomics: A Tale of Two Harvests
Europe's story is a supply shock. A historic heat wave, the worst since 1976 by some measures, has cut France's corn crop estimate to roughly 9.4 to 9.5 million metric tons, down about 30% from last year and the smallest French harvest this century. Less than a third of French corn is irrigated, and the heat arrived precisely at pollination, the single most damage-sensitive stage of the crop's development. The European Union's total corn crop forecast has fallen to 52.7 million metric tons, the smallest since 2007.
America's story is almost the opposite. Ahead of the August 12 WASDE report, analysts expect a yield near 182.4 bushels per acre and production close to 15.9 billion bushels, comfortably supplied territory. Export sales are running 23% ahead of last year. That supply cushion is why Chicago corn has stayed range-bound even as oil-linked biofuel demand and renewed Strait of Hormuz tensions have periodically pushed prices higher.
Geopolitics and Geostrategy
The transatlantic price gap is reshaping global trade flows in real time. USDA has raised its 2026-27 EU corn import forecast by 3 million metric tons to 22.5 million tons, approaching the record levels seen during Europe's 2022 drought. Spain has ramped up purchases of US corn directly, widening the arbitrage between Paris and Chicago futures. Ukraine remains a critical swing supplier into the EU and Mediterranean markets, so any disruption to Black Sea export capacity now carries outsized weight for European buyers already short on domestic supply. Meanwhile, renewed tension around the Strait of Hormuz continues to link oil prices to corn through biofuel feedstock demand, a reminder that energy geopolitics and grain markets are no longer separate stories.
Industry Trends and Business Models
Persistent volatility is pushing the industry toward more precise hedging tools. CME Group's newly announced sorghum basis futures contract, designed to hedge the spread between sorghum and corn rather than outright price direction, reflects a broader shift toward localized, targeted risk management. European buyers are responding to their own crisis by locking in coverage earlier and diversifying origin countries, while US exporters are capturing demand that would normally have gone to French and other European suppliers. This is a genuine business model shift: grain trading increasingly rewards flexibility in sourcing over long-term single-origin contracts.
Management and Leadership
Executives at global grain traders like ADM, Bunge, and Cargill are managing a rare moment where their US and European operations face opposite conditions simultaneously. Leadership teams must balance capturing higher-margin European sales against maintaining reliable US export commitments, a genuine test of capital allocation discipline. Firms that diversified their origination footprint across both hemispheres years ago are best positioned to arbitrage the current price gap profitably.
Technology, Science, and High-Tech
Precision agriculture is doing real work on both continents right now, just in opposite directions. In France, remote soil moisture sensing and satellite-based crop stress monitoring are being used to triage which fields are salvageable versus a total loss. In the US, the same technology is confirming the comfortable crop conditions supporting current yield estimates. Drought-tolerant corn genetics, developed through CRISPR gene editing by companies including Bayer and Corteva, are drawing renewed commercial attention as a direct response to Europe's crisis, since the yield gap between irrigated and rainfed corn has never been more financially visible.
Patent Analysis
Patent filings in drought-resistant corn traits and gene-edited seed varieties have been climbing steadily, and Europe's 2026 crop failure is likely to accelerate that trend further. Seed companies that can demonstrate real yield protection under heat and moisture stress, not just laboratory results, gain a commercial advantage that this specific growing season is making unusually easy to quantify and market.
Cybersecurity
Grain markets increasingly run through digital infrastructure, from automated elevator systems to satellite-fed crop monitoring platforms, and that infrastructure is a growing target. A successful attack on export logistics or crop data systems during a supply-constrained year like this one would carry outsized market impact, making cybersecurity investment a genuine operational priority rather than an afterthought for major grain handlers.
The Pharmaceutical Connection
Corn starch remains a genuine, if underappreciated, pharmaceutical input, used as a binder and excipient in tablet manufacturing. Tighter European corn supply and higher prices flow modestly into pharmaceutical production costs on that continent, a small but real example of how a weather event in rural France eventually touches a pharmacy shelf.
Closing Thoughts
Corn's transatlantic split is the real story this season, not a single global price trend. Europe faces a genuine, multi-decade supply shock that is reshaping its import needs and pulling in US and Black Sea grain to fill the gap. The United States, by contrast, is managing a comfortably supplied crop into a WASDE report that could confirm or complicate that calm. Watch three things closely: the August 12 WASDE yield and production numbers, whether France's crop deterioration stabilizes or worsens into harvest, and whether the Paris-Chicago price spread keeps widening or begins to close as US exports fill Europe's shortfall.  Long
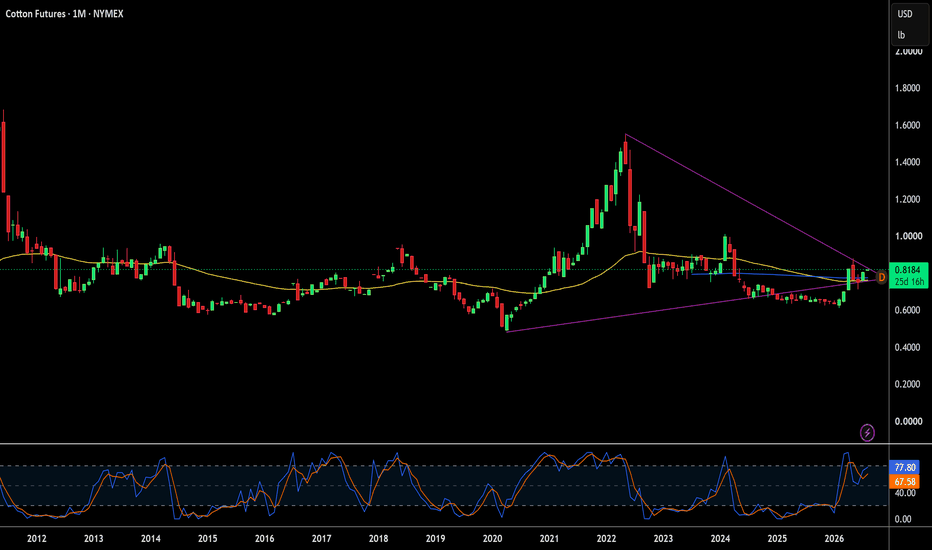
Are Hidden Water Costs Driving Global Cotton Futures?Investors often misunderstand the true volatility of global cotton futures. They typically blame erratic weather patterns or sudden trade tariffs. A new Chatham House study, "The Water Footprints of Global Textiles Trade," points to a deeper catalyst. Every textile carries what researchers call a hidden water footprint, the water embedded in its production, trade, consumption, and eventual disposal. The global textile industry employs roughly 90 million people, more than half of them women. For Bangladesh, Pakistan, India, and Uzbekistan, this industry remains a vital source of jobs and export revenue. But the same water pressures that built these industries now threaten their future growth. Cotton futures increasingly reflect this hidden resource constraint.
Geopolitics and Geostrategy in Agriculture
Water scarcity is reshaping textile trade geopolitics in concrete, measurable ways. Chatham House uses a "baseline water stress" metric, the ratio of total water demand to available renewable supply, to compare exporting and importing nations. China was the largest cotton lint importer in 2024 at 2.6 million tonnes, followed by Bangladesh, Vietnam, Turkey, and Pakistan. Crucially, not all imported cotton carries the same hidden cost. Cotton grown in India, Bangladesh, and East and West Africa relies mostly on rainfed "green water." Cotton from Uzbekistan, the United States, Pakistan, Australia, Egypt, and China relies far more on irrigated "blue water," drawn directly from stressed rivers and aquifers. That distinction means two countries can export the same volume of cotton while imposing very different burdens on scarce freshwater systems.
Macroeconomics and Global Economics
The economic stakes are substantial for the countries most exposed. Bangladesh's apparel sector alone contributed 81.5% of the country's total export earnings in 2024/25. A separate peer-reviewed study found Bangladesh's ready-made garment sector carries a total cotton cultivation water footprint of 25 billion cubic meters, with roughly 91% of that tied to cotton grown abroad and imported as embedded, or "virtual," water. About a third of that footprint relates to water pollution from processing rather than cultivation itself. When a country this economically dependent on textiles imports cotton grown under heavy irrigation stress, its entire export engine inherits a resource risk that does not show up on any conventional balance sheet.
Industry Trends and Innovative Business Models
Chatham House calls for trade policy to incorporate water stewardship and circular economy principles directly, alongside common government standards for measuring textile water footprints. Textile companies are responding by investing in regenerative agriculture, forest conservation, recycling technologies, and better supply chain monitoring. This is a genuine business model shift, not a marketing exercise, since buyers are increasingly asking suppliers to document water sourcing, not just final product cost. Firms that can prove their cotton draws on rainfed rather than irrigated sources may gain a real, defensible advantage as water stewardship becomes a procurement criterion rather than an afterthought.
Management Leadership and Corporate Culture
Chatham House frames the challenge as demanding "a whole-of-value-chain approach, and collective commitment to more sustainable and circular practices." That requires management attention extending well beyond a company's own factory floor, back into cotton fields in countries the company may never directly visit. Executive teams that map their water exposure by sourcing country, distinguishing green-water suppliers from blue-water ones, gain a genuine risk management edge unavailable to competitors still treating cotton as an undifferentiated commodity.
Technology Science and High Tech Solutions
Precision agriculture and remote monitoring are becoming essential tools for managing this exposure. Farmers deploy soil moisture sensors and satellite imagery to track water use against crop yield in real time. This data increasingly feeds directly into the kind of water footprint accounting Chatham House is calling for, giving traders and manufacturers visibility into a variable that was previously invisible in standard commodity pricing.
Cybersecurity and Patent Analysis Edge
As water footprint data becomes commercially material, protecting it becomes a genuine cybersecurity concern, not just an agricultural one. Patent activity in drought-resistant and lower-water cotton varieties continues to grow, and companies that can document verifiably lower water footprints stand to capture a real pricing premium as buyers factor sustainability into sourcing decisions.
The Critical Pharmaceutical Industry Connection
Medical-grade cotton and cellulose remain essential inputs for wound care and certain drug delivery systems. Since cotton's water footprint is concentrated overwhelmingly in cultivation rather than processing, per the 91% figure from the Bangladesh study, pharmaceutical supply chains sourcing raw cotton inherit the same underlying water exposure as the broader textile industry, even though the end use is medical rather than apparel.
 Long
Are Soybean Futures the Ultimate Climate Hedge?Weather Volatility and Market Swings
Soybean futures markets are experiencing severe price volatility in mid-2026. Sizzling Midwest heatwaves routinely stoke fear across Chicago Board of Trade trading desks. November soybean contracts recently hit two-year highs near $12.50 per bushel. However, shifting rain forecasts quickly trigger sharp sell-offs across agricultural markets. Speculative funds aggressively manage net long positions in response to weekly crop reports. Crucially, crude oil price movements spill directly into soy oil and biodiesel markets. Farmers and institutional traders must navigate these sudden price swings daily.
Geopolitics, Geostrategy, and Macroeconomics
Soybeans represent a crucial geopolitical weapon in global trade strategy. The United States and China continuously negotiate massive soybean purchasing agreements. Brazilian and Argentine agricultural exports compete directly with American grain shipments. Meanwhile, macroeconomic shifts in inflation and currency valuations dictate international export competitiveness. Global energy policy also drives commodity demand. Expanding federal mandates for renewable diesel link agricultural commodities to global energy security. Consequently, soybean futures serve as a key barometer for international economic health.
Technology, High-Tech Science, and Patent Moats
AgTech innovation fundamentally alters modern soybean yield potential. Biotechnology giants hold vast patent portfolios covering CRISPR gene-editing tools. Companies like Bayer, Corteva, and Inari develop advanced seed varieties. These high-tech seeds resist extreme drought, pests, and synthetic herbicides. Gene-edited traits allow crops to thrive despite severe environmental stress. Modern farmers utilize precision agriculture tools to optimize fertilizer and water usage. Patent protection secures massive profit margins for agricultural technology leaders.
Business Models and Leadership Execution
Major grain traders like ADM, Bunge, and Cargill dominate global distribution. These agribusiness giants execute integrated business models across processing and logistics. Management teams focus on maximizing crush margins between raw beans and refined meal. Corporate leadership must hedge complex supply chain risks during extreme weather events. Companies invest heavily in biofuel refining infrastructure to capture clean energy subsidies. Agile supply chain execution separates industry leaders from struggling competitors.
Cybersecurity, Pharmaceuticals, and Modern Science
The soybean ecosystem extends far beyond traditional food and animal feed. Soybean-derived lecithin provides critical lipid nanoparticles for pharmaceutical drug delivery systems. mRNA vaccines and advanced therapeutics rely on these bio-based chemical compounds. High-tech pharmaceutical research depends on consistent, high-purity soy derivatives. Furthermore, automated grain elevators and smart farming systems face growing cybersecurity threats. Ransomware attacks on agricultural logistics can freeze global food supplies instantly. Modern agribusiness must fortify digital infrastructure to ensure food security.  Long

Why Smart Capital Is Betting Big on Lean HogsLean Hog futures on the CME recently surged to fresh multi-month highs. Investors increasingly view swine markets as an essential macro asset class. Beef prices face extreme inflation and shrinking cattle herds. Consequently, institutional traders now pivot aggressively toward lean hogs. Swine production offers faster biological cycles and lower consumer costs. The Chicago Mercantile Exchange cash-settled index reflects strong wholesale demand. Meanwhile, lower corn feed costs boost producer profit margins. Lean hogs now anchor agricultural portfolio strategies.
Geopolitics and Foreign Trade Strategies
Global food security drives modern geopolitical alliances and trade policies. Pork remains the most consumed land-based animal protein worldwide. China heavily influences global prices through strategic pork reserve adjustments. American producers mitigate export tariffs through diversified trade agreements across Latin America. Nearshoring supply chains protects pork exports from Pacific shipping vulnerabilities. Furthermore, trade negotiators use pork quotas as leverage in diplomatic talks. Securing protein trade routes directly shields nations from domestic food inflation.
Macroeconomics, Feed Economics, and Market Trends
Macroeconomic pressures heavily shape protein consumption across global markets. Elevated interest rates continue to strain consumer purchasing power. Consumers naturally trade down from expensive beef cuts to affordable pork options. Simultaneously, falling corn and soybean meal prices lower feeding costs. Iowa State University data highlights rebounding profit margins for farrow-to-finish operations. Commodity funds actively rebalance portfolios to capture this widening spread. Lean hog futures provide an ideal hedge against broader commodity inflation.
High-Tech Science, CRISPR, and Patent Analysis
Agricultural science is rapidly revolutionizing livestock biology and production efficiency. CRISPR gene-editing technology now produces pigs immune to devastating viral diseases. Companies aggressively file patents on disease-resistant swine genetics and reproductive traits. These biological innovations drastically lower mortality rates and reduce antibiotic usage. Patent analytics show massive growth in automated livestock monitoring technologies. Genetic sequencing allows breeders to select optimal lean muscle yields. High-tech biology directly transforms raw commodity assets into high-margin intellectual property.
Pharmaceutical Breakthroughs and Xenotransplantation
The swine industry uniquely bridges agricultural production and advanced medical science. Swine intestinal tissues provide the primary global supply of heparin blood thinners. Furthermore, biotech companies utilize gene-edited pigs for groundbreaking human xenotransplantation. Transplants of engineered pig hearts and kidneys now enter clinical human trials. These medical breakthroughs create high-value secondary markets for specialized hog herds. Consequently, pharmaceutical demand decouples swine valuation from basic food supply cycles.
Precision AgTech and Industrial Cybersecurity
Modern swine production relies heavily on connected IoT infrastructure and smart automation. Sensor networks continuously monitor barn temperatures, water intake, and animal health. Biometric thermal cameras instantly flag early infection signs across thousands of animals. However, hyper-connected mega-farms introduce severe cybersecurity risks from malicious cyber actors. Processing plants deploy advanced encryption to protect automated slaughtering lines from ransomware attacks. Securing digital infrastructure maintains uninterrupted pork processing and safeguards operational continuity.
Leadership, Business Models, and Corporate Culture
Agribusiness leaders are completely revamping traditional contract farming models. Modern management cultures emphasize rapid digital transformation and strict biosecurity protocols. Major pork processors vertically integrate feed mills, genetics, and meat packing facilities. Executives use CME futures contracts to lock in profit margins months in advance. Sustainable corporate cultures focus on carbon footprint reduction and waste-to-energy biogas capture. Assertive leadership transforms legacy livestock management into a sophisticated, technology-driven asset class.  Long

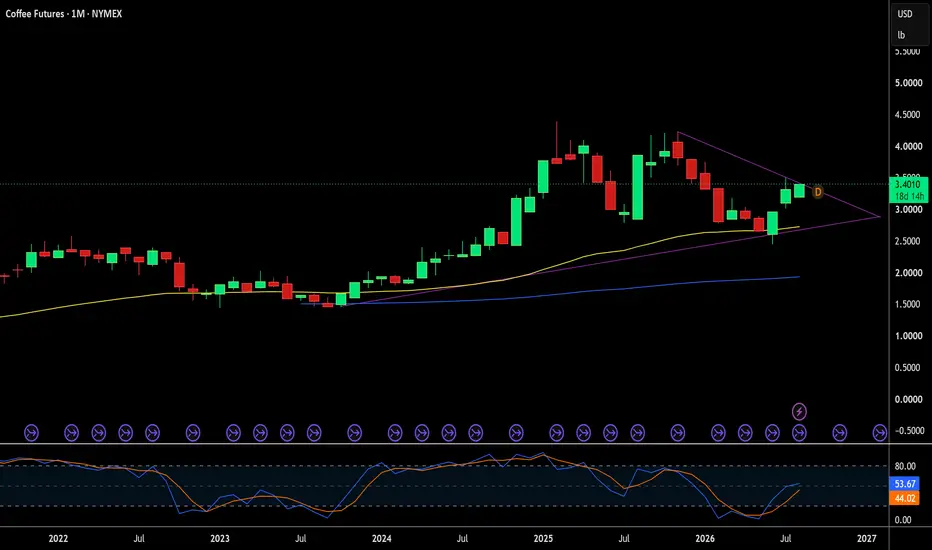
Awakening Liquid Gold: The Coffee Futures BoomInvestors face a volatile landscape in 2026. ICE Arabica coffee futures exploded higher this month. Prices rallied nearly 50 percent after finding a bottom in June. Supply chain issues and delayed harvests drive this momentum. Heavy rains disrupted fieldwork in Brazil. This weather crisis degrades crop quality and restricts output. Traders monitor these developments closely. We must analyze the catalysts propelling coffee prices across multiple sectors.
Macroeconomics and Economics
Macroeconomic forces heavily influence coffee futures today. The Brazilian Real recently surged against the US dollar. This currency strength discourages Brazilian farmers from exporting their beans. They hold inventory, waiting for better margins. Global demand increases simultaneously. Intercontinental Exchange (ICE) raised margin requirements twice recently. This action drained liquidity from the market. Commodity funds then closed positions rapidly, worsening price volatility. Supply shortages establish a bullish foundation.
Geopolitics and Geostrategy
Trade policies directly shape the global coffee trade. Governments implement new tariffs and export restrictions. Supply chain bottlenecks complicate physical deliveries worldwide. Brazil remains the dominant producer, controlling 37 percent of global output. Vietnam follows as the primary robusta supplier. Geopolitical tensions impact major shipping routes. This disruption forces shipping companies to reroute vessels. Traders must factor these geopolitical risks into their pricing models.
Science and Industry Trends
El Niño creates severe weather anomalies across South America. Heavy rains delay the Brazilian harvest, which currently sits at only 52 percent completion. Agronomists rush to address these climate challenges. Science plays a vital role here. Researchers study the impact of extreme moisture on bean development. Industry trends show a definitive shift toward climate-resilient farming. Farmers adopt advanced cultivation techniques to salvage their yields.
Technology, High-Tech, and Patent Analysis
Technology revolutionizes coffee production and trading. AI algorithms now predict weather patterns and yield fluctuations accurately. High-tech sensors monitor soil moisture and plant health in real time. Innovators file numerous patents for advanced agricultural tech. Patent analysis reveals a spike in drought-resistant seed technologies. Companies also patent novel extraction methods for specialty coffees. This technological arms race gives progressive farms a competitive edge.
Cybersecurity
Digital platforms process millions of commodity trades daily. Cybercriminals target these financial exchanges relentlessly. Cybersecurity protocols must protect sensitive trading data and supply chain logistics. A single breach could manipulate futures pricing or disrupt global distribution. Firms invest heavily in encrypted networks. They deploy zero-trust architectures to secure their commodity trading operations. Constant vigilance prevents catastrophic market manipulation.
Company Culture, Innovation, and Business Models
Coffee companies must foster a culture of ultimate agility. Rigid organizations fail during intense market volatility. Leaders encourage rapid innovation to offset rising bean costs. Businesses adopt dynamic pricing models to maintain profit margins. Some roasters pivot to direct-trade business models. This strategy bypasses intermediaries and secures supply lines. Hedging against volatile futures requires a forward-thinking corporate mindset.
Management and Leadership
Executives face immense pressure from volatile coffee markets. Leaders must execute precise risk management strategies. They utilize complex financial instruments to hedge against future price spikes. Managers optimize supply chains to reduce unnecessary costs. Strong leadership ensures stability during market chaos. Decision-makers must remain proactive rather than reactive. Effective leaders turn these market disruptions into strategic advantages.
The Pharmaceutical Industry Connection
Pharmaceutical companies watch coffee futures closely. Coffee beans contain valuable bioactive compounds and antioxidants. Manufacturers extract high-grade caffeine for medicinal formulations. Scientists study chlorogenic acid for its metabolic benefits. Rising raw material costs squeeze pharmaceutical profit margins. Drug companies must secure their supply of these crucial organic compounds. This cross-industry reliance highlights the broad economic impact of coffee.
Conclusion
Coffee futures represent far more than a morning beverage. They reflect a complex matrix of global forces. Climate change, currency fluctuations, and technology drive this dynamic market. Investors must understand these diverse catalysts. Astute traders will capitalize on these violent price swings. We expect continued volatility as weather patterns remain unpredictable. The liquid gold rush presents unique opportunities for prepared minds. Long 
Why Is the Global Wheat Market Surging?Wheat futures are experiencing a violent upward rally today. The recent July WASDE report triggered panic buying across commodity desks. Global wheat production is officially falling below total consumption. Russia just reinstated its controversial wheat export tax. Meanwhile, maritime drone strikes continue to choke vital Black Sea transit routes. Investors must look beyond the surface of this massive agricultural shockwave. Let us dissect the multi-layered drivers reshaping global wheat markets today.
Geopolitics and Geostrategy
Food security remains the ultimate weapon of modern geopolitical statecraft. Ukraine recently deployed sophisticated maritime drones near major Russian grain straits. This strategic move instantly choked vessel traffic and panicked global shipping lines. Concurrently, Russia weaponized its market dominance by reinstating floating export taxes. By artificially elevating international prices, Moscow controls the global low-cost food supply. Meanwhile, China actively hoards domestic stockpiles while restricting Western grain inflows. These aggressive geostrategic moves establish agricultural control as a core pillar of modern warfare.
Macroeconomics and Economics
The latest USDA reports fundamentally shattered previous bearish market assumptions. Forecasters slashed U.S. new-crop wheat ending stocks down to 722 million bushels. Globally, the agency projects total wheat production at 820 million tonnes. This tight supply faces an expanding global demand of 824.5 million tonnes. Structural deficits naturally fuel massive speculative capital inflows from hedge funds. This supply-demand mismatch guarantees persistent inflationary pressures across developing nations. Consequently, central banks face prolonged food-driven inflation threats well into next year.
Industry Trends and Business Mode ls
Agricultural supply chains are completely overhauling their traditional logistics models. Global agribusinesses are abandoning just-in-time inventory strategies entirely. Instead, they embrace heavy regional storage and localized sourcing networks. Modern grain trading desks utilize dynamic hedging models to neutralize severe price volatility. Agribusiness companies must adapt their business models to survive sudden export tax shocks. Firms that fail to secure diverse alternative origins face swift financial ruin. Resilience now takes absolute priority over short-term cost minimization.
Management, Leadership, and Culture
Navigating volatile commodity spikes requires highly decentralized corporate leadership. Rigid, slow-moving agricultural conglomerates fail instantly during fast-moving supply shocks. Forward-thinking executives actively foster agile, data-driven corporate cultures across trading teams. Leaders must empower regional managers to make immediate procurement decisions. Bureaucratic delays during a shipping crisis can cost trading firms millions. Progressive organizational culture values rapid adaptability over traditional, top-down hierarchy. Decisive leadership ultimately separates thriving market leaders from bankrupt laggards.
Technology and Cybersecurity
The global grain trade operates almost entirely on highly interconnected digital trading platforms. Automated electronic supply chains manage millions of tons of wheat transactions daily. This massive digital footprint creates an enticing target for state-sponsored cybercriminals. Rogue actors aggressively deploy ransomware against grain elevators and port control systems. A successful cyber attack on critical food logistics can paralyze regional supply chains instantly. Therefore, global agribusinesses must dramatically scale up their cybersecurity spending. Digital defense secures physical food survival.
Science, High-Tech, and Patent Analysis
Severe climate volatility forces agricultural science to accelerate rapidly. High-tech laboratories utilize gene-editing tools like CRISPR to engineer drought-resistant wheat varieties. Agro-tech corporations aggressively file patents for climate-resilient seed phenotypes. Patent analysis reveals a massive corporate arms race targeting heat-tolerant crop genomes. Furthermore, satellite imaging and machine learning algorithms predict crop yields with unprecedented precision. These scientific innovations shield multinational producers from catastrophic weather anomalies. Intellectual property in agriculture directly dictates future market dominance.
The Pharmaceutical Industry Connection
The pharmaceutical sector maintains a quiet but deep connection to global wheat markets. Modern drug manufacturers rely heavily on high-purity wheat starch as a primary binding excipient. Pharmaceutical factories process vast amounts of wheat derivatives to produce daily tablets and capsules. Additionally, medical research increasingly isolates specific wheat proteins for targeted immunotherapy applications. A prolonged global wheat shortage directly spikes production costs for essential medications. Therefore, major healthcare conglomerates closely monitor wheat futures to protect their manufacturing supply chains. Long 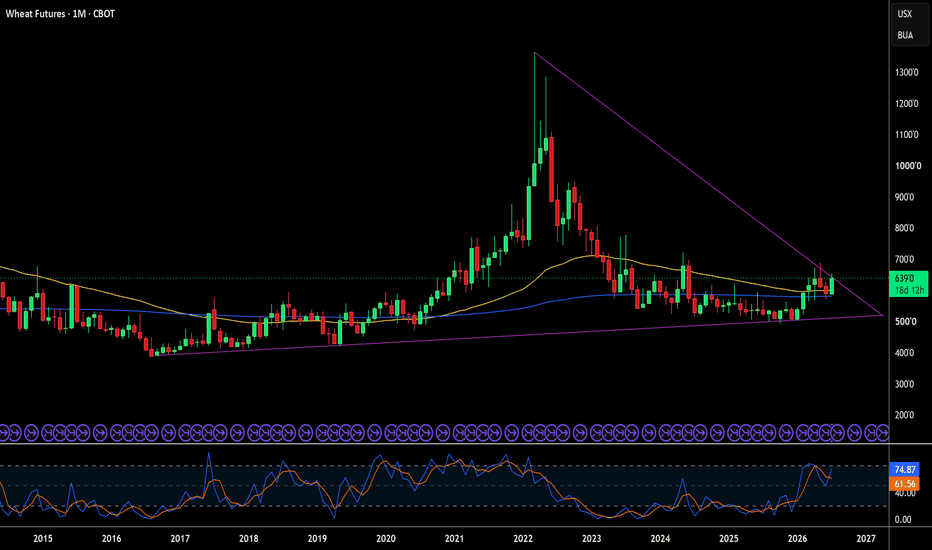
 Long
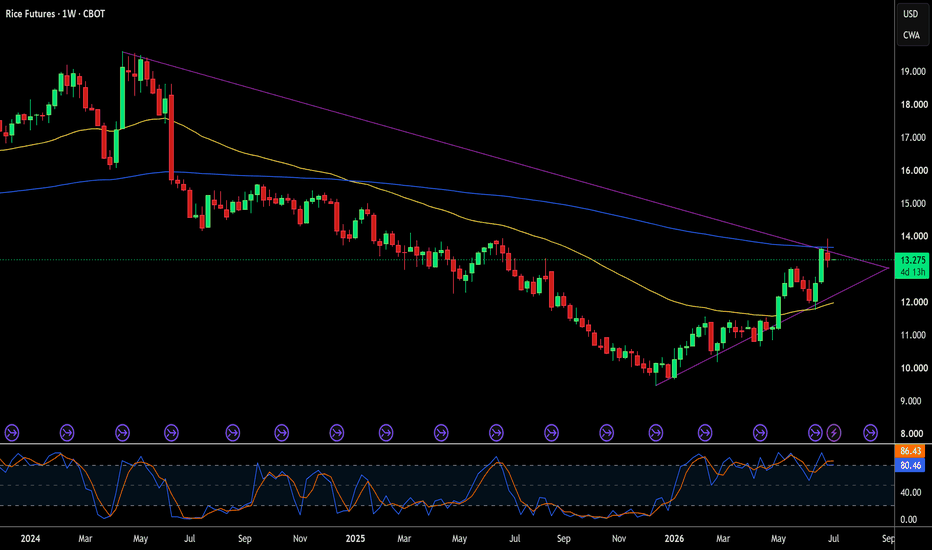
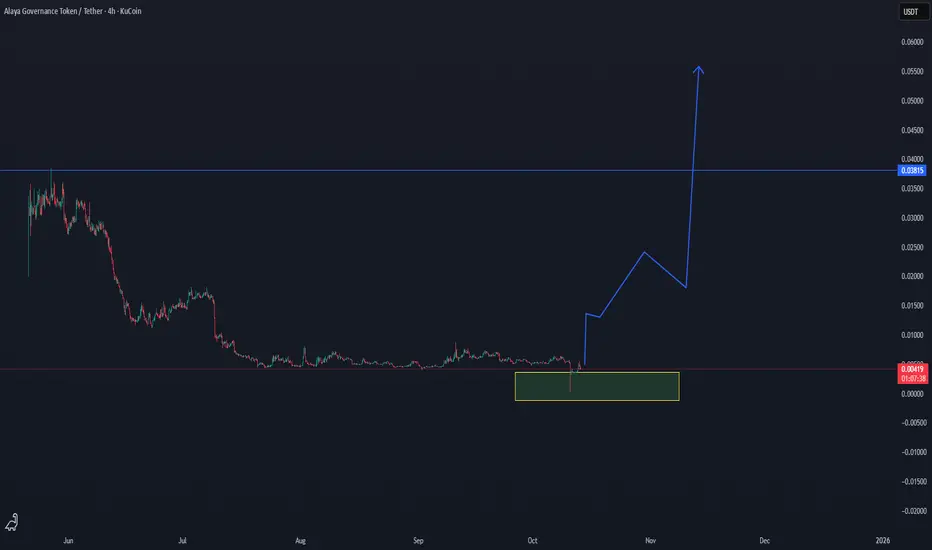
DMTR: $6.61 With Nothing vs $0.0052 With EverythingBeen watching BBG:DMTR quietly for a while. Decided to put the macro picture together properly.
First, the chart. Then I'll show you what's actually happening on the ground.
November 2021. ATH of $6.61. Dimitra had a whitepaper and a vision. EUDR wasn't even law yet — just an EC proposal. No government contracts. No mandates. The market gave it a peak valuation anyway.
Then the bear market hit. And it never came back.
Here's what changed while the price didn't:
EUDR entered legal force June 2023. Uganda government approved Dimitra as one of 5 national EUDR traceability providers — 2 million coffee farmers. PT Surveyor Indonesia — 3 million farmer programme. India OBC government contract — 1.3 million farms. Ethiopia 1.2 million smallholders across 12 cooperatives. Saudi Arabia, Honduras, Peru, Kenya, Nepal, Mexico. 4.8 million farms. 45+ countries. 6 continents.
184 days to enforcement. EU law. Not a roadmap item.
Pull up the technicals on this and it says Sell. 13 sell signals, 2 buy, on both oscillators and moving averages. I'm not going to argue with that — the chart is the chart.
But technicals measure what price has done. They don't measure what's been built while nobody was looking. Government mandates. A live compliance protocol. 4.8 million farms onboarded todate. Technicals say sell. Fundamentals say something else. That gap is the whole thesis.
Price compressing in a tight accumulation channel since mid-2022. Volume $152K in the last 24h on a $2.54M market cap. Only 155 people across all social media discussing this right now.
Been in crypto since 2016. Seen a few cycles. This one feels different.
Maybe I'm wrong. Liquidity is thin. Token is tiny. Regulatory catalysts don't always move prices the way logic says they should.
But 1,204x between current price and the ATH — reached when none of this existed — is an asymmetry worth sitting with.
I hold $DMTR. Not financial advice. Data: CoinMarketCap/TradingView, 1 July 2026.
#DMTR #EUDR #RWA #AgTech #crypt  Long

Who Controls Wheat: Weather Scares or Supply?Wheat is caught between opposing forces, and right now the bearish side is winning. A record-breaking European heatwave pushed French milling wheat to a three-month high near €211 a tonne, its strongest since mid-March, on fears of crop stress in the EU's largest producer. Yet the global benchmark is falling. CBOT wheat dropped below $5.80, its lowest since April 10, as the US winter-wheat harvest races ahead at 49% complete versus 11% a year ago. Ample supply is overpowering the weather scare.
The reason is comfortable global inventories. Record stocks and strong Black Sea production have left the market largely desensitized to bullish headlines, from the European heat to a developing El Niño to renewed Russia-Ukraine strikes. Russian wheat remains the world's price-setter, and major buyers like Egypt and Turkey are importing less as their own harvests improve. Even Kazakhstan's new six-month ban on most wheat imports, aimed at cheap Russian grain, is a localized protectionist signal rather than a global price driver. When inventories are full, weather and politics struggle to move the needle.
That said, the bullish risks are real, just not yet decisive. The European heat is genuine, but with the crop largely past flowering, the damage skews toward quality and test weights more than outright production, and corn is the more vulnerable victim. The bigger danger is cumulative. A 2003-style EU yield loss of roughly 9% to 10%, if it materialized, would tighten world stocks-to-use toward levels not seen since 2013. And a developing El Niño threatens the 2026/27 crop, which is why some analysts see the next meaningful rally arriving in 2027 rather than now.
The honest read is that the well-supplied exporters, not the weather headlines, control the breadbasket today. Near-term, the fast US harvest, record global stocks, and dominant Black Sea supply keep prices pressured, even as Europe bakes and nations hoard grain. The bullish case is a story for later. If the European heat cuts deeper than feared, or if El Niño damages the next crop, the market's current complacency could reverse sharply. For traders, the signals to watch are EU yield confirmations from FranceAgriMer, the pace of the US harvest, and Black Sea export flows. For now, ample supply wins, and the rally waits. Short 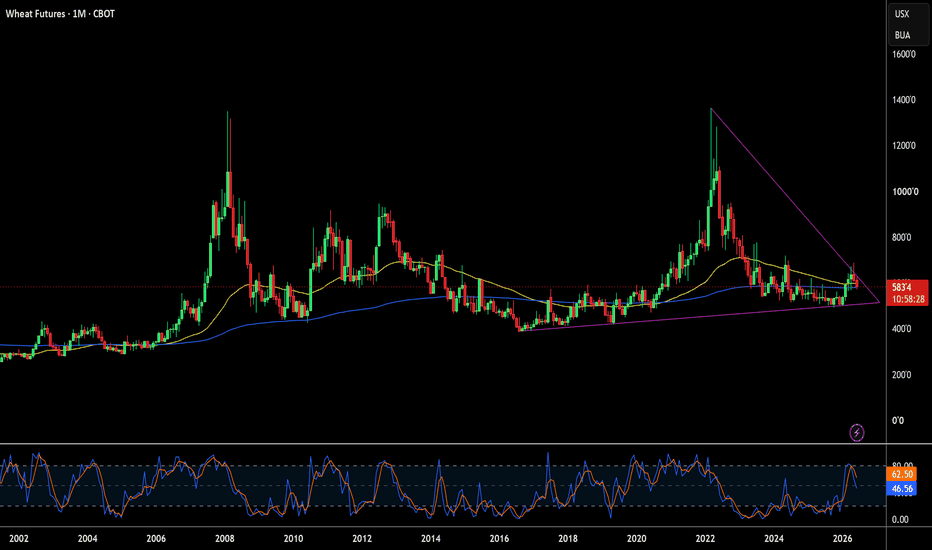
Will the Next Harvest Decide the Cocoa Market?Cocoa's story over the past two years is a violent round trip. Three consecutive West African deficits, the worst supply shortfall in more than 60 years, drove futures to a record near $12,900 a ton in December 2024. Then the market flipped. Better West African weather lifted production into back-to-back surpluses, while two years of record prices destroyed demand. Futures crashed more than 60% to near $2,850 in early 2026, before rebounding to roughly $4,300 by mid-June on weak next-crop signals and heavy speculative short-covering. Cocoa now sits far below its peak but is anything but settled, with realized volatility running near 63%.
That leaves a genuinely two-sided market. On the bearish side, supply has recovered, with StoneX projecting surpluses of about 247,000 tons in 2025/26 and 149,000 tons in 2026/27, and demand destruction has proven real and lasting, with grindings down roughly 6.7% across Europe, North America, and Asia. On the bullish side, early readings of the 2026/27 West African crop are weak, showing below-average cherelle counts, dry soils, and El Niño risk. The October main harvest is the swing factor: a normal crop points back toward $3,200, a disappointing one toward $5,800.
Two structural forces sit beneath the price. First, the EU Deforestation Regulation, with large-operator compliance due in December 2026, is bifurcating the market. Certified, traceable beans command a premium, while non-certified West African volumes risk exclusion from European buyers. Second, retail chocolate prices have stayed stubbornly high even as futures collapsed, because manufacturers hedge and buy months ahead and rarely reverse price increases once made. That asymmetry, cheaper beans but not cheaper bars, is a textbook case of sticky consumer inflation.
The honest read is a two-sided, harvest-driven market rather than a clean directional bet. Demand destruction and surplus supply cap the upside, while weak next-crop signals and El Niño risk cap the downside, leaving a wide but bounded range around the mid-$4,000s. For traders, the October West African harvest and the pace of demand recovery are the variables that matter. For chocolate makers, EUDR compliance and sticky retail pricing define the margin picture. Watch the crop and the grindings data rather than the geopolitical headlines. The contest over cocoa is really supply recovery and demand destruction fighting next-crop risk, and the next harvest casts the deciding vote. Long 
Screwworm or Supply Cycle: What's Driving Cattle?The cattle market sits at record highs because of a historic supply squeeze, and the screwworm is amplifying that story rather than creating it. US herd inventory has fallen to a 75-year low, beef cow numbers are down about 285,000 head, feedlot placements dropped roughly 9.7% in May, and weekly slaughter is running 22,000 to 32,000 head below last year. Set against beef demand near a 40-year high, that scarcity has pushed fed cattle toward $250 per hundredweight and feeder cattle to roughly $375. This is the dominant force in the market.
Onto that tight backdrop, the New World screwworm adds a fresh and escalating supply threat. The pest already closed the Mexican border to feeder-cattle imports, a key driver of 2025's record prices, and now the first US detections since the pest's 1966 eradication have appeared. Officials have confirmed 19 cases across Texas and New Mexico since June 3, with Terrell County emerging as a focal point. Texas has imposed animal-movement quarantines across more than a dozen counties, while the USDA releases tens of millions of sterile flies each week. Because the fly's roughly 21-day life cycle means containment takes several reproductive cycles, this risk will not resolve quickly.
For prices, the screwworm is bullish at the margin. Any domestic quarantine that strands cattle, or any further squeeze on Mexican imports, tightens a supply that is already historically thin. But the market is showing late-cycle fatigue, with the August live cattle contract repeatedly failing at $250 resistance even as cash trades higher. The strain is acute downstream, where packer margins are running roughly $300 to $330 per head in the red, forcing the slaughter cuts that tighten beef supply further. The screwworm, in other words, is an accelerant on an already late-cycle market, not the origin of the move.
The honest read is that the outbreak is a genuine, watch-closely risk that amplifies a supply story already in control of the market. The upside catalysts, the outbreak's spread and the status of the Mexican border, sit alongside clear late-cycle warning signs: record prices, deeply negative packer margins, and repeated failure at technical resistance. That combination points to higher volatility rather than a clean one-way bet. Producers with cattle to sell hold strong leverage, while buyers and packers face a margin vise. Watch the outbreak's geography and the border closely, but remember the market was priced for scarcity well before the first fly crossed the line.  Long

What Is the Bean-Corn Ratio Signaling for 2026?The soybean-to-corn price ratio, November beans divided by December corn, is the row-crop producer's planting compass. A reading below about 2.4 signals that corn pays better per acre, while a reading above 2.6 tilts the math toward soybeans. For 2026, the ratio sits near 2.40, essentially neutral and just below its long-run average of 2.45, giving no clear edge to either crop. That is a meaningful change from 2025, when a low ratio favored corn and helped drive a near-record 95 million corn acres.
With the signal neutral, acreage is drifting modestly back toward soybeans rather than swinging hard in either direction. USDA projects 2026 corn plantings down about 3.7 million acres to roughly 94 million, and soybeans up nearly 4 million to around 85 million, as new-crop corn prices fail to compete on profitability. So the shift the ratio is driving this year is a mild rotation, not the dramatic reallocation the headline numbers might suggest.
The bigger story for corn is margin pressure. The 2026/27 season-average price is forecast near $4.20 a bushel, below the roughly $5 break-even, leaving many growers underwater even after input costs eased from their peaks. Record 2025 production left heavy carryover stocks, and although 2026/27 output is projected down about 7% to 15.8 billion bushels, ample supply still caps the upside. The forces that could actually lift prices sit on the demand side: ethanol policy and the push for E15, export pace and Chinese buying, and the outcome of USMCA negotiations.
The honest read is that the bean-corn ratio matters, but in 2026 it is sending a quiet signal rather than breaking markets. Near 2.40, it is nudging acreage toward soybeans without forcing a dramatic swing, and corn's real problem is structural: prices below break-even, large stocks, and demand that needs a catalyst. For investors, corn this year is a range-bound, demand-and-weather story. Watch the ratio for the 2027 planting tilt, but watch ethanol policy, export pace, and summer weather for what actually moves the price between now and harvest. Long 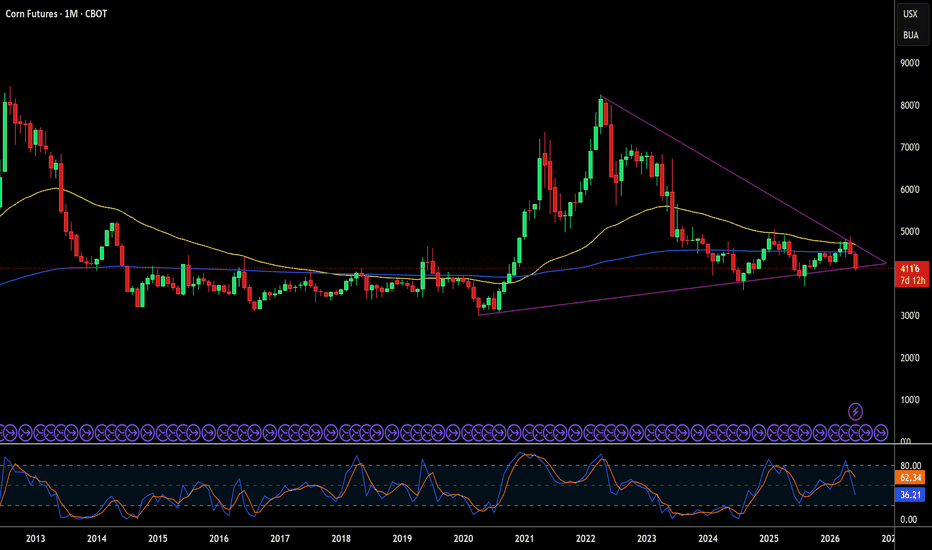
 Long

Why the Sudden Surge in Soybean Oil Prices?Recent sharp increases in Chicago soybean oil prices reflect a confluence of dynamic global and domestic factors. Geopolitical tensions, particularly those impacting crude oil markets, have played a significant role, as evidenced by the recent surge in Brent crude futures following events in the Middle East. This volatility in the broader energy complex directly influences the cost and strategic value of alternative fuels, positioning soybean oil at the forefront of this market shift.
A primary driver of this ascent is the transformative policy initiatives from the U.S. Environmental Protection Agency (EPA). The EPA's proposed Renewable Fuel Standard (RFS) volume requirements for 2026 and 2027 represent an aggressive push towards increased domestic biofuel production. These mandates, significantly exceeding previous targets, aim to bolster U.S. energy security and provide substantial support for American agriculture by boosting demand for soybeans and their derivatives. Key changes, such as the transition to RIN equivalents and reduced RIN costs for imports, are designed to further incentivize domestic consumption and reshape market dynamics.
This policy-driven demand fundamentally reorients the U.S. soybean oil market, causing Chicago Board of Trade futures to increasingly reflect internal American forces rather than global trends. This necessitates a shift in focus for traders towards physical market prices in other regions for international insights. The market has reacted swiftly, with notable increases in futures prices, a surge in open interest, and record trading volumes, indicating strong investor confidence in soybean oil's role within this evolving landscape. Concurrently, the new mandates exert pressure on imported biofuel feedstocks, further solidifying the emphasis on domestic supply.
Ultimately, the rise of soybean oil prices signifies more than just market speculation; it marks a pivotal transformation. It positions soybean oil as an essential commodity within the U.S.'s energy independence strategy, where robust domestic demand, shaped by forward-looking policy, becomes the prevailing force. This transition underscores how intertwined agricultural markets now are with national energy objectives and global geopolitical stability.  Long