Long
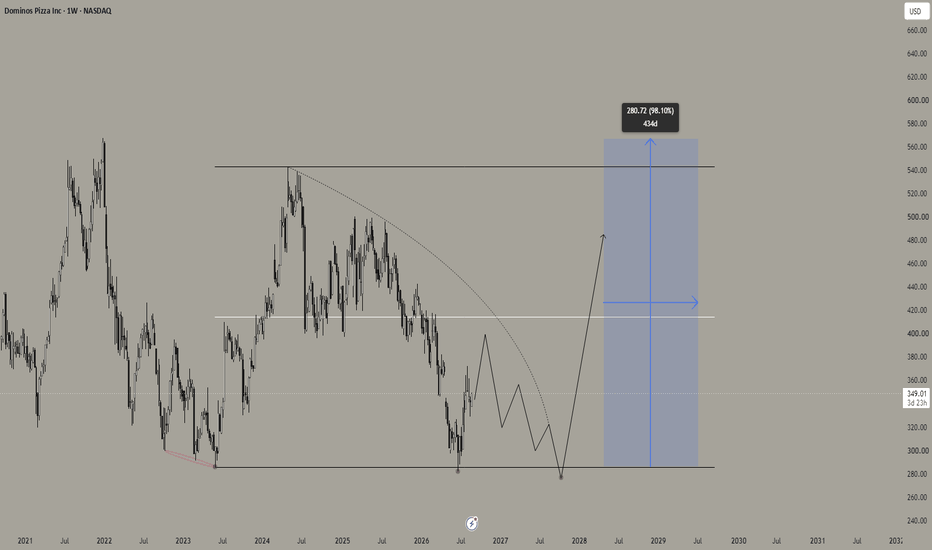
Short 
DPZ Domino's Pizza remains the undisputed global leader.**💡 DPZ (Domino's Pizza) — Strong Buy: Q4 Earnings on Feb 23 Set to Reveal Consumer Resilience & Digital Moat Strength 🚀**
**SECTION 1 — Executive Summary** 💼
Domino's Pizza remains the undisputed global leader in pizza delivery with unmatched digital ordering infrastructure and a proven franchise model that delivers consistent same-store growth even in choppy consumer environments. With Q4 results due Monday Feb 23 before the open, investors are positioned for a read on 2026 consumer spending trends and international acceleration that could re-rate the stock higher.
**Overall rating: Strong Buy**
**12-month price target: $480** (blended 60% DCF + 40% comps multiple; methodology detailed in Valuation section)
**Single biggest reason to own:** Industry-leading digital platform (app + tracking) drives 70%+ of sales and creates sticky repeat revenue in a $220B+ global pizza TAM.
**Single biggest risk:** Rising commodity and labor costs squeezing franchisee margins if not offset by pricing power or efficiency gains.
**SECTION 2 — Business Overview** 🏢
Domino's Pizza is the world's largest pizza company by global retail sales, operating a network of approximately 21,000 stores in 90+ markets. It delivers pizza, wings, pasta, and desserts primarily through carryout and delivery.
**Revenue breakdown (latest TTM as of Sep 2025):**
- U.S. Company-owned stores & supply chain: ~55%
- U.S. franchise royalties & fees: ~25%
- International (franchise royalties + supply chain): ~20%
(Source: Yahoo Finance key statistics, Feb 19 2026 data)
**Business model:** 95%+ franchise-operated stores generate high-margin royalty income (typically 5.5% of sales) plus supply-chain distribution profits. Digital orders (via Domino's app and website) now represent the majority of sales, driving repeat business through loyalty programs and AI-powered personalization.
**Competitive moat:** Vertically integrated supply chain (dough, cheese, toppings produced in-house or controlled), proprietary ordering technology with real-time GPS tracking, and 65+ years of brand equity make replication extremely difficult for new entrants.
**SECTION 3 — Financial Deep Dive** 📈
**Key metrics (TTM as of latest reported Q3 ended Sep 7 2025; source: Yahoo Finance & company filings, Feb 19 2026):**
| Metric | TTM Value | YoY Growth |
|---------------------|---------------|------------|
| Revenue | $4.85B | +3.9% |
| Net Income | $589.5M | +3.1% |
| Diluted EPS | $17.24 | -2.6% (Q3 specific; full year 2024 was +13.7%) |
| Gross Margin | ~39.8% | Stable |
| Operating Margin | 19.25% | Stable |
| Net Profit Margin | 12.16% | Stable |
| Free Cash Flow | ~$631M | Positive |
**Balance sheet health (mrq):** Cash $295M, total debt/equity moderate for the sector, current ratio healthy.
**Cash flow quality:** Operating cash flow consistently exceeds net income (high quality; no major red flags).
**Capital allocation:** Consistent share buybacks + growing dividend (current yield ~1.3%); management prioritizes returning capital while funding international store growth.
**SECTION 4 — Growth Analysis** 🚀
**Total addressable market (TAM):** Global pizza market projected at ~$216B in 2026, growing to $340B+ by 2032 (CAGR ~4.5-5%; sources: Fortune Business Insights & Coherent Market Insights, Dec 2025/Feb 2026 reports). Delivery segment growing faster due to digital shift.
**Current market share:** Domino's holds the #1 position in U.S. pizza delivery (~17-20% share) and leads globally in store count and digital sales.
**Key growth drivers next 3-5 years:** International store expansion (targeting 4,000+ new stores in high-growth markets like India), continued digital innovation (AI personalization, loyalty), and menu innovation.
**Management guidance vs. analyst consensus:** Analysts expect Q4 EPS $5.36 (+YoY) and revenue $1.52B; management historically guides conservatively — analysts appear slightly more bullish on 2026 recovery.
**Organic vs. acquisition:** 100% organic growth (no major M&A).
**SECTION 5 — Valuation** 📊
**DCF analysis :** 5-year revenue CAGR 5%, EBIT margin expansion to 20.5%, WACC 8.5%, terminal growth 3% → implies fair value ~$475 (justified by historical 15-20% ROIC and digital scalability).
**Comparable company analysis (as of Feb 19 2026):**
| Peer | P/E (TTM) | EV/EBITDA | Growth Outlook |
|----------|-----------|-----------|----------------|
| MCD | 24x | 18x | Stable |
| YUM | 23x | 17x | Mid-single |
| QSR | 22x | 16x | Mid-single |
| DPZ | 22.4x | 18x | Mid-single |
**Historical valuation range (5-year):** P/E 20-30x; current 22.4x sits at lower end.
**Bull / Base / Bear targets:**
- Bull $550 (strong consumer + international beat; 35% upside)
- Base $480 (consensus growth; 19% upside)
- Bear $380 (macro slowdown; -6% downside)
Current price ~$404 (intraday Feb 19 2026 per TradingView data) vs. targets shows clear upside skew.
**SECTION 6 — Risk Analysis** ⚠️
1. **Commodity/labor inflation (High prob, Medium impact):** Trigger — rising cheese/wheat prices; watch monthly cost updates.
2. **Consumer trade-down (Medium prob, High impact):** Trigger — prolonged high interest rates; watch same-store sales.
3. **Increased competition from aggregators (Medium prob, Medium impact):** Trigger — DoorDash/Uber Eats gains; watch order mix.
4. **Foreign currency volatility (Low-Medium prob, Medium impact):** International exposure growing.
5. **Regulatory (Low prob, Low-Medium impact):** Minimum wage hikes in key states.
**Short interest:** Low (~2-3% of float; source: recent filings).
**Insider activity:** Net buying by executives in recent quarters.
**Accounting quality:** Clean; no red flags.
**SECTION 7 — Catalyst Calendar** 📅
- **Next earnings:** Feb 23 2026, BMO (Q4 FY2025)
- **Product/strategic:** Potential loyalty program enhancements or new menu items in H1 2026
- **Macro events:** Fed rate path & consumer spending data (impacts QSR traffic)
- **12-month timeline:** International store openings (monthly), Q1 earnings May 2026, potential capital return updates.
**SECTION 8 — Relevant Data & Charts** 📊
**Why it matters:** Clear long-term revenue compounding with stable margins — underpins the growth thesis heading into earnings. (Source: Simply Wall St analysis, 2025 data)
**Why it matters:** North America still dominates pizza demand — Domino's U.S. leadership position drives the majority of near-term earnings power.
**Why it matters:** Global pizza market projected to expand steadily through 2033 — validates Domino's international runway.
**SECTION 9 — Technical Analysis** 📈
**Primary Chart:** Daily timeframe, 1-year view (as of Feb 19 2026).
- Price action hugging 200-day MA after pullback from 2025 highs; testing key support ~$390-400 zone.
- RSI (14) neutral ~45 (room to run); MACD showing early bullish crossover.
- Volume profile: Highest volume node near $420 — potential magnet on positive earnings reaction.
- Visible setup: Inverse head-and-shoulders forming; breakout above $420 resistance would target $460-480 quickly.
**Technical implication:** Earnings beat + positive guidance could spark 10-15% move higher in days.
**SECTION 10 — The Verdict** 🏆
**Bull case ($550, 35% prob):** Consumer holds up + international acceleration + margin beat → 2026 guidance raised.
**Base case ($480, 50% prob):** In-line print with steady 4-5% comps; most likely scenario.
**Bear case ($380, 15% prob):** Weak guidance on macro fears triggers sell-off.
**Expected value:** (0.35×550) + (0.50×480) + (0.15×380) = **$492** (22% upside from ~$404).
**Final recommendation: Strong Buy with High conviction.**
**30-second elevator pitch:** "DPZ is the highest-quality QSR name with the best digital flywheel in the industry — earnings Monday likely confirms 2026 is back on track for mid-single-digit growth and expanding returns to shareholders."
**Sources**
- Yahoo Finance DPZ key statistics & financials (Feb 19 2026)
- EarningsWhispers & Finviz earnings calendar (Feb 19 2026)
- Fortune Business Insights / Coherent Market Insights pizza TAM reports (2025-2026)
- TradingView DPZ daily chart (Feb 19 2026)
- Analyst consensus: Public.com, Zacks, Benzinga, TickerNerd (Feb 2026 data)
- Company filings & Simply Wall St (Q3 2025 TTM data)
What are your thoughts on DPZ? Drop them below 👇 Long 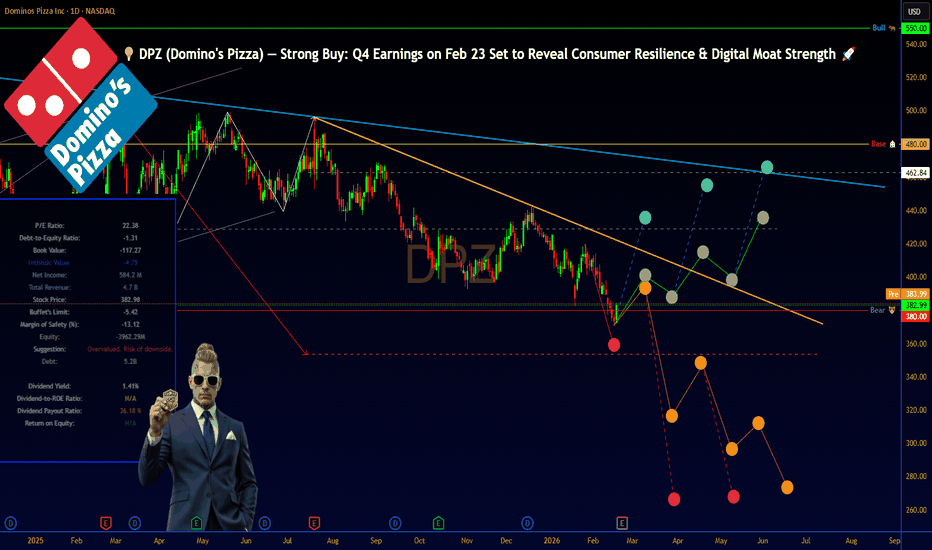
Breaking: Domino's Pizza Reports Weaker-Than-Expected Q1 RevenueShares of Domino's Pizza (NASDAQ: NASDAQ:DPZ ) moved lower in premarket trading Monday after the pizza delivery giant reported weaker-than-expected first-quarter revenue and U.S. same-store sales.
The Ann Arbor, Mich.-based company posted earnings per share (EPS) of $4.33 on revenue that increased 2.5% year-over-year to $1.11 billion. Analysts polled by Visible Alpha expected $4.04 and $1.13 billion, respectively.
Same-store sales among Domino's U.S. locations fell by 0.5% year-over-year, worse than the 0.22% bump analysts had forecast. International same store sales excluding foreign currency impacts were up 3.7%, topping the 1.88% growth analysts were expecting.
CEO Russell Weiner said the company continues to operate in a "challenging global macroeconomic environment," but said Domino's is continuing to gain market share in the U.S. and internationally.
Earlier this month, Domino's announced a new partnership with DoorDash (DASH), with the pizza chain's food set to be available through the latter's app beginning in May, once its exclusive agreement with Uber (UBER) Eats expires. Domino's has said it believes the third-party delivery market could eventually generate $1 billion in sales.
Domino's shares, which entered Monday up 16% in 2025, were down 2% shortly after the report was released.
Technical Outlook
As of the time of writing, NASDAQ:DPZ shares are down 1.66% in Monday's premarket session, albeit the earnings missed. With the RSI at 64, NASDAQ:DPZ is strong enough to hold the current resistant point. However, should selling pressure increased, shares of NASDAQ:DPZ could retraced touching the $399 support zone.
Similarly, the $500 resistant point is still in play, should the bulls take over. Long 
 Long

Domino’s Pizza Q3 Earnings Report: Revenue Misses, Earnings BeatDomino's Pizza Inc. (NYSE: NYSE:DPZ ), the largest pizza chain globally, has released its Q3 2024 financial results, revealing a mixed performance that left investors somewhat disappointed. Despite beating analyst expectations on earnings, Domino’s missed revenue estimates, causing the stock to slip. The company remains focused on its "Hungry for MORE" strategy, but the latest report underscores the challenges Domino's is facing in a pressured global marketplace.
Fundamental Overview
In Q3, Domino’s reported adjusted earnings per share (EPS) of $4.19, exceeding analyst projections of $3.63 by a significant margin. This 15.2% earnings beat reflects the strength of Domino's operations, particularly its cost management and international growth. However, revenue came in at $1.08 billion, falling short of Wall Street’s $1.1 billion estimate. This revenue miss highlights the broader industry challenges, particularly a competitive market and shifts in consumer spending.
Key Financial Metrics:
- Revenue: $1.08 billion (5.1% YoY growth, but 1.6% below expectations)
- EPS: $4.19, beating the $3.63 consensus
- Global Retail Sales Growth: 5.1% YoY, excluding currency impacts
- Same-Store Sales: U.S. up 3.0%, International up 0.8%
- Operating Income Growth: 5.7%, excluding FX impacts
- Net Store Growth: 72 new locations globally in Q3
While the growth in same-store sales and net store expansion demonstrates Domino’s resilience, the revenue shortfall suggests there may be limitations to growth in a highly competitive fast-food market. Additionally, rising operating costs and fluctuations in foreign exchange rates have impacted Domino’s international operations.
2024 Guidance and Future Outlook
Domino’s maintained its full-year 2024 guidance, projecting approximately 6% global retail sales growth and 8% growth in operating income. These targets align with the company’s consistent expansion strategy, which includes adding 800 to 850 new stores globally by year’s end. For 2025, the company expects sales and income growth to be broadly in line with 2024 projections, signaling confidence in its long-term strategy.
However, the revenue miss, combined with the challenges of maintaining growth in mature markets like the U.S., has caused some investors to reassess Domino’s trajectory. Domino’s already boasts 21,002 locations globally, making incremental growth more challenging.
Technical Outlook
From a technical perspective, Domino’s stock has entered a bearish zone following the release of its Q3 earnings. As of the time of writing, NYSE:DPZ has dropped 2.52%, with the Relative Strength Index (RSI) sitting at 35, approaching the oversold region. This signals that the stock could be nearing a critical support level but is not yet undervalued enough for a bullish reversal.
Key technical indicators point to further weakness:
All major moving averages depict a bearish tone, with the stock trading below its 50-day and 200-day moving averages. This suggests downward momentum in the short to medium term.
The daily price chart shows a gap-down pattern that has yet to be filled, creating a technical overhang that could pressure the stock further.
NYSE:DPZ is also trading within a falling wedge channel, a pattern often associated with continued downward momentum until a breakout occurs. A dip towards the $355 pivot could lead to a significant selloff, potentially triggering a broader decline if support levels fail to hold.
If Domino's stock fails to find support at current levels, it could face further downside, especially given the broader headwinds in the fast-food sector, including inflationary pressures and changing consumer preferences.
Conclusion
While Domino's continues to execute its growth strategy effectively, as evidenced by strong EPS growth and net store expansion, the revenue miss in Q3 signals challenges ahead. The stock's current technical outlook suggests caution is warranted, particularly as NYSE:DPZ nears critical support levels. Investors should watch for a potential bounce if the stock hits oversold territory, but the risk of further downside looms if the broader market sentiment remains negative.
In the long term, Domino’s focus on expansion and operational improvements may help it navigate current headwinds, but short-term technical signals and the revenue shortfall indicate that the stock could face more turbulence before recovering. D

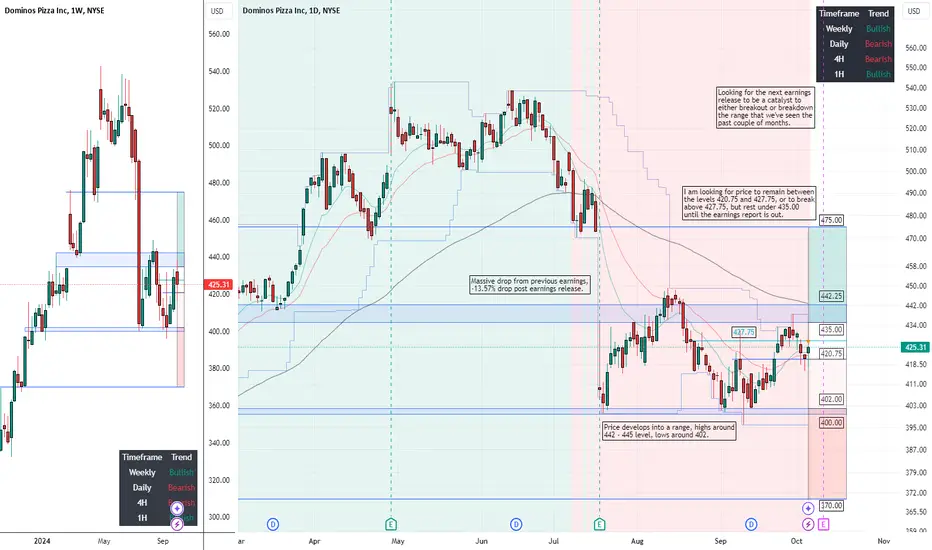
DOMINOS PIZZA $DPZ | RANGE BREAKOUT AFTER EARNINGS? - Oct 06 '24DOMINOS PIZZA NYSE:DPZ | RANGE BREAKOUT AFTER EARNINGS? - Oct 06 '24
BUY/LONG ZONE (GREEN): 435.00 - 475.00
DO NOT TRADE/DNT ZONE (WHITE): 420.75 - 435.00 (can be extended to 402.00 - 435.00)
SELL/SHORT ZONE (RED): 370.00 - 402.00 (can be extended to 370.00 - 420.75)
Weekly: DNT
Daily: Bearish
4H: Bearish
NYSE:DPZ saw a massive drop from previous earnings, -13.57% drop post earnings release. Price then develops into a range, highs around 442 - 445 level, lows around 402. I am looking for the next earnings release (Oct 10, pre market) to be a catalyst to either breakout or breakdown the range that we've seen the past couple of months. I am looking for price to remain between the levels 420.75 and 427.75, or to break above 427.75, but rest under 435.00 until the earnings report is out.
This is what I would personally look at before entering trades, everything is subject to change on a daily basis and as I analyze different timeframes and ideas.
ENTERTAINMENT PURPOSES ONLY, NOT FINANCIAL ADVICE!
trendanalysis, trendtrading, priceaction, priceactiontrading, technicalindicators, supportandresistance, rangebreakout, rangebreakdown, rangetrading, chartpatterntrading, chartpatterns, spy, sp500, s&p, fed, federalreserve, dominos, dominospizza, dpz, NYSE:DPZ , dominosearnings, earningsplay, earningstrade, dominospizzaearnings, dominospizzarange, rangetrade, earningssetup, dominospizzatrade, dominostrade, dpztrade, dpzearningsrelease, dominosiv, dominosoptions, dpzoptions, dpziv, D

Domino’s Pizza Stock Rises 4.73% on Earnings BeatDomino's Pizza ( NYSE:DPZ ) sizzles in the first quarter, serving up a mouthwatering performance that leaves investors craving for more. With a strategic blend of innovative initiatives and strategic partnerships, the world's largest pizza chain surpasses expectations, sending its shares soaring in early trading.
Loyalty Program and Uber Eats Partnership Drive Growth
The secret ingredients behind Domino's recipe for success? A revamped Domino's Rewards loyalty program and a lucrative partnership with Uber Eats. CEO Russell Weiner attributes the chain's stellar performance to the revamped loyalty program, which enticed customers with irresistible rewards. Moreover, Domino's foray into marketing on Uber Eats proved to be a game-changer, opening new avenues for sales growth. Weiner's bullish outlook suggests that Domino's anticipates ending the year with a significant uptick in sales, thanks to this strategic collaboration.
Impressive Financial Performance
Domino's earnings report leaves investors craving more, with diluted earnings per share soaring to $3.58, marking a remarkable 22.2% increase from the year-ago period. Revenue also witnessed a robust uptick, surging 5.9% year-over-year to $1.08 billion. These stellar figures not only exceed analyst estimates but also underscore Domino's unwavering dominance in the fiercely competitive pizza delivery market. With same-store sales up by an impressive 5.6%, Domino's solidifies its position as a leader in the industry, leaving competitors in the dust.
Expansion and Growth Projections
Domino's appetite for growth shows no signs of slowing down, as evidenced by the addition of 164 stores in the quarter, bringing its total store count to a whopping 20,755. The company remains steadfast in its commitment to expansion, reiterating its full-year guidance of sales growth exceeding 7% and the addition of 1,100 or more net stores. This bullish projection reflects Domino's confidence in its ability to capitalize on emerging opportunities and navigate challenges in the dynamic food delivery landscape.
Market Response and Future Outlook
Investors devour Domino's impressive performance, driving its shares up by 3.5% in early trading. The stock's remarkable ascent, gaining approximately one-quarter of its value since the start of 2024, underscores investor confidence in the company's growth trajectory and strategic initiatives. As Domino's continues to innovate and expand its footprint, the future looks promising for the pizza giant, with shareholders eagerly anticipating the next slice of success in its delectable journey.
Technical Outlook
Domino's Pizza stock ( NYSE:DPZ ) is trading high above the 200, 100, and 50-day Moving Average (MA) respectfully. Domino's Pizza stock ( NYSE:DPZ ) has a Relative Strength Index (RSI) of 70.80 creating further room for reaching the pivot point at $560. Domino's Pizza (DPZ) Serves Up Tasty Returns with Strong EarningDomino's Pizza ( NYSE:DPZ ) has once again delivered a delectable performance, serving up better-than-expected fourth-quarter earnings and announcing a significant dividend increase, sending its shares soaring higher. The renowned restaurant chain's robust financial results underscore its resilience and strategic initiatives amidst a dynamic market landscape, propelling investor confidence and setting the stage for continued growth.
In the fourth quarter, Domino's Pizza ( NYSE:DPZ ) showcased its prowess by reporting earnings per share (EPS) of $4.48, surpassing analyst estimates of $4.38, while revenue edged slightly lower than expectations, standing at $1.403 billion. Despite the marginal revenue miss, the company's same-store sales surged 2%, driven by a remarkable 2.8% growth in U.S. comparable sales, outperforming Wall Street's projections and highlighting the strength of its domestic operations.
Not content with merely exceeding earnings forecasts, Domino's Pizza ( NYSE:DPZ ) demonstrated its commitment to shareholder value by approving a substantial 25% increase in its quarterly dividend, elevating it to $1.51 per share. This move reflects the company's confidence in its financial position and long-term prospects, bolstering investor sentiment and underscoring its dedication to returning capital to shareholders.
Furthermore, Domino's Pizza ( NYSE:DPZ ) unveiled an ambitious $1 billion share repurchase program, reaffirming its commitment to optimizing capital allocation and enhancing shareholder returns. With a track record of prudent financial management, the company has consistently generated robust free cash flow, reaching $485.5 million in 2023, a significant increase from the previous year despite higher capital expenditures.
Investors welcomed the positive news with enthusiasm, propelling Domino's Pizza ( NYSE:DPZ ) stock to a 5.3% surge during premarket trading. With shares poised to break through key resistance levels and reach heights unseen in nearly two years, the company's strong operational performance and shareholder-friendly initiatives are resonating positively with market participants.
Looking ahead, Domino's Pizza ( NYSE:DPZ ) remains focused on its long-term growth trajectory, as evidenced by its updated guidance presented during its investor day. The company anticipates annual retail global sales growth of "more than 7%" through 2028, coupled with aggressive expansion plans, including the addition of over 1,100 new stores. Moreover, Domino's aims to achieve more than 8% annual operating income growth, signaling a robust outlook for profitability and value creation.
In conclusion, Domino's Pizza's ( NYSE:DPZ ) stellar fourth-quarter performance, highlighted by impressive earnings, dividend hike, and share repurchase program, underscores its resilience and strategic vision in navigating evolving market dynamics. With a solid foundation and a commitment to delivering value for shareholders, Domino's Pizza ( NYSE:DPZ ) is poised to continue its journey of success and remain a dominant force in the ever-changing landscape of the food industry.  Short

D

D

DPZ (Domino's Pizza) Short: Bearish divergence and upwicks #0003Weekly: Closed lower, after upwick, impulse is blue (meaning MACD-H ticking down). Latest top diverging with previous local top. Often times, the 2.5 ATR level is a turning point for tops.
Daily: A nice set of divergences, on MACD lines, MACD-Histogram, and EFI. Even there is a divergence on Stochastic RSI, as well as ATR lines, showing an ATR channel divergence (see the two purple arrows). .
We can also see 2 long upwicks, supporting the idea that bulls run out of steam and the selling pressure comes in, as these price levels are rejected, and end of day closes close to the open price.
The entry can be either here, but I will wait the market open first, to see how it opens. I will post a chart on how I think I can enter, on a shorter Timeframe
Stoploss will be place somere halfway the upwick of the previous candle, around 465,1
Entry: 457
Target 1: 444,1
Target 2: 439,1
SL: 465,1
R/R ratio: 1:1.6, 1:2.1